


Mirion Technologies (MIR) Stock Can Q3 Results Justify Thin Margins
Mirion Technologies stock slipped 1.6% to US$18.37 in Friday trading, a muted reaction for a business that just posted a muscular Q3 2026 revenue figure of US$277.8 million and a trailing twelve month net profit margin of 2.7%. On the screen the move looks like fatigue after a strong month. Over a multi year period, the story is about a company pouring cash into nuclear power, artificial intelligence and cybersecurity, accepting near term margin pressure so that future earnings growth and a richer backlog can carry more weight than today’s modest profit rate.
Love Mirion Technologies’ nuclear, AI and cybersecurity exposure but concerned that a 2.7% net margin leaves little room for error right now? Compare it against peers with stronger profitability and balance sheets in our list of solid balance sheet and fundamentals stocks (25 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$277.8 million vs. US$223.1 million (up roughly 24.5% year on year, reflecting stronger top line scale for Mirion Technologies)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$7.4 million vs. US$2.9 million (higher quarterly profit in absolute terms, off a relatively small base)
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.0305 vs. US$0.0129 (earnings per share more than doubled on a quarterly comparison)
- Adjusted EBITDA Margin (Q3 2026 vs. Q3 2025): 23.3% vs. 23.5% (slight margin compression despite stronger revenue and adjusted EBITDA growth)
Earnings tell part of Mirion Technologies' story, but cash flows show how much real money is available to service debt, reinvest and ultimately support shareholder value over time. When you line up Mirion Technologies' cash generation against its current share price, the stock could be a slight 9% undervalued.
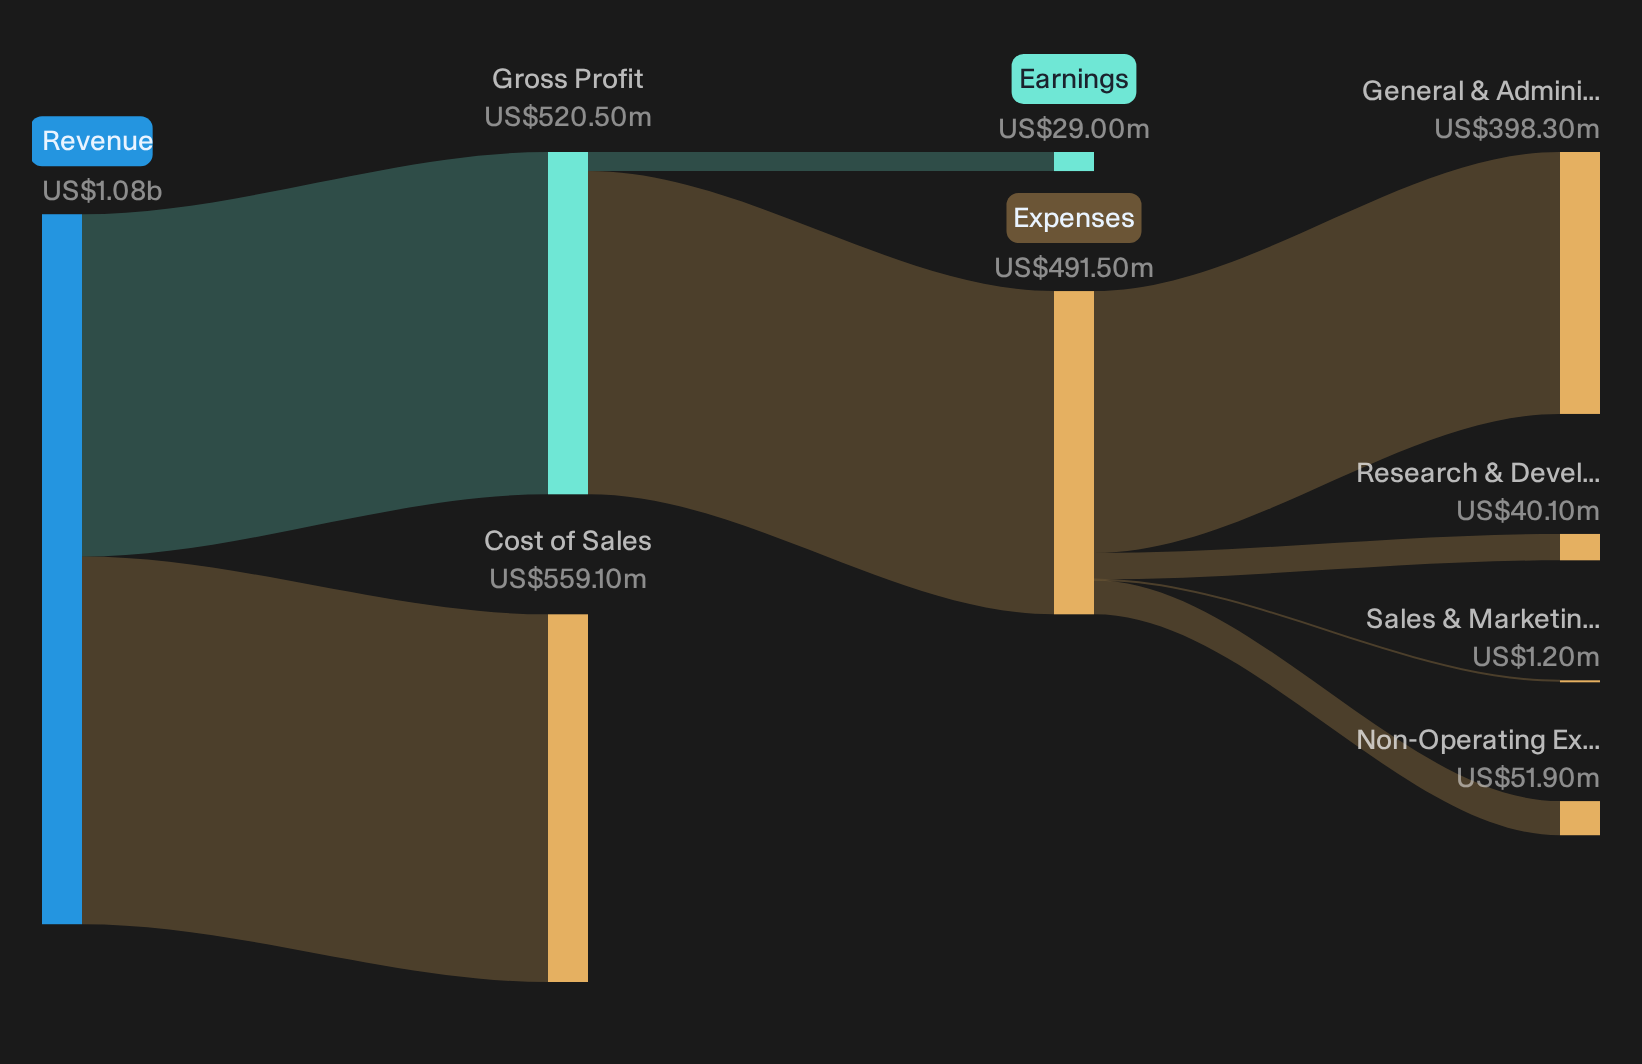
Mirion Bull Case Meets Nuclear Order Reality
Optimists argue Mirion Technologies is building a higher quality, more recurring business as nuclear and digital projects compound.
"Continued rollout of new digital platforms, such as the Vital and Apex-Guard software, along with the strategic Certrec acquisition (bringing SaaS-based, AI-enabled compliance tools), positions Mirion to capture premium pricing, drive software mix expansion, and unlock operating leverage, benefitting margins and long-term earnings potential."
Q3 order growth of 62% excluding acquisitions and a US$1.25b backlog, with nuclear orders more than doubling, show the demand side showing up. Yet adjusted EBITDA margin held roughly flat and net margin sits at 2.7%, so operating leverage is not visible yet.
Bear Case Tests Margin And Concentration Risks
Skeptics focus on nuclear exposure and integration risk, and recent results give some backing to that worry.
"Mirion's acquisition-led growth strategy, including the recent Certrec purchase, increases execution and integration risks. Failure to realize expected synergies or elevated SG&A expenses may compress net margins and dilute earnings quality over the long term."
Management has already walked back an earlier 2028 margin ambition and now talks about 1 to 2 percentage points of annual expansion. Nuclear and Safety margins are being hit by legacy Paragon project costs, while AI and cybersecurity spending is running higher. Net margin at 2.7% leaves limited cushion if nuclear orders or integration work slow.
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all.
Hunt For Quiet Dislocations
Mirion Technologies shows how a full order book and thin margins can limit momentum. The real opportunity sits in finding companies that could be undervalued before the market closes the gap.
- Company 1 - 38% below our estimate - uses new high horsepower capacity and engine platforms to pursue long data center power contracts.
- Company 2 - 37% below our estimate - leans on AI enabled freight tools and stricter carrier screening to move heavier specialized loads through its agent network.
- Company 3 - 46% below our estimate - turns a near record construction backlog of large projects into targeted cash generation while working through dispute liabilities.
Three companies from the same screener. Open all 29 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com