


Oshkosh (OSK) Stock Climbs As Q3 Results Expose Margin Pressure
Oshkosh just released its Q3 2026 results and the stock responded immediately. Shares closed at US$139.91, up 3.4% on the day, even though quarterly earnings per share of about US$2.24 and net income of US$138.4 million came in well below the prior quarter.
The price move underscores how important sentiment is today. Traders are focusing on strong free cash flow and the raised 2026 cash generation outlook while looking past a clear profit squeeze in the core operations. The gap between that optimism and the margin pressure is the key dynamic for Oshkosh right now.
Love Oshkosh’s cash generation but concerned about the earnings squeeze in the core business operations? You can compare that mix of strong free cash flow and cleaner profitability with the stocks in our list of solid balance sheet and fundamentals stocks (25 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$2,841.6 million vs. US$2,688.6 million (up about 5.7%)
- Net Income (Q3 2026 vs. Q3 2025): US$138.4 million vs. US$196.2 million (down about 29.4%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$2.24 vs. US$3.06 (fell roughly 26.9%)
- Trailing 12-month Net Margin (Q3 2026 vs. prior year): 4.6% vs. 6.4% (compressed by about 1.8 percentage points)
Tired of skimming Oshkosh earnings and still feeling buried in raw numbers and footnotes? Get a clear visual picture of how the business earns, spends, and reinvests its cash with our full financial breakdown in the company report for Oshkosh.
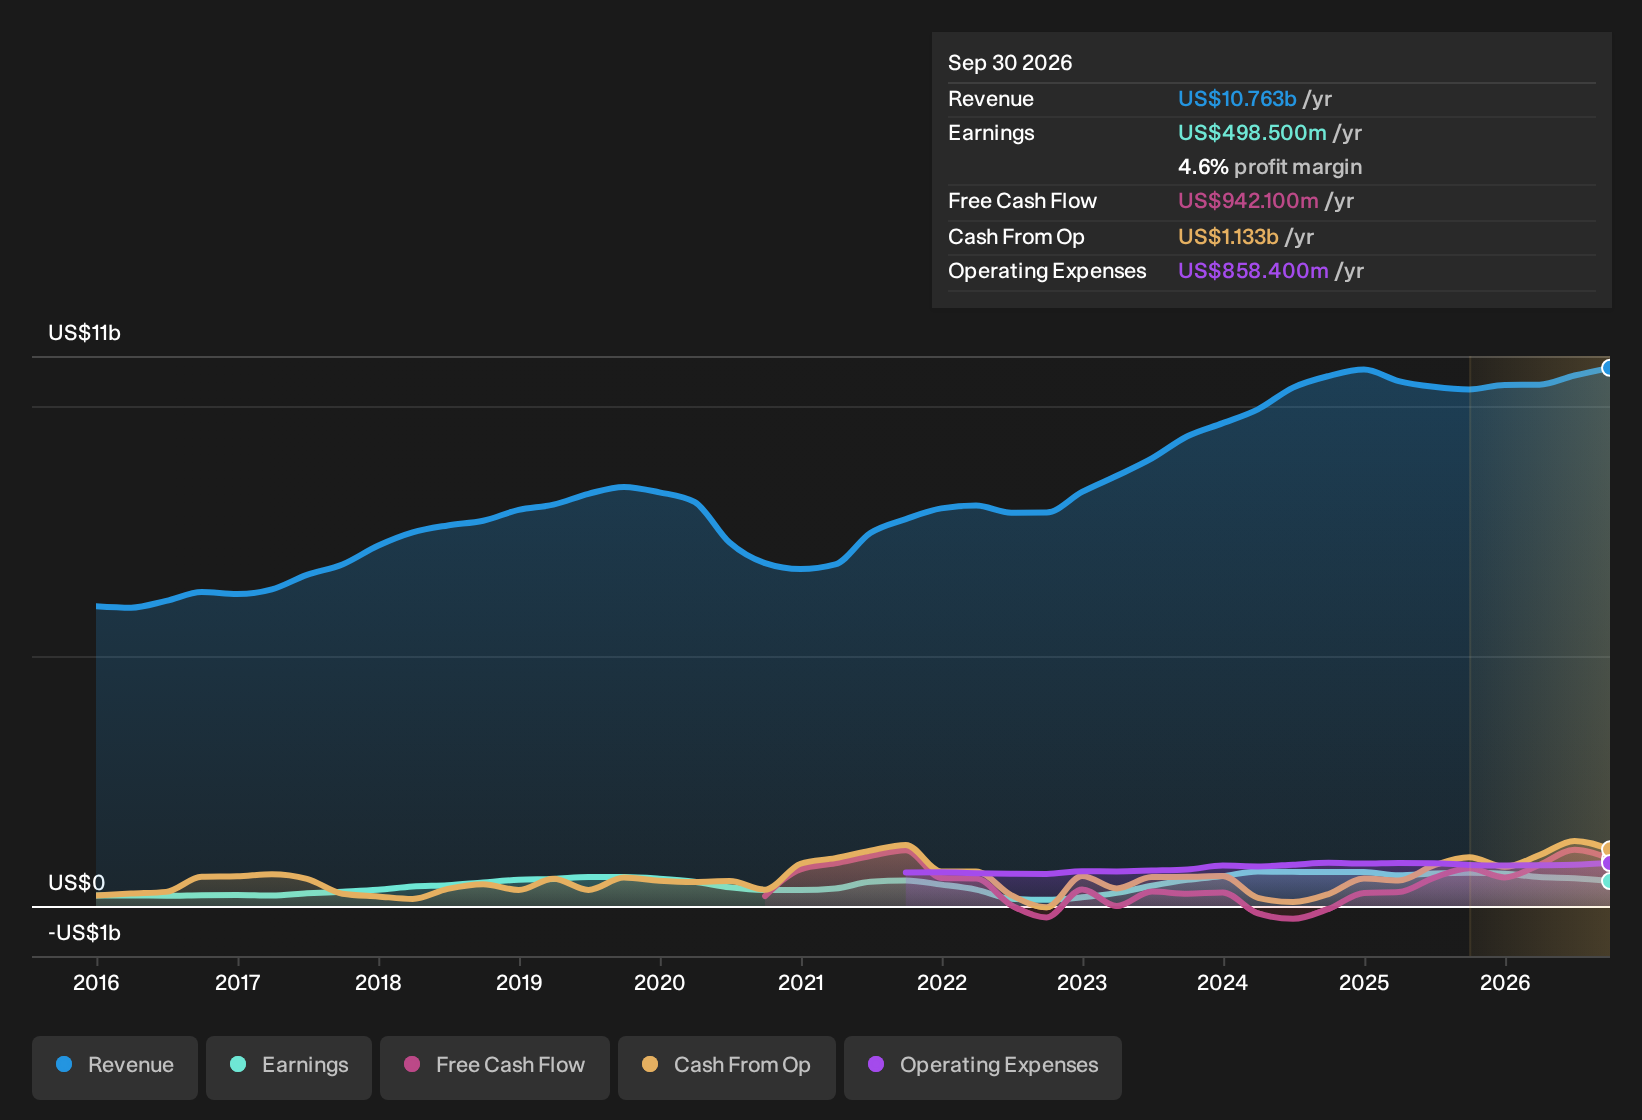
Oshkosh Bull Case Hinges On Execution Milestones
The bullish view hangs on Oshkosh turning ambitious manufacturing and contract plans into tangible earnings power. One of the clearest statements of intent sits around Vocational fire.
"A key requirement for this view is Oshkosh executing its manufacturing and product roadmap, including the Vocational fire capacity ramp, technology rollouts and repriced Defense and NGDV contracts, while keeping tariff and input cost pressures broadly neutral through engineering and pricing actions."
Q3 shows mixed progress against that roadmap. Access just delivered US$1.3b of sales with double digit margins and strong orders, matching the upgraded Access narrative. Vocational fire is lagging, with fire truck shipments about 20% below last year and EPS guidance cut, so the capacity ramp is not yet a completed milestone. Free cash flow, at US$275 million in Q3 and higher full year guidance of US$600 million to US$700 million, is the clearest box ticked so far.
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for.
Oshkosh Bear Case: Execution Wobbles Trump Strong Demand
Bearish investors question whether Oshkosh can translate a healthy order book into clean earnings while fire production and NGDV execution stay messy.
"Despite the multi year, roughly US$150 million Pierce fire truck modernization intended to lift throughput and Vocational margins, the cut to 2026 adjusted EPS guidance from US$11.50 to about US$11.00 and the continued three to four year fire truck lead times indicate that execution risk is already deferring expected volume and margin gains. This could mean Vocational segment margins and overall EPS track below current targets for longer."
Q3 results validate that concern. Vocational sales of US$900 million fell year on year as Pierce shipments dropped about 20%, and 2026 EPS guidance is now US$8.50 to US$9.50, below earlier levels. NGDV is progressing but still constrained by suppliers. Free cash flow strength and Access double digit margins suggest that demand and cash generation are intact. The core bear worry is execution timing, and that risk is clearly showing up in this quarter’s numbers and guidance reset.
Hunt For The Next Disconnect
Oshkosh shows how cash strength can sit alongside pressure in core earnings. The real opportunity is finding stocks that could be undervalued before the market adjusts.
- Company 1 - 38% below our estimate - focuses on expanding branded and private label coconut drinks while holding pricing power against rising input costs.
- Company 2 - 31% below our estimate - leans into large-scale AI infrastructure builds after winning supercluster workloads needing extra multi cloud capacity.
- Company 3 - 34% below our estimate - turns long term contracts and customer prepayments in optical networks and solar materials into a targeted margin and returns uplift plan.
That is three of the list. See every one of the 30 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com