


3 Oil Refining Stocks To Watch As Brent Crude Nears $120
Oil markets are back in the spotlight, with Brent crude hovering near $120, shipping routes under threat and governments releasing emergency reserves to keep fuel costs in check. That mix of pressure and profit potential is reshaping expectations for integrated oil and refining stocks. This article explains how those headlines affect the sector and profiles 3 stocks exposed to these shocks that investors may want to keep on their radar.
The three stocks highlighted next are just a sample of what rises to the surface when you filter global integrated oil and refining companies. The full screen surfaces 24 more businesses with equally compelling stories that are not covered in this article. If you want to identify your own highest conviction ideas in this corner of the market, head straight into the Global Integrated Oil & Refining Companies screener to filter and analyze the full list on your own terms.
Delek US Holdings (DK)
Overview: Delek US Holdings is a U.S. downstream energy company that runs refineries and logistics assets to turn crude oil into gasoline, diesel and other fuels.
Operations: Delek US Holdings generates about US$11.9b from refining and US$1.2b from logistics, with virtually all revenue coming from the United States.
Market Cap: US$4.4b
Delek US Holdings is one of the purest ways to tap the integrated oil and refining theme, with earnings closely tied to crack spreads, crude differentials and product pricing, which is exactly where current energy market stress is most visible.
"Delek's sustained operational improvements, driven by its enterprise optimization program (EOP), which targets structural changes in refinery operations, procurement, and product sales, are expected to deliver $130 to $170 million of annualized cash flow enhancements, with much of the benefit expected to flow through to net margins and free cash flow starting in the second half of 2025."
What really matters for Delek US Holdings now is how one less visible pressure on refining margins ultimately feeds through to cash generation.
That makes the real question how this cash engine behaves once the refinery tweaks and pricing pressures fully bite, which is exactly what the full narrative for Delek US Holdings unpacks, including where expectations may be misaligned.

OPAL Fuels (OPAL)
Overview: OPAL Fuels produces renewable natural gas and related fuels for heavy trucking fleets, supported by fuel stations and renewable power assets.
Operations: OPAL Fuels generates about US$240 million from Fuel Station Services, US$95 million from RNG Fuel and US$31 million from Renewable Power, all in the United States.
Market Cap: US$285 million
OPAL Fuels links this integrated oil and refining screen to the cleaner end of the fuel spectrum. This provides exposure to energy pricing while tying that exposure to how quickly trucking operators shift away from diesel and into renewable natural gas.
"The company plans to market and distribute the full output from the new RNG facilities through its RNG/CNG fueling station network, targeting heavy-duty trucking fleets that are replacing diesel with RNG and CNG."
The real swing factor for OPAL Fuels is how one evolving policy and credit backdrop ultimately feeds through to cash margins.
That policy overhang is exactly where the story gets interesting, and the full narrative for OPAL Fuels shows how OPAL Fuels could turn shifting credits into accelerating cash generation.

Chennai Petroleum (BSE:500110)
Overview: Chennai Petroleum refines crude oil in India into fuels and specialty petroleum products, giving investors direct exposure to refining margins.
Operations: Chennai Petroleum generates about ₹804.3b in revenue from its Petroleum Sector, reflecting a focused downstream refining business model.
Market Cap: ₹225.0b
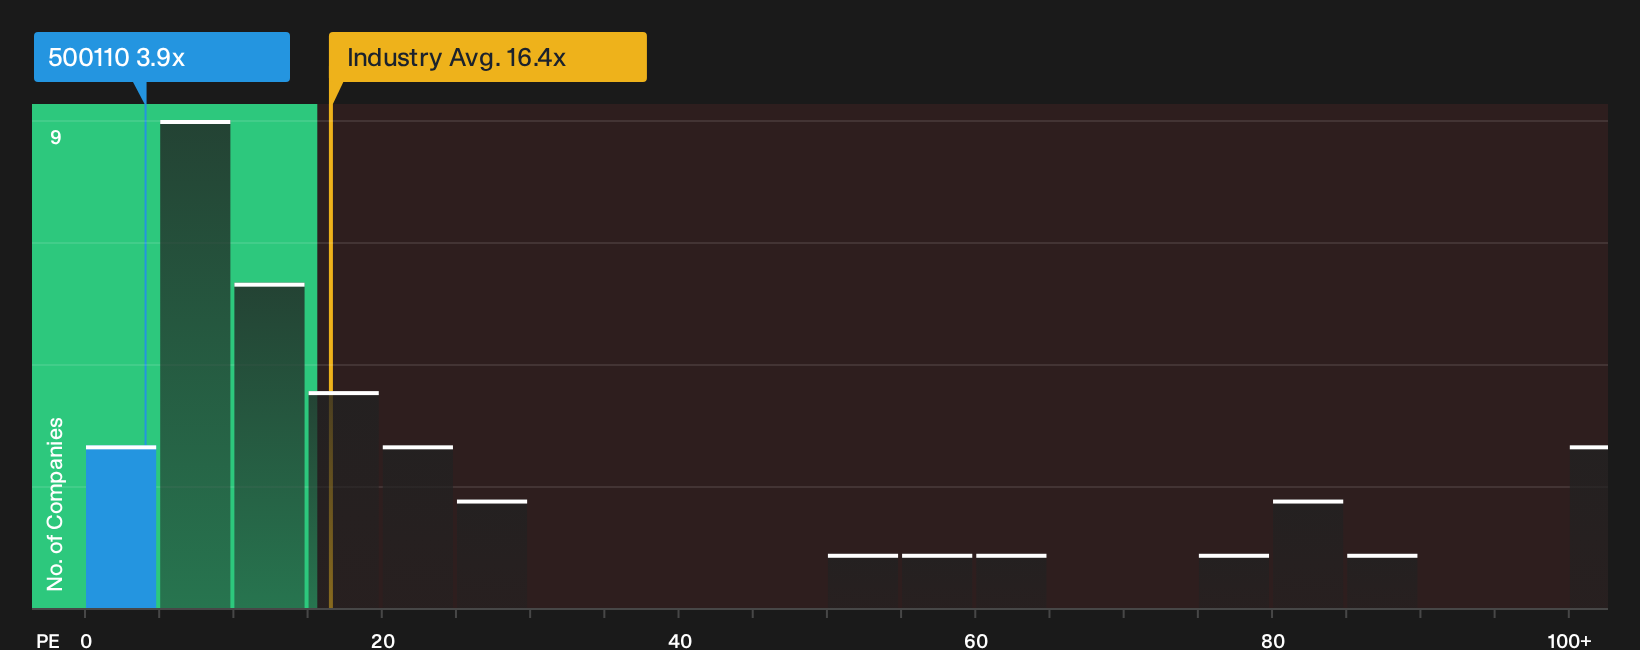
For an integrated oil and refining theme, Chennai Petroleum provides exposure to Indian fuel pricing, crude input costs and gross refining margins, while combining a low P/E around 3.9x with recent profitability and a 4.1% dividend yield that depends heavily on how one pressure point in those refining spreads behaves from here.
If you want to see how that pressure point really affects Chennai Petroleum's valuation and risk profile, go straight to the analysis report for Chennai Petroleum for the full picture.
Seeking Fresh Alternatives Beyond Oil?
New opportunities can move from under the radar to flying out of reach fast. Scan these fresh ideas before the crowd catches on and act now.
- Explore potential income momentum and target cash flow resilience by screening for proven yield plays through the 5 dividend fortresses while payout strength still appears to be mispriced.
- Identify potential early leaders in AI infrastructure and consider positioning before sentiment fully shifts by reviewing the curated 54 AI infrastructure stocks while it remains relatively under the radar.
- Focus on companies with strong balance sheets and lower risk profiles by filtering candidates via the list of solid balance sheet and fundamentals (25 results) before quality-related premiums change and selected entry points become less available.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com