


Will Slower First Half Growth Change Volex's (LSE:VLX) Narrative
- Volex reported that revenue growth in the first half of its fiscal year slowed while it continued to push further into higher margin, complex manufacturing areas such as electric vehicle charging, medical devices and industrial technology.
- This slower top line momentum increases scrutiny on how effectively Volex can convert its shift toward more complex work into operational efficiency, pricing discipline and productive use of its manufacturing capacity.
- We will now see how Volex's investment narrative might be affected by the slower first half revenue growth reported this year.
Balance your view on Volex's slower first half by scanning 12 high quality undervalued stocks which may also be trying to convert operational execution into better margins and more resilient cash flows.
Volex Investment Narrative Recap
To back Volex as a shareholder, you have to believe the shift into complex industrial, EV charging and medical work can keep supporting margins even when top line momentum cools. The slower first half growth puts that thesis under the microscope, because it tests how resilient the higher mix, higher complexity portfolio really is.
The near term catalyst still lies in execution on existing programs. Investors are watching how management handles pricing, cost control and factory utilisation while Consumer Electricals faces tougher competition and Murat Ticaret integration and Turkish cost inflation remain live issues. If operations hold up, the recent revenue wobble may not be a major break in the story.
With no fresh regulatory filings or deal announcements tied directly to this slowdown, the most relevant recent signal is management’s previously stated ambition to reach around $2b of revenue within five years using both organic growth and acquisitions. That target now meets a more demanding test from the latest numbers.
The short term read through is simple. Slower first half sales make organic growth and margin delivery even more important while acquisition valuations are described as higher and the deal pipeline has not produced a transaction after about 50 reviews. Execution on existing EV, data center and industrial programs therefore carries more weight as a day to day catalyst for Volex.
What The Current Volex Forecasts Assume
Volex's current analyst narrative leans on a fairly clear set of numbers. Consensus work suggests annual revenue growth assumptions of 9.2% for the next few years and a lift in profit margins from 5.3% today to 6.5% by year three. That view sits in the background when you weigh the first half slowdown, because it outlines what would need to happen in the broader business for the recent wobble not to matter much over a multi year period.
On earnings, the gap between today and the outer year target is material. Analysts are looking for profit of $65.8 million at present to rise to $105.6 million by around 2029, with the more optimistic views stretching as high as $121.8 million. The central case implies an earnings increase of about $39.8 million, which is what would need to be delivered through a mix of better margins, higher utilisation and careful cost discipline even if top line growth cools at times along the way.
Those earnings expectations tie directly into the long term revenue frame. The same set of forecasts couples that $105.6 million profit figure with 2029 revenue of $1.6b, using the 9.2% annual revenue growth assumption as the bridge from where Volex is today. In plain terms, the analyst view is that more complex EV, data center and industrial work can support that jump in both sales and profitability if execution holds together.
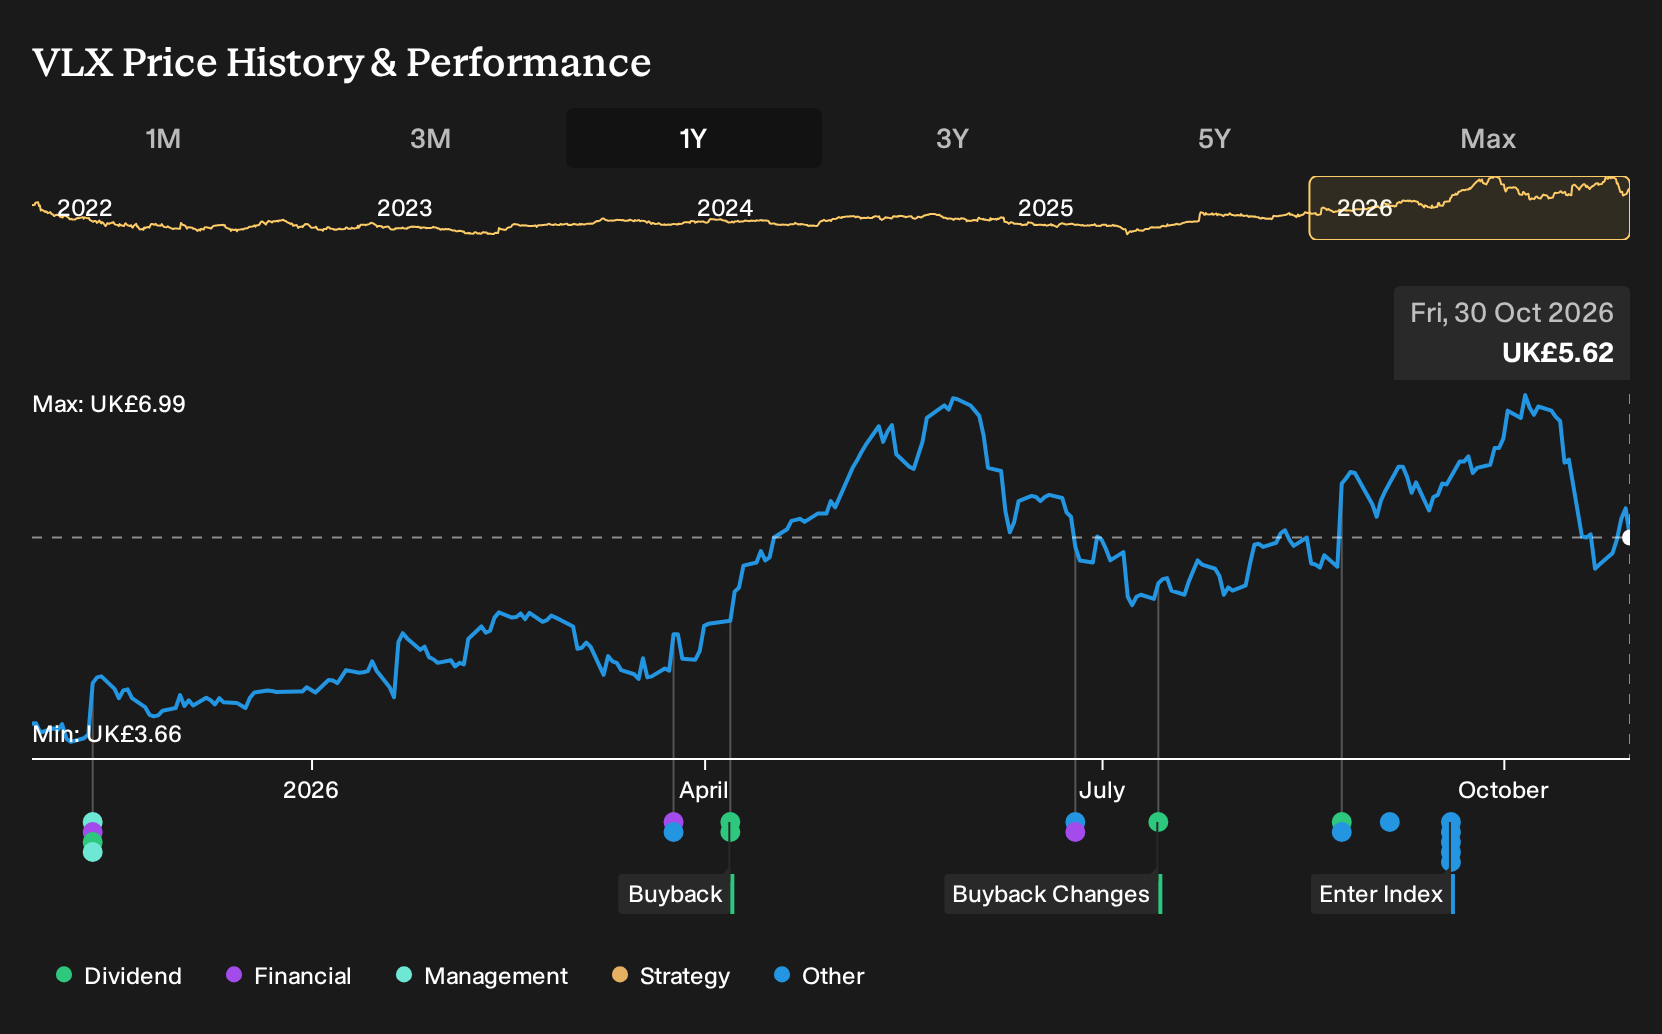
For valuation, the story is just as specific. The consensus price target of £7.29, compared with a current share price of £5.36, is built on those 2029 expectations of $1.6b in revenue and $105.6 million in earnings, along with a P/E multiple of 23.1x on those future profits. That multiple sits a touch above the 23.0x level quoted for the wider GB Electrical group and above the current 19.7x for Volex itself, so the market would need to maintain or award a richer earnings multiple even as the business scales.
Volex's narrative projects $1.6b revenue and $105.6 million earnings by 2029. This relies on 9.2% yearly revenue growth and an earnings increase of about $39.8 million from $65.8 million today.
Uncover why Volex's fair value indicates a 30% potential upside to its current price, which could narrow quickly as expectations adjust.
Exploring Other Perspectives
You now have two very different stories about Volex in front of you. The most optimistic analysts pinned forecasts on revenue reaching about $1.7b and earnings of roughly $119.7 million by 2029, leaning heavily on AI data center demand as a key catalyst. With today’s slower first half update, those pre news assumptions may shift. Treat them as one viewpoint and explore several others before deciding what feels reasonable to you.
Explore 3 other Volex fair value estimates, including one that suggests there may be as much as 50% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Volex research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Volex. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Volex's overall financial health at a glance.
Looking for more investment ideas beyond Volex?
If the Volex story has sharpened your thinking about margins, balance sheets and future cash flows, use that same lens to scan a wider universe of opportunities with the Simply Wall St Screener.
- If you want potential value combined with quality fundamentals, start with 12 high quality undervalued stocks that already clear basic cash flow and balance sheet checks.
- If balance sheet strength is your first filter, focus on companies in the list of solid balance sheet and fundamentals (10 results) to see which businesses pair financial resilience with consistent fundamentals.
- If you are hunting for less crowded situations with sound metrics, the 5 high quality undiscovered gems can surface quieter opportunities that still show solid financial underpinnings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com