


China Zheshang Bank (SEHK:2016), What Is Behind The Fresh Attention?
China Zheshang Bank (SEHK:2016) just posted nine-month earnings through September 30, 2026, reporting net interest income of CNY 33,422 million and net income of CNY 11,780 million, which is keeping investor attention squarely on the stock.
At a share price of HK$2.37, China Zheshang Bank has seen a 2.60% 7 day share price gain, yet the share price return is still down 6.32% year to date, while the 3 year total shareholder return of 48.61% points to momentum that has built over a longer horizon as today’s earnings keep the recent move in focus.
Scan beyond China Zheshang Bank and compare its steady earnings profile with a curated 220 resilient stocks with low risk scores that may appeal if you are focusing on stability and resilience.
After a small rebound in China Zheshang Bank following steady nine month earnings, the real tension is simple: Is this a reasonable entry now, or does patience for a cheaper valuation make more sense?
Preferred P/E of 4.6x: Is it justified?
Valuation on China Zheshang Bank is anchored by a P/E of 4.6x at the HK$2.37 share price, and that figure sits below both Hong Kong banks and its direct peer group according to the latest Simply Wall St checks.
The P/E ratio compares what you pay today for each unit of earnings that the bank generates. For a lender like China Zheshang Bank, where profitability and capital strength matter more than headline revenue growth, this metric gives you a quick sense of how the market is treating those earnings relative to other banks on the same exchange.
There is a split picture. Earnings over the past year declined 12.7%, and net profit margins moved from 35.5% to 31.4%. At the same time, profits have still grown by 2.1% per year over the past five years and Simply Wall St currently classifies those earnings as high quality, which can matter when judging whether a low P/E reflects short term pressure or a deeper issue.
The comparison line is clear. A 4.6x P/E is described as good value versus the Hong Kong Banks industry average of 5.1x, and it is also flagged as attractive against a broader peer group average of 8.9x. That is a sizeable gap, and it suggests the market is applying a heavier discount to China Zheshang Bank’s earnings than to many similar lenders.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 4.6x (UNDERVALUED)
Still, China Zheshang Bank faces pressure if credit quality weakens or if slower fee income from corporate or retail clients reduces its earnings appeal.
Find out about the key risks to this China Zheshang Bank narrative.
Another view on China Zheshang Bank’s value
The P/E points one way, but the Simply Wall St DCF model is stronger. At HK$2.37, China Zheshang Bank is compared with an estimated cash flow value of HK$6.64, which flags the shares as heavily undervalued. The key consideration is whether you place more weight on current earnings or on long term cash flows.
Look into how the SWS DCF model arrives at its fair value.
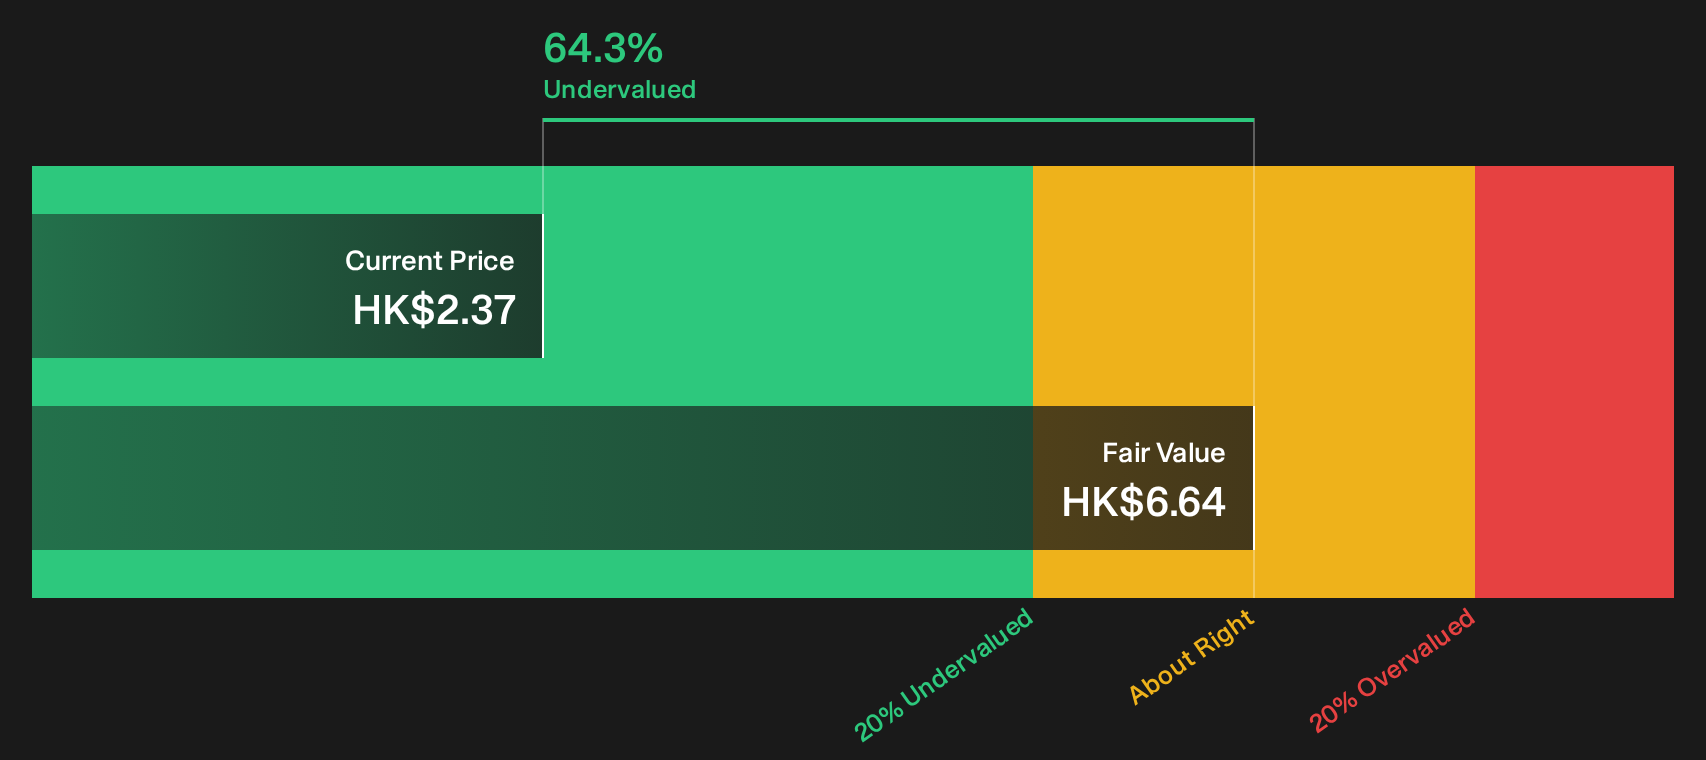
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out China Zheshang Bank for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 201 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around China Zheshang Bank can be confusing, so treat this as a starting point and pressure test the numbers yourself. Then weigh both sides using the 1 key reward and 1 important warning sign
Looking for more investment ideas beyond China Zheshang Bank?
If China Zheshang Bank has your attention, do not stop here. Use the same disciplined lens across a broader watchlist so you are not reliant on one story.
- Target potential mispricings by scanning a curated set of quality companies through the 201 high quality undervalued stocks which filters for both strength and attractive pricing.
- Strengthen your income stream by reviewing the 222 dividend fortresses and focus on payouts that aim to combine yield with balance sheet support.
- Lock in a shortlist of financially resilient businesses using the list of solid balance sheet and fundamentals (202 results) which filters for robust fundamentals and lower financial risk.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com