


Renesas Electronics (TSE:6723) Stock Can Q3 Results Sustain Its AI Momentum
Renesas Electronics went into today’s session on the back foot, with the share price down about 17% over the past month and 90 days ahead of a closely watched Q3 2026 print. Traders saw another choppy semiconductor story, but the results told a different tale. Revenue landed at ¥435.9b and basic earnings per share hit ¥203.47, powered by stronger automotive and data center demand. In the short term, the stock is reacting to that recent slide. Over a longer horizon, the focus is on whether this profit surge is sustainable once one off gains and a richer investment budget are fully reflected.
Like the Renesas Electronics profit jump but wary that one off gains can fade and investment needs can climb just as fast? Screen for companies that pair resilient earnings with sturdier balance sheets using the list of solid balance sheet and fundamentals stocks (22 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): ¥435,917m vs. ¥335,364m (up about 30% year on year)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): ¥372,193m vs. ¥106,256m (very large year on year increase)
- Basic EPS (Q3 2026 vs. Q3 2025): ¥203.47 vs. ¥58.66 (very large year on year increase)
- Trailing 12-Month Revenue (to Q3 2026 vs. to Q3 2025): ¥1.586b vs. ¥1.262b (higher over the past year on a rolling basis)
Tired of scrolling through earnings tables and raw figures until your eyes glaze over? View Renesas Electronics through a clean visual dashboard that lays out the full picture, including how analysts are modelling the road ahead for the business in the company report for Renesas Electronics..
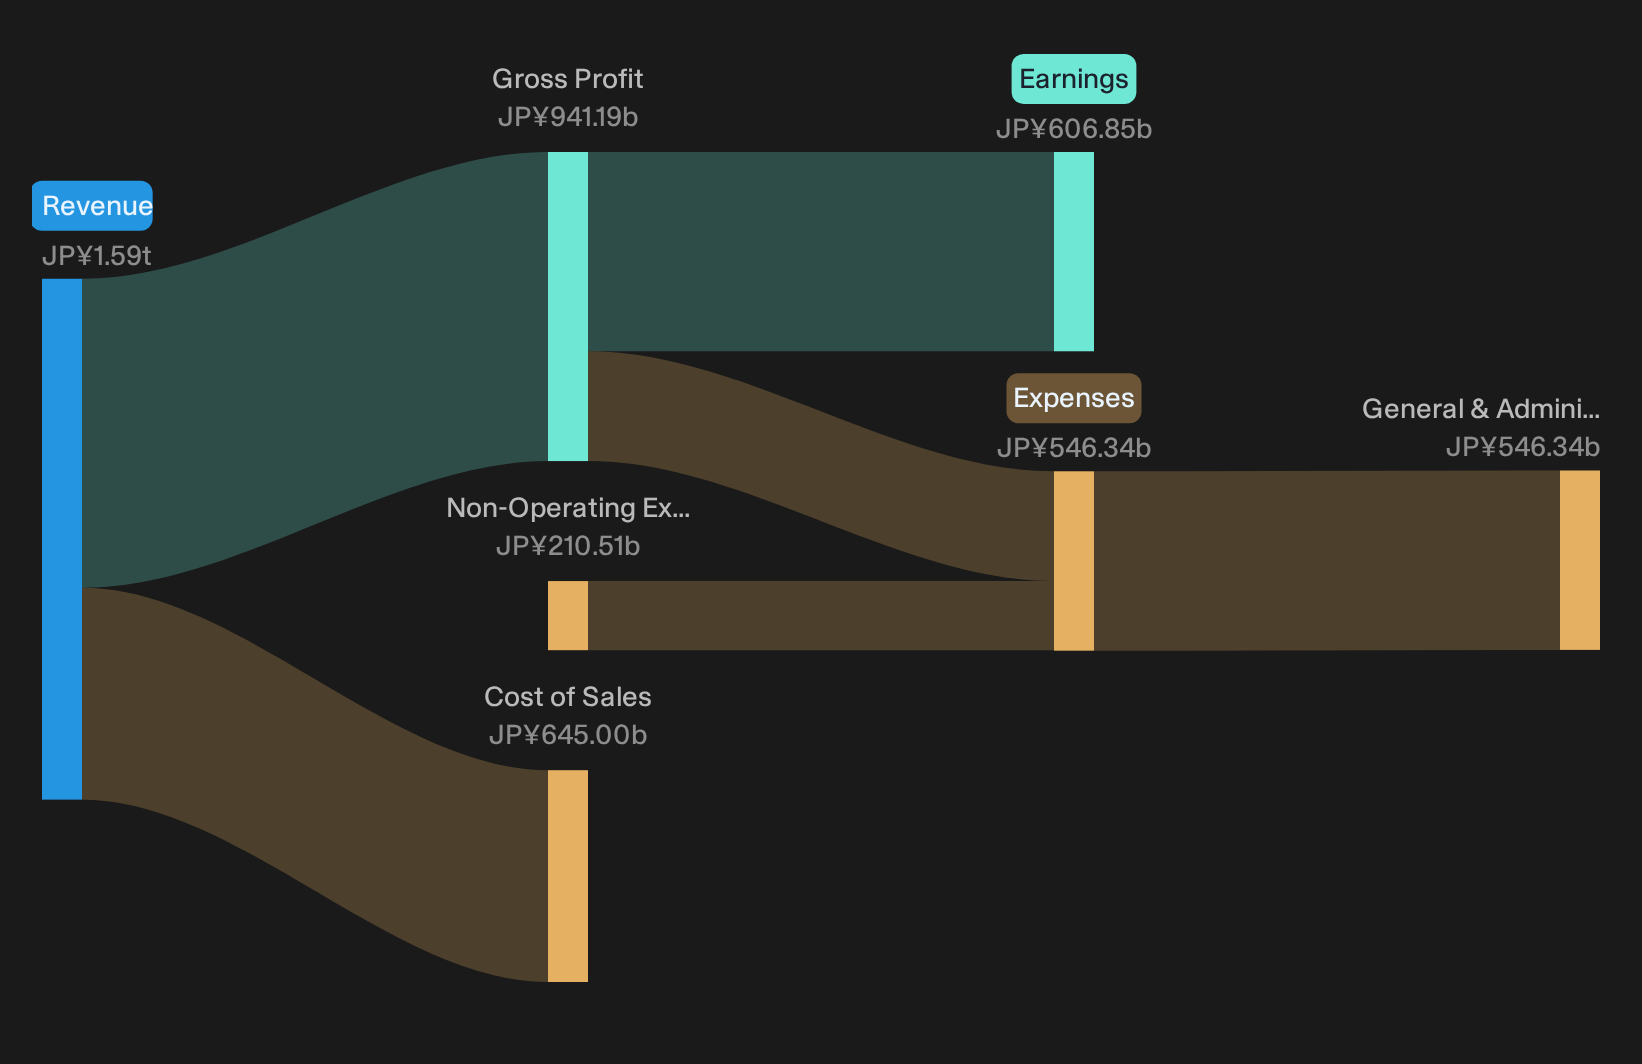
Renesas bullish AI thesis clears first execution test
The upbeat story hinges on AI infrastructure and software becoming real growth engines, not just slideware.
"Continued expansion of Renesas Electronics into AI infrastructure and data center compute, supported by management's expectation that AI and infrastructure related businesses could reach around 40% of company revenue in 3 to 4 years, points to a larger share of sales coming from higher value segments that can support earnings and operating margins."
Q3 puts a stake in the ground. Data center accounts for roughly 21% of Renesas Electronics sales and management guides mid teens percent quarter on quarter growth into Q4. Digital power and memory interface products sit among the key contributors and CapEx is being pulled forward to lift in house output by 2.0 to 2.5 times from FY2026 levels.
Renesas bear case on investment strain still in play
The worry is that the spend needed to win AI sockets eats into profitability faster than new revenue arrives.
"High SG&A and R&D investment intensity remains a live issue, since foundational spending on R&D, software, IT and workplace has already lifted these outlays to around 14% of revenue and pulled the 2025 operating margin to 24% compared with the 25% to 30% framework."
Q3 shows Renesas Electronics can post a 34.6% operating margin with elevated R&D, helped by FX, rich product mix and one offs. Guidance then flags Q4 margin contraction of 2.6 percentage points as mix tilts and OpEx rises. Management also signals a sustained J¥100b plus quarterly OpEx run rate, so the margin debate is very much alive.
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all.
Hunt For Mispriced Earnings Power
Renesas Electronics just showed how one quarter can shift expectations without resolving the long-term discussion. The real opportunity could sit in stocks the market has not yet correctly priced.
- Company 1 - 32% below our estimate - supplies high precision photomasks that chipmakers depend on as node complexity and packaging requirements steadily increase.
- Company 2 - 46% below our estimate - runs recruiting and workforce software that employers adopt once manual HR workflows start breaking under scale and compliance pressure.
- Company 3 - 33% below our estimate - provides specialty electronic materials that device makers specify when standard components cannot handle tighter optical and reliability requirements.
That is three of the list. See all 15 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com