


Kalmar (HLSE:KALMAR) Stock Faces Q3 Earnings Margin Durability Question
Kalmar Oyj went into its Q3 2026 report with the stock drifting, roughly flat over the past week and weaker over one and three months. The share price now has to digest a quarter where orders reached €458m and the comparable operating margin landed at 13.0%, while the trailing P/E sits at 13.8x against higher industry levels. In the short term, the market is reacting to a machinery manufacturer that just posted solid profitability. Over a longer horizon, this is a business that currently pairs a 9.2% net margin with earnings forecasts that indicate growth over several years.
Like the profitability profile of Kalmar Oyj but want similar machinery stocks that also clear a higher bar on valuation and balance sheet strength? Scan our curated group of list of solid balance sheet and fundamentals stocks (202 results)
Q3 2026 Earnings Summary
- Total Revenue (Q3 2026 vs. Q3 2025): €432.8m vs. €435.6m (slight decline of about 0.6%)
- Net Income, excl. extra items (Q3 2026 vs. Q3 2025): €38.6m vs. €44.7m (decline of about 13.6%)
- Basic EPS (Q3 2026 vs. Q3 2025): €0.60 vs. €0.70 (decline of about 14.3%)
- Comparable Operating Margin (Q3 2026 vs. prior quarter Q2 2026): 13.0% vs. 12.5% (sequential improvement, margin higher quarter on quarter)
Ask Charlie what’s really behind Kalmar’s North America order surge.
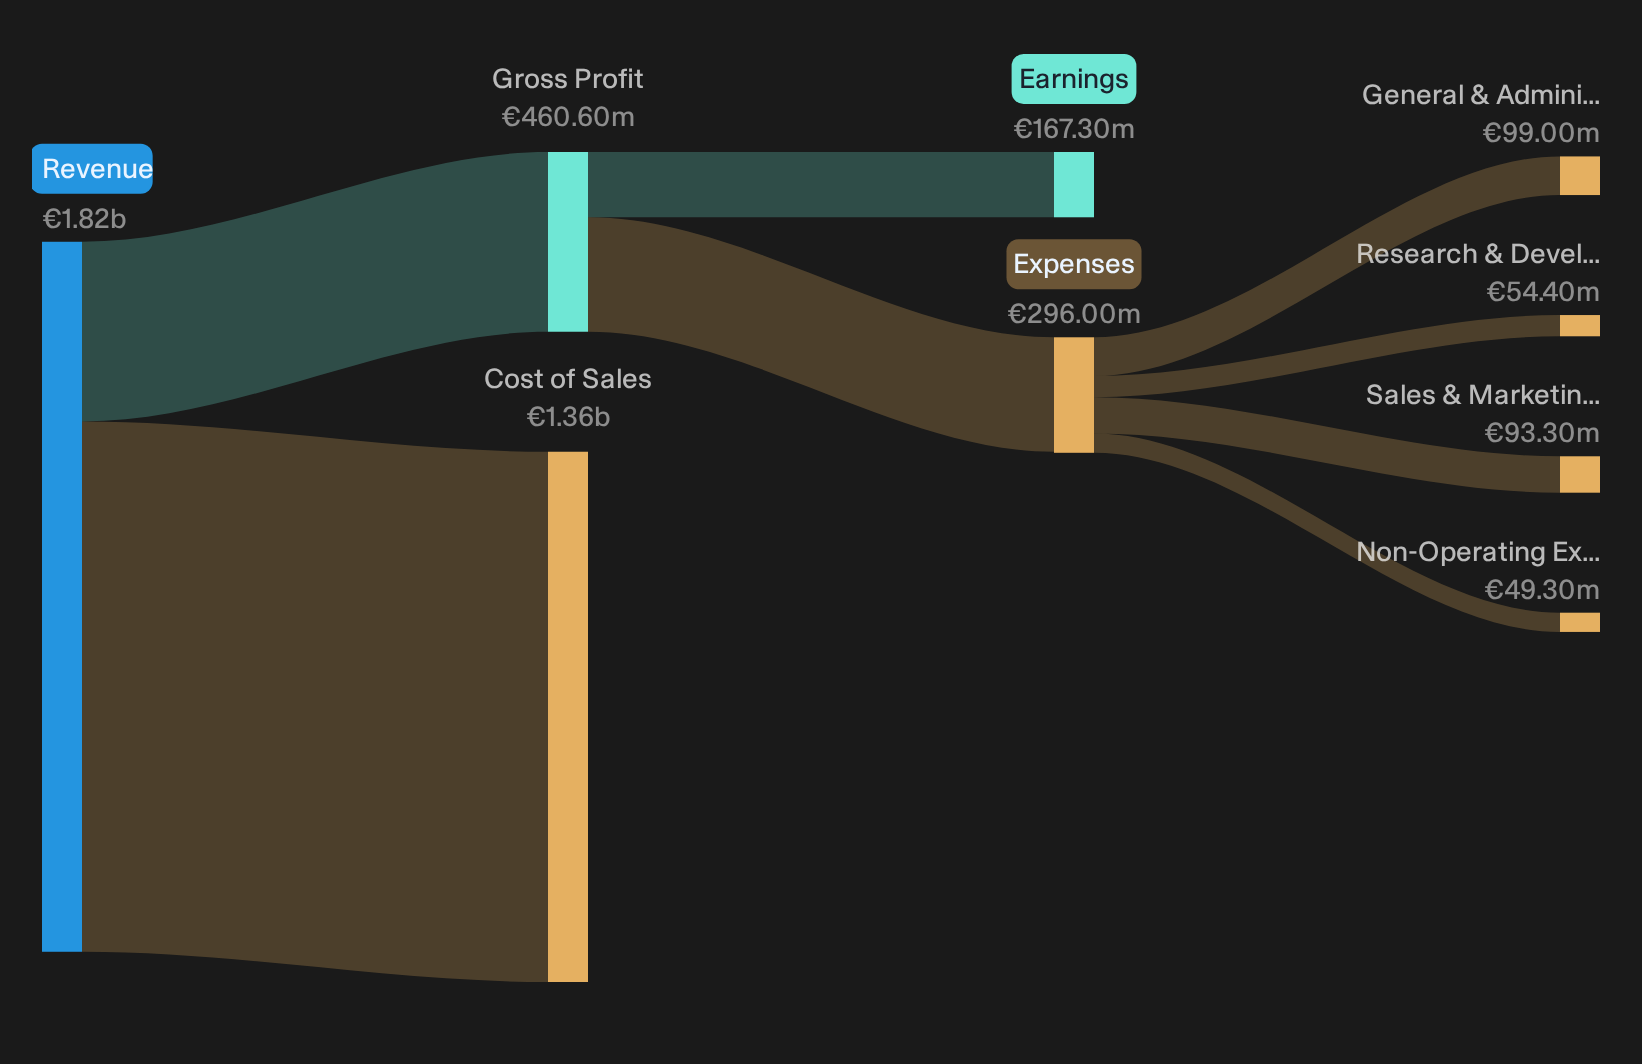
Evaluating Kalmar’s Margin Story Against Q3 Delivery
The bullish view depends on Kalmar Oyj converting cost programs and services into sturdier profitability. That ambition is clearly spelled out.
"The main thing that has to go right is that Kalmar turns its Driving Excellence savings, service expansion, automation initiatives and tariff refunds into sustained or better comparable operating margins despite ongoing freight and input cost headwinds."
Q3 moves this thesis forward. Comparable operating margin improved sequentially to 13.0% while guidance still points to a full year above 12.5%. Driving Excellence savings have already exceeded the €50m target, and Services, at 35% of sales with a 17.6% margin, provide tangible support for that profitability goal.
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for.
Kalmar tariffs and electrification worries face mixed evidence
Bearish investors argue that Kalmar’s push into eco and electric kit could collide with customer hesitation and stubborn cost inflation.
"Tariff exposure on Chinese origin components and batteries, along with shifting documentation requirements, raises the risk that price increases of around 5% to 15% fail to fully offset cost pressure, which would erode equipment margins and comparable operating profit."
The latest quarter complicates that fear. Equipment margin held at about 12.6% and group comparable margin improved to 13.0%, with tariff refunds helping. That means tariffs are still a real headwind, yet so far Kalmar is containing the damage rather than suffering the margin squeeze this narrative anticipated.
Hunt For Mispriced Earnings Power
Kalmar Oyj recently illustrated that even with solid margins, a share price can pause. The real opportunity is finding stocks that could be undervalued before the market adjusts their earnings power.
- Company 1 - 46% below our estimate - uses heavy spending on AI infrastructure to deliver more targeted ads, automated campaigns, and new business messaging tools.
- Company 2 - 43% below our estimate - ties its efficiency program and capital plan to higher margin composite components and aftermarket services.
- Company 3 - 27% below our estimate - sells photonic systems into semiconductor and biophotonics projects for chip and mobility customers expanding manufacturing capacity.
That is three of the list. See the full list of 201 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com