China Index Research Institute: The total amount of land acquired by the top 100 housing enterprises fell 17.5% year-on-year in January-October, private housing enterprises were more motivated to acquire land in October
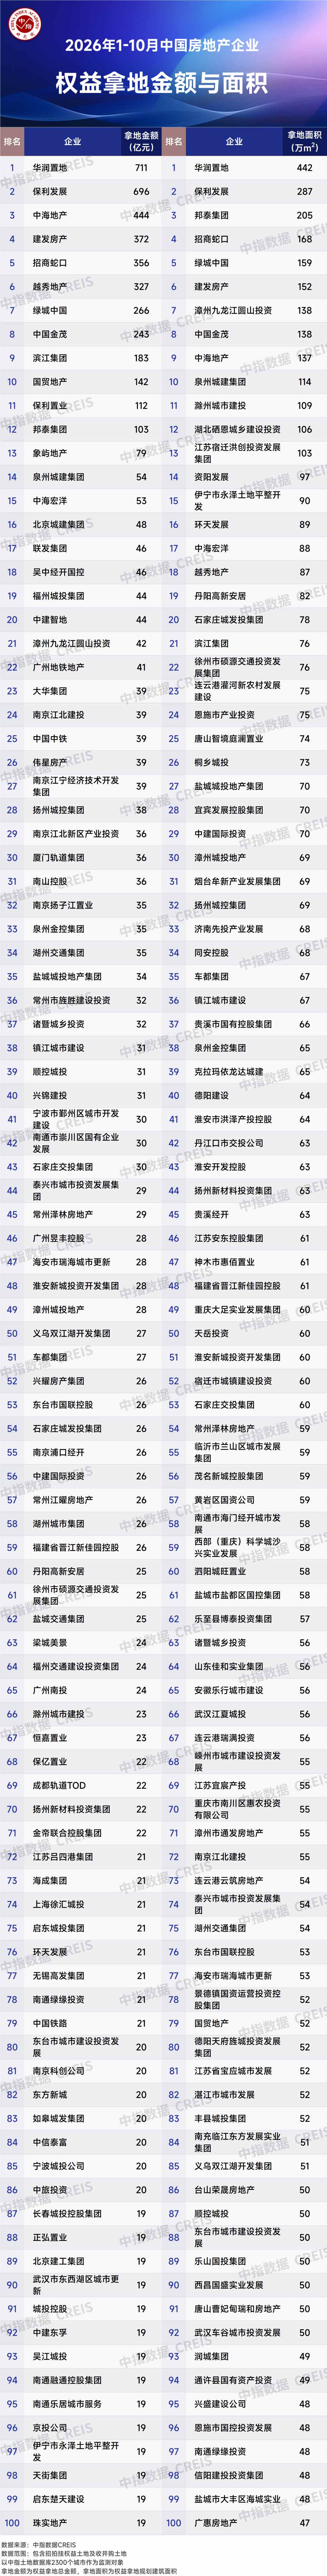
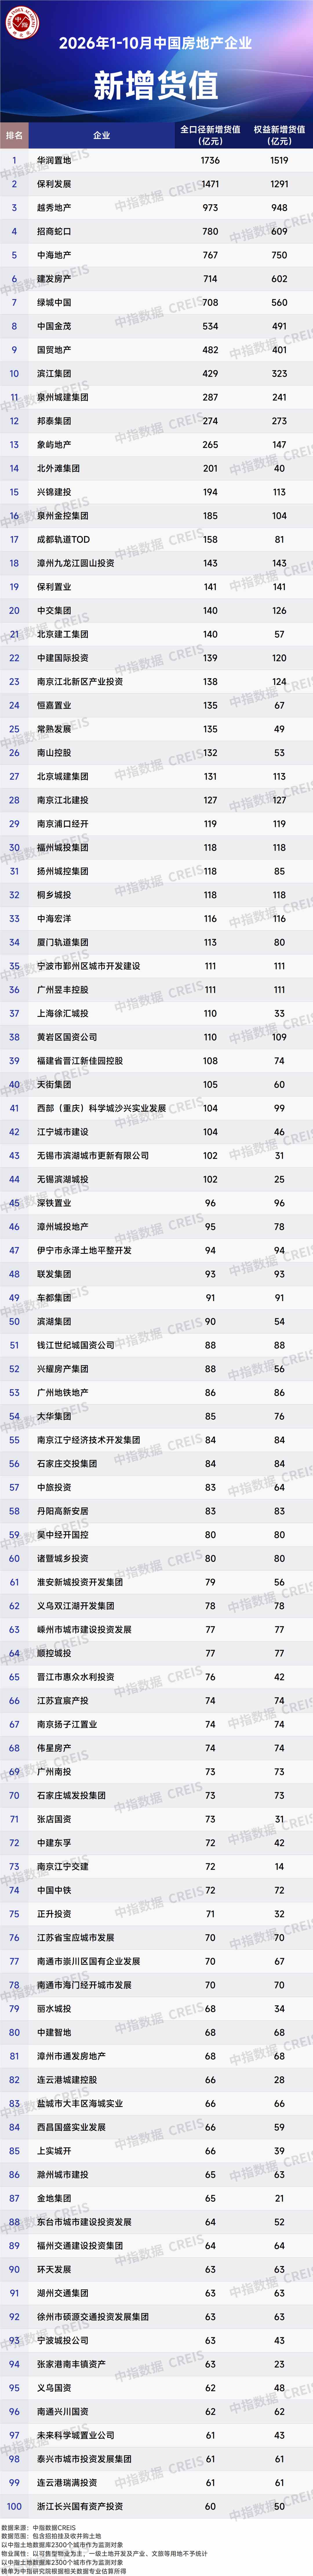
The Zhitong Finance App learned that the China Index Research Institute published an article stating that from January to October 2026, 100 housing enterprises acquired a total of 646.5 billion yuan of land, a year-on-year decrease of 17.5%, and the decline was 3 percentage points narrower than in January-September. In October, the decline in land acquisition by housing enterprises narrowed: First, although land in the three first-tier cities of Beijing, Shenzhen and Shanghai is currently empty, housing enterprises are still acquiring land in second-tier, third-tier and fourth-tier cities. For example, seven parcels of land in Chengdu sold 3,687 billion yuan, Suzhou and Nanjing sold multiple parcels of land several times, and 18 parcels of land in Changzhou sold 6.346 billion yuan. Second, many cities have introduced rules relating to the sale of existing homes. Among them, for land plots that have not been announced before the 828 New Deal, most cities stipulate that it is still possible to apply for pre-sale in accordance with the original pre-sale conditions until the end of 2027. Therefore, some housing enterprises actively use the window period to acquire land. From January to October 2026, the value of new goods added by 100 housing enterprises in full caliber decreased by 19.2% year-on-year.
Figure: Total land acquisition total of 100 housing enterprises from 2023 to 2026 and the year-on-year ratio

In October 2026, the average premium rate of 300 cities across the country fell to 1.4%, the lowest in the year. This month, none of the three first-tier cities of Beijing, Shenzhen, and Shanghai launched. Although third- and fourth-tier cities continue to promote land, most of them acquire land at reserve prices from local state-owned assets. Although the local auction market continues to operate at a low level, and reserve price transactions are mainstream, high-quality land plots in core areas are still favored by housing enterprises, and competition is more intense. For example, plot No. 24 in the Ersha Area of Zhongyuan District of Zhengzhou was contested by Sichuan Bangtai for 617 million yuan, with a premium rate of 20.76%. Land plot 2026-WG-Z45 in Suzhou went through 54 rounds of bidding, and C&D Real Estate competed for a total price of 646 million yuan, with a premium rate of 19.62%. The XS010304-07 plot, the core unit of Hangzhou Xiaoshan Century City, was won by Binjiang Group at a total price of 2,969 billion yuan after 97 rounds of bidding, with a premium rate of 48.53%.
Figure: Average premium rate for residential land in 300 cities across the country from 2023 to 2026

Land acquisition efforts by leading housing enterprises are slowing down, and private housing enterprises are more motivated to acquire land
Land acquisition efforts by leading housing enterprises are slowing down. From January to October, although the amount of land acquired by some companies increased year-on-year, they were all cumulative advantages. Looking at land acquisitions in a single month in October, China Resources Land (01109) and Binjiang Group (002244.SZ) are investing strongly. C&D Real Estate and China Jinmao (00817) have also increased their land acquisition efforts to a certain extent, and the remaining 6 housing companies' land acquisition efforts have all slowed down.
Table: Land acquisition status of key enterprises from January to October 2026

Although the number of private housing enterprises in the TOP30 is the same as in the same period last year, they are highly motivated to acquire land. Specifically, there is 1 private enterprise in the TOP10, Binjiang Group; 1 private enterprise in TOP11-20 is Bangtai Group; and 2 private enterprises in TOP21-30 are Dahua Group and Weixing Real Estate. In October alone, Binjiang Group won a plot of land in Xiaoshan District of Hangzhou at a total price of 2,969 billion yuan. The total amount of land acquired was quite high. Bangtai Group acquired 5 land cases, totaling 1.67 billion yuan. In October, due to a slowdown in land acquisition efforts by leading central and state-owned enterprises, private housing companies' efforts to acquire land became prominent.
Land acquisition by housing enterprises in key regions and cities

Land acquisition by housing enterprises has gone from being “fully rolled out” to an era of “accurate card slots,” and resources have been further concentrated on leading central state-owned enterprises. Specifically, Poly has developed a “heavy position” in the Yangtze River Delta, leading the country in terms of value. Poly Development topped the Yangtze River Delta list with 33.2 billion yuan, far exceeding the top amount in other regions, showing its high focus on the core cities of the Yangtze River Delta. China Resources Land's “dual regional dominance” has the strongest national layout. China Resources Land topped the list in both the Beijing-Tianjin-Hebei and Midwest regions at the same time. It is the only real estate company on the list that is at the top of both regions. Yuexiu Real Estate (00123) is deeply involved in the Greater Bay Area and has outstanding local advantages. As a local state-owned enterprise in Guangzhou, it has a strong ability to obtain resources in the Greater Bay Area. The Midwest is “large in volume and low in price”. Housing enterprises have acquired a total land area of 6.87 million square meters. It is the largest area of the four major regions, but the amount is only 44.3 billion, indicating that the Midwest is still an important position for housing enterprises to “exchange volume for scale.”

Judging from the top 10 real estate companies that have acquired land in key cities, leading state-owned enterprises pursue multi-city allocations; they are deeply involved in local housing enterprises and concentrate resources to protect their home ground; and central state-owned enterprises that have entered selective cities are heavy on a small number of cities. Leading central enterprises, such as Poly Development (600048.SH) and China Resources Land, are simultaneously established in multiple core cities, reducing the financial pressure on individual parcels through cooperative development, and actively participating in the competition for high-total land plots. Local housing enterprises, represented by the Binjiang Group, concentrate on land acquisition in the most reliable cities, and continue to further refine with local brands, product reputation, and sales advantages. Central state-owned enterprises, such as C&D Real Estate, appear more frequently in cities such as Shanghai, Hangzhou, Beijing, and Guangzhou. These housing enterprises do not necessarily seek to be number one in the country, but instead concentrate on entering markets with strong fundamentals and more secure diversification.

Judging from the top 10 total residential land transaction prices in the country, it is mainly concentrated in second-tier cities, and land acquisition companies are mainly local state-owned. Since only one first-tier city in Guangzhou launched land this month, the land on the list is mainly in second-tier cities, including 2 in Xiamen, 2 in Nanjing, and 1 each in Hangzhou and Jinan. Among them, China Resources Land bid at a reserve price of 4.9 billion yuan on the southwest side of the intersection of Tiyu Road and Qixing Road in the western area of 03-01, Siming District, Xiamen. Judging from the nature of land acquisition enterprises, six have become locally state-owned.