


Is Wall Street Bullish or Bearish on AppLovin’s Stock?
Valued at $87 billion by market cap, AppLovin Corporation (APP) is an AI-powered advertising technology company. Headquartered in Palo Alto, California, AppLovin provides a software platform that helps developers acquire users, optimize app performance, and generate revenue through advertising.
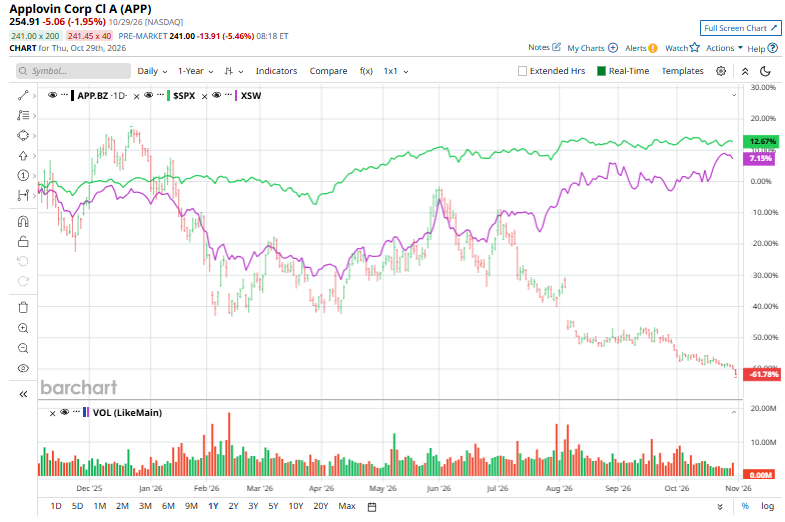
Shares of AppLovin have considerably underperformed the broader market over the past year. APP has tanked 59.6% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 12%. Over the past six months, APP stock is down 62.2%, trailing the SPX’s 8.2% rise.
Zooming in further, APP has also exceeded the SPDR S&P Software & Services ETF (XSW). The exchange-traded fund has gained 7.5% over the past year. Moreover, APP’s double-digit gains over the past six months outshine the ETF’s 13.6% rise over the same time frame.
AppLovin is facing growing legal scrutiny over its AI advertising business, its disclosures to investors, and allegations about the ads and data practices associated with its platform. The most direct threat to APP shareholders is a securities-fraud class-action lawsuit filed in the U.S. District Court for the Northern District of California. The lawsuit alleges that AppLovin and certain executives misled investors about the strength of its AI advertising models and the readiness of a new generative AI video-creation tool.
Moreover, on Oct. 5, San Diego County sued AppLovin in California state court, alleging that its advertising technology displayed sexually explicit, violent, and age-inappropriate ads, including promotions for alcohol, vaping, and cannabis, in games used by children.
Similarly, AppLovin is also involved in a dispute with its rival Unity over alleged unauthorized collection of confidential advertising and auction data, with Unity disputing the claims. Together, these cases threaten to increase legal costs, intensify scrutiny of AppLovin’s business practices, and weigh on investor confidence.
For FY2026, which ends in December, analysts expect APP’s EPS to grow 56.1% to $15.67 on a diluted basis. The company’s earnings surprise history is impressive. It beat the consensus estimate in each of the last four quarters.
Among the 30 analysts covering APP stock, the consensus is a “Strong Buy.” That’s based on 21 “Strong Buy” ratings, two “Moderate Buys,” and seven “Holds.”
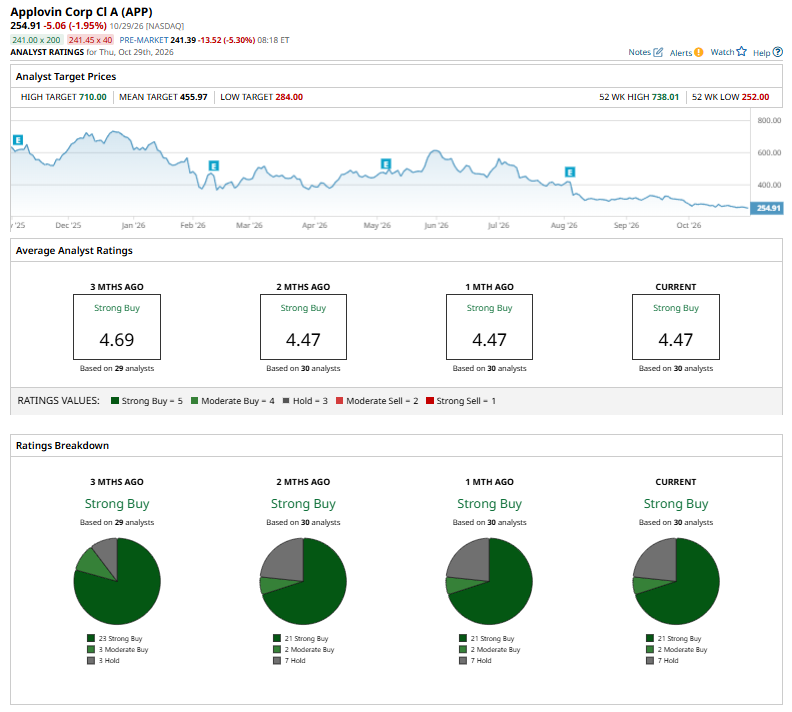
This configuration is more bearish than three months ago, with 23 analysts suggesting a “Strong Buy.”
On Oct. 19, Citi analyst Jason Bazinet maintained a “Buy” rating on AppLovin but lowered his price target to $500 from $600 ahead of the company’s Nov. 4 earnings report. The reduced target reflects a more cautious outlook amid higher interest rates, execution risks following the previous quarter’s revenue miss, and ongoing litigation involving Unity.
The mean price target of $455.97 represents a 78.9% premium to APP’s current price levels. The Street-high price target of $710 suggests an ambitious upside potential of 178.5%.
On the date of publication, Kritika Sarmah did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.