


Canadian Stock Market Today: TSX Futures Dip On European Energy Inflation And GDP Watch
The Morning Bull - Canadian Market Morning Update Friday, 30 Oct 2026
Canadian equities are set for a softer open, with sentiment pinned to fresh evidence of sticky, energy driven inflation in Europe. Investors are treating the French and German data as a clean read on global pricing pressure.
France’s October inflation came in at 3.4% year on year, above the previous 3.1%. Germany’s import prices rose 10.4% year on year in September, reflecting higher energy and commodity costs that feed directly into euro area inflation expectations.
When key European prices run hot, bond markets tend to price a higher risk of tighter policy or a longer plateau in rates. That keeps global borrowing costs elevated, which can pressure valuation multiples and squeeze cash flows for more debt heavy Canadian sectors.
The open question now is simple: Do upcoming euro area GDP and inflation readings justify a tougher European Central Bank stance, or does weaker French growth at 0.1% quarter on quarter argue for patience and give Canadian markets some breathing room?
Stocks to Watch Before the Opening Bell
Whitecap Resources (WCP)
Whitecap Resources reported a third quarter profit that was about 60% higher than a year earlier, raised its dividend, and lifted its production forecast for the third time this year. The producer is adding roughly $100 million to this year’s spending as drilling runs ahead of schedule, while letting extra cash accumulate for potential buybacks, higher payouts, growth projects, or acquisitions.
Air Canada (AC)
Air Canada posted record third quarter operating revenue of $6.984b, supported by broad strength across its network and revenue streams. The airline also launched a normal course issuer bid for up to 25.2 million shares, about 10% of its public float, and adjusted full year guidance to reflect higher fuel costs while aiming to offset roughly 70% through pricing and cost measures.
Methanex (MX)
Methanex reported third quarter net income of $265 million and adjusted EBITDA of $543 million, supported by strong operations and methanol pricing. The producer plans to sell most of its New Zealand gas entitlements and indefinitely idle local plants, redeem $300 million of 2027 bonds, and start a normal course issuer bid on November 4 to retire up to 5% of its shares.
Top Movers
- Restaurant Brands International Limited Partnership (TSX:QSP.UN) jumped 4.29% after Q3 earnings showed higher revenue and sharply stronger net income year on year.
- FirstService (TSX:FSV) gained 3.99% as fresh research and new management mandates highlighted its role in amenity rich communities.
- GFL Environmental (TSX:GFL) advanced 3.33% on raised 2026 guidance, strong Q3 results, and ongoing interest in potential take private offers.

Top Losers
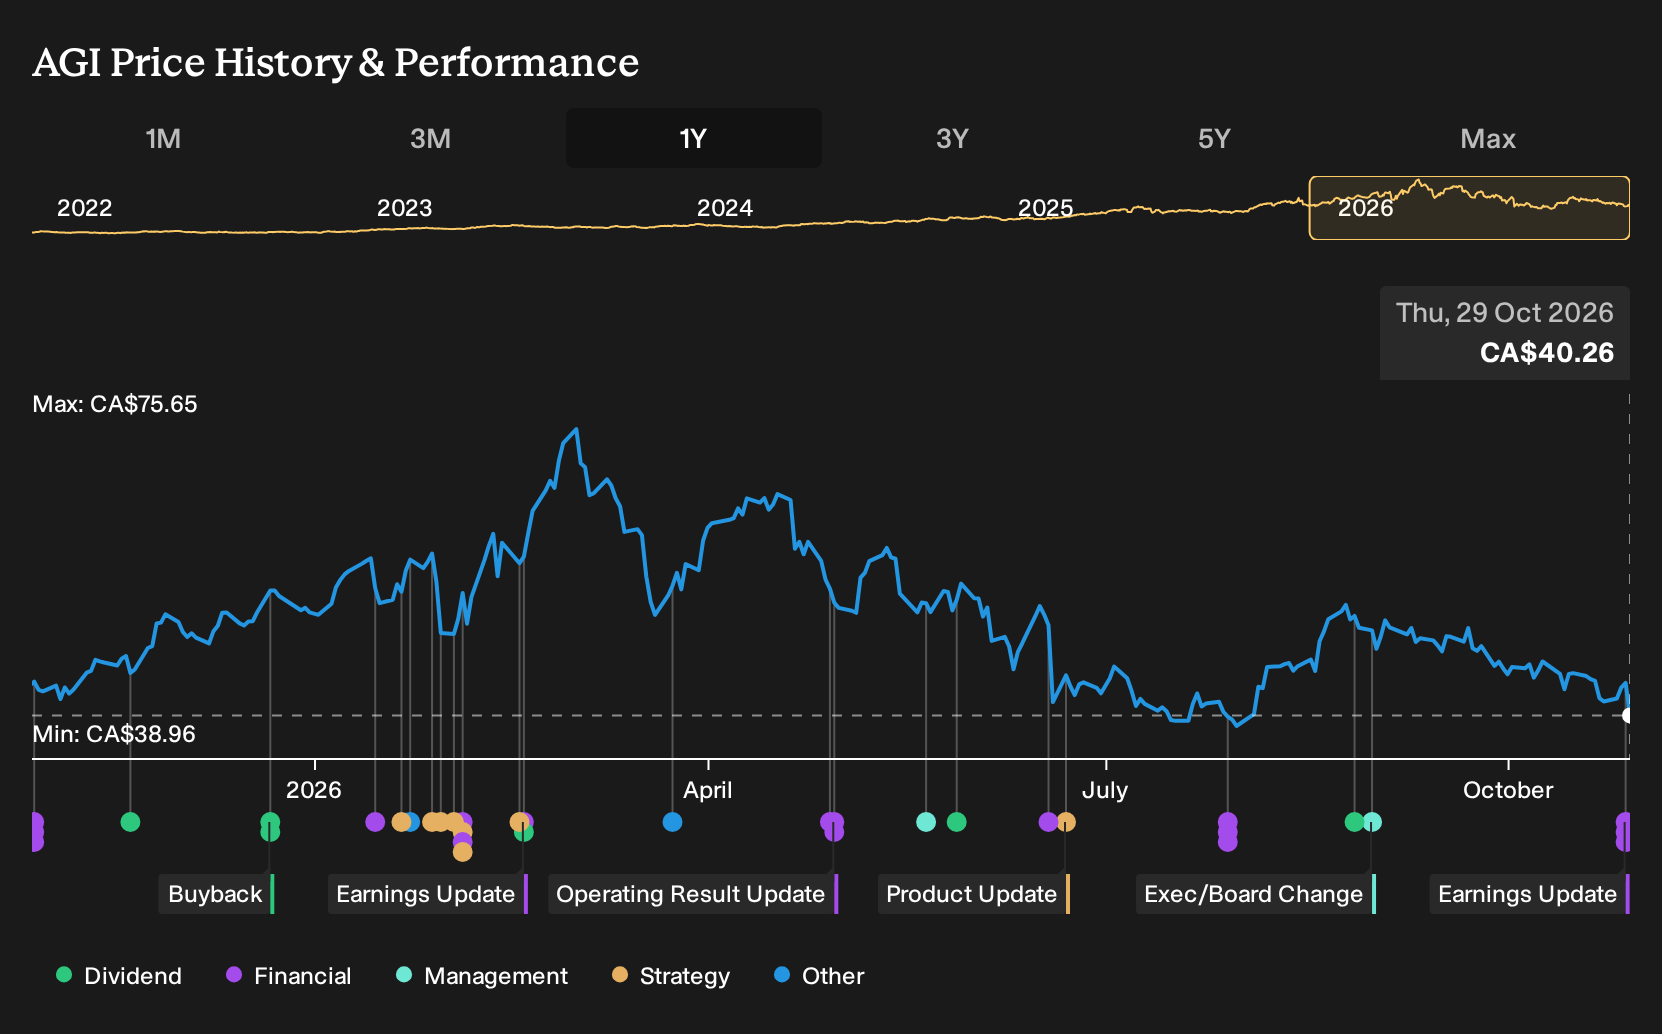
- Alamos Gold (TSX:AGI) fell 9.10% after delaying the Island Gold shaft expansion and cutting 2026 guidance with higher costs.
- Kinross Gold (TSX:K) declined 6.28% following weaker production, lower free cash flow, and reports of two contractor fatalities.
- Eldorado Gold (TSX:ELD) dropped 6.22% after cutting its 2026 output outlook and flagging extra Skouries costs and delays.
On The Radar
Canadian trading over the next few sessions leans on a tight cluster of domestic data and heavyweight TSX earnings, with US labour and cost figures setting the backdrop for rates and the Canadian dollar.
- Canada GDP MoM (Aug and Sep prelim) Fri 30 Oct. A move around the 0.2% consensus for August and the 0.1% preliminary view for September will influence how firmly markets treat the current Bank of Canada rate path and rate sensitive TSX sectors.
- Magna International Fri 30 Oct. Q3 results before the bell will put auto production volumes and margin resilience under the microscope, which is relevant for anyone holding Canadian manufacturing exposure tied to North American vehicle and parts demand.
- Imperial Oil Fri 30 Oct. Quarterly numbers land during the session and will focus attention on upstream cash generation and downstream refining profitability, both key reference points for Canadian integrated energy stocks and broader index earnings power.
- Canadian labour market data Fri 6 Nov. The October jobless rate, employment change and participation rate will indicate whether September’s 68,300 job decline was a one off, with any upside surprise versus forecasts likely to support the loonie and weigh on expectations for rate cuts.
- US Non Farm Payrolls and wages Fri 6 Nov. An October payroll gain compared with the prior 29,000 print and wage growth around the 0.2% MoM and 3% YoY forecasts would be consistent with current Fed expectations, shaping US dollar moves that often spill into Canadian equities and FX.
Sector & Industry Watch
Energy: Cash rich producers stay busy
Energy and Oil and Gas keep building on recent gains over the past week and month, backed by strong 1 year returns. Companies such as Whitecap Resources, TerraVest and Keyera are using this backdrop to fund higher dividends, extra drilling, and fee based projects while still keeping an eye on debt.
The crucial macro check for this group is today’s Canada GDP release, since a stronger read would underline how much national output still leans on resource activity.
Banks: Rate hike supports lending income
Banks continue to outpace the broader CA Market over the last year, with a clear 7 day lift as investors absorb the Bank of Canada’s move to a 2.5% policy rate and a 4.70% prime rate. Higher reference rates tend to fatten interest income for lenders like RBC, TD, BMO, CIBC and National Bank, even as households and businesses face more expensive mortgages and credit lines.
For anyone holding bank stocks, August GDP and the preliminary September figure this afternoon are the data points that matter because surprises on growth feed directly into views on loan demand and future credit losses.
Real Estate: Higher borrowing costs still hurt
Real Estate has slipped over the past week despite a small 30 day gain, and both year to date and 1 year returns trail the CA Market. A 4.70% prime rate keeps debt expensive for REITs and property operators such as RioCan, Mainstreet Equity and Colliers that rely on refinancing to fund new projects or keep existing buildings running.
If you own Real Estate exposure, today’s Canada GDP report is the key reference point because softer activity would keep questions alive around occupancy, rent growth and interest costs.
Materials and Metals and Mining: Weak month, busy project pipeline
Materials is down sharply over the past month and Metals and Mining has fallen even more, while 7 day returns are roughly flat. At the same time, miners and processors including Methanex, Teck Resources, Centerra Gold and a long list of juniors are pressing ahead with drilling, feasibility work and asset deals that often depend on fresh financing.
For investors with exposure here, Canada’s GDP print this afternoon is the single macro signal to watch because it can influence risk appetite for long dated resource projects.
Utilities: Income trade backed by project news
Utilities has edged higher over the last week, with firm gains over the past month and year to date that outpace the CA Market. Updates from AltaGas, ATCO and Northland Power keep attention on how regulated or contract based cash flow lines up against dividends and sizeable capital programs.
The swing factor for Utilities is less about one data release and more about company guidance, such as AltaGas lifting its full year earnings outlook, because that commentary shapes confidence in future payouts and spending plans.
Build Your Perfect Portfolio
With Canadian banks benefiting from a 2.5% policy rate and 4.70% prime rate, income focused investors can start with this list of 3 dividend fortresses
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com