


Cipher Digital (CIFR) Stock Looks Overvalued On Fresh AI Data Center News
Cipher Digital has had a rough year on the screen, yet the stock is still coming off a very strong three year run. This puts fresh attention on whether today's US$8.10 share price lines up with the revenue the business is generating. Recent news around a new AI data center project in Spain has added another layer to the story and raises a clear question about what investors are now paying for each dollar of Cipher Digital's sales.
- Over the past three years, Cipher Digital has delivered a gain of 97.6% which makes the current tag per share far more sensitive to how its sales base is valued.
- News that IREN secured approvals and power for a planned 300MW AI data center campus in Spain, with Cipher Digital rising alongside it, can feed expectations for future workload demand that may support higher revenue assumptions and influence how much investors are willing to pay per unit of sales today.
- Your read on Cipher Digital is one view; the desks covering it have another. See what analysts think Cipher Digital's shares could be worth.
The issue now is whether the recent share price around US$8.10 is adequately supported by Cipher Digital's current sales and how investors are choosing to value that revenue stream.
If you are weighing Cipher Digital against other ways to play this theme, it can help to see how it stacks up beside 54 AI infrastructure stocks.
Is Cipher Digital Getting Expensive on Sales?
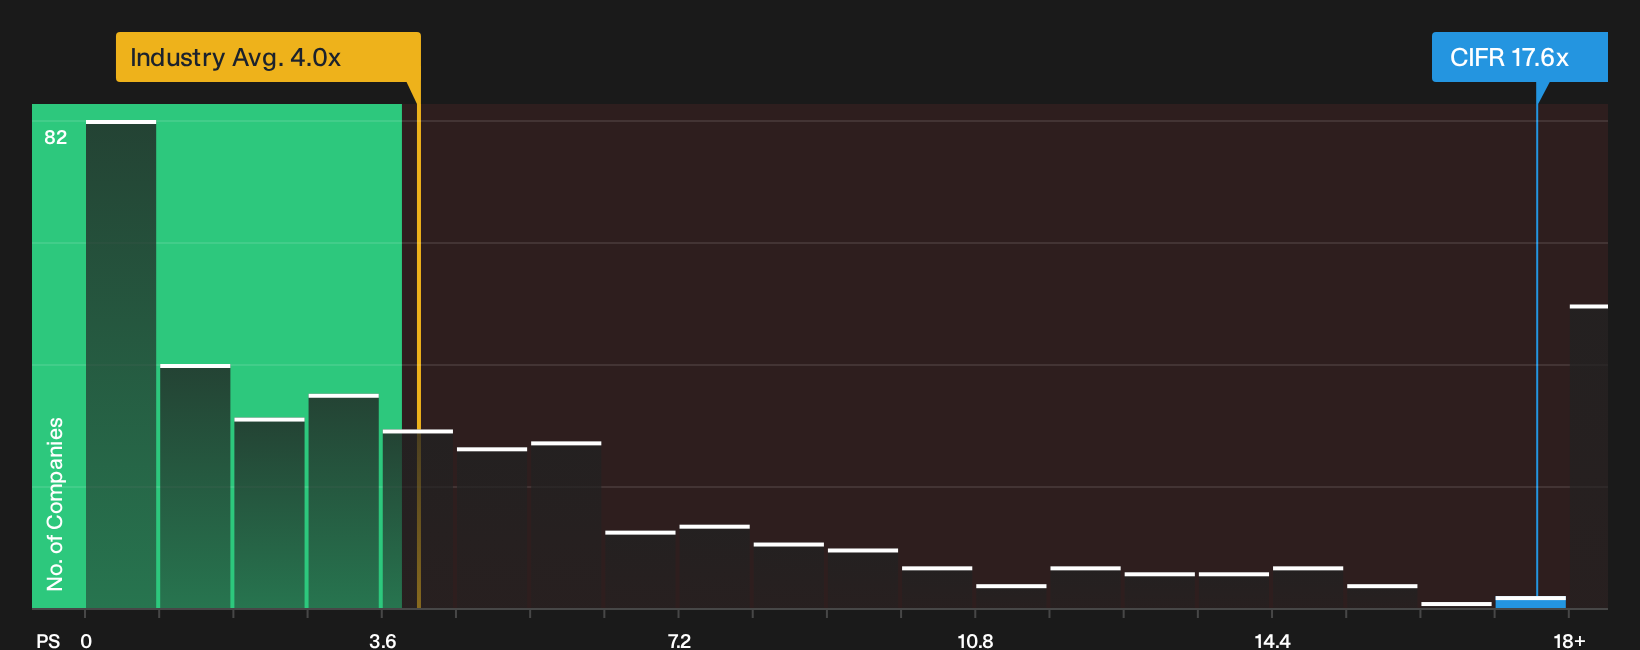
P/S suits Cipher Digital because revenue is currently a cleaner reference point than earnings, which are still shaped by heavy investment and losses. On this yardstick, the stock trades at about 17.6x sales, compared with roughly 4.0x for the wider Software industry and about 6.8x for closer peers. That is a steep step up in what buyers are paying for each dollar of current revenue.
Despite the recent AI data center news lifting sentiment around the theme, the present P/S multiple sits well above what a more tailored fair ratio model would suggest for Cipher Digital given its risk profile and cash flow track record. The model is heavily penalising ongoing losses and the quality of the revenue base, so the gap is better read as a warning that the shares screen very expensive on this framework rather than a precise estimate of where they should trade. Explore the numbers behind Cipher Digital's P/S valuation.
The Cipher Digital Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Cipher Digital's valuation question leaves off by spelling out which revenue, margin and earnings paths would need to hold for the stock to look meaningfully under or overvalued relative to today's price, all housed on the Community page. Each narrative sets out a fair value view as a thesis you can track over time, so you can see how the reasoning holds up as Cipher Digital's story develops.
One of the top community narratives on Cipher Digital: 72% undervalued
"The current valuation implies the market is still discounting Cipher Digital’s contracted revenue base and billions of dollars of project level funding…"
Discover why this Narrative puts Cipher Digital at 72% undervalued.
Cipher Digital’s story is not complete without who is steering it
Valuation is only one side of Cipher Digital, because the judgment, incentives and pay structures guiding leadership can heavily influence how that story plays out for shareholders. See who runs Cipher Digital and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com