


First Tractor (SEHK:38) Stock Faces Q3 Earnings Margin Pressure
First Tractor just posted its Q3 2026 scorecard, and the share price tells one story while the income statement hints at another. The stock closed at HK$7.55 on 30 October, down over the past month, even as quarterly basic earnings per share came in at ¥0.24 and net income reached ¥270.3 million. For a machinery manufacturer that lives and dies on profitability through the cycle, the key tension now is a gentle squeeze in net margin that sits below last year, which the market appears to be treating as a verdict rather than a warning shot.
Like the earnings power at First Tractor but uneasy about a thinner net margin and market skepticism? Use our benchmark and scan the list of solid balance sheet and fundamentals stocks (203 results) for peers that pair earnings with sturdier financial footing.
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): ¥3,163.5 million vs. ¥2,774.9 million (up about 14.0%)
- Net Income (Q3 2026 vs. Q3 2025): ¥270.3 million vs. ¥225.2 million (up about 20.1%)
- Basic EPS (Q3 2026 vs. Q3 2025): ¥0.2406 per share vs. ¥0.2004 per share (up about 20.1%)
- Net Profit Margin (Trailing 12 Months vs. Prior Year): 7.2% vs. 7.5% (slight compression)
First Tractor’s earnings are growing faster than the market. Ask Charlie why First Tractor trades so far below earnings.
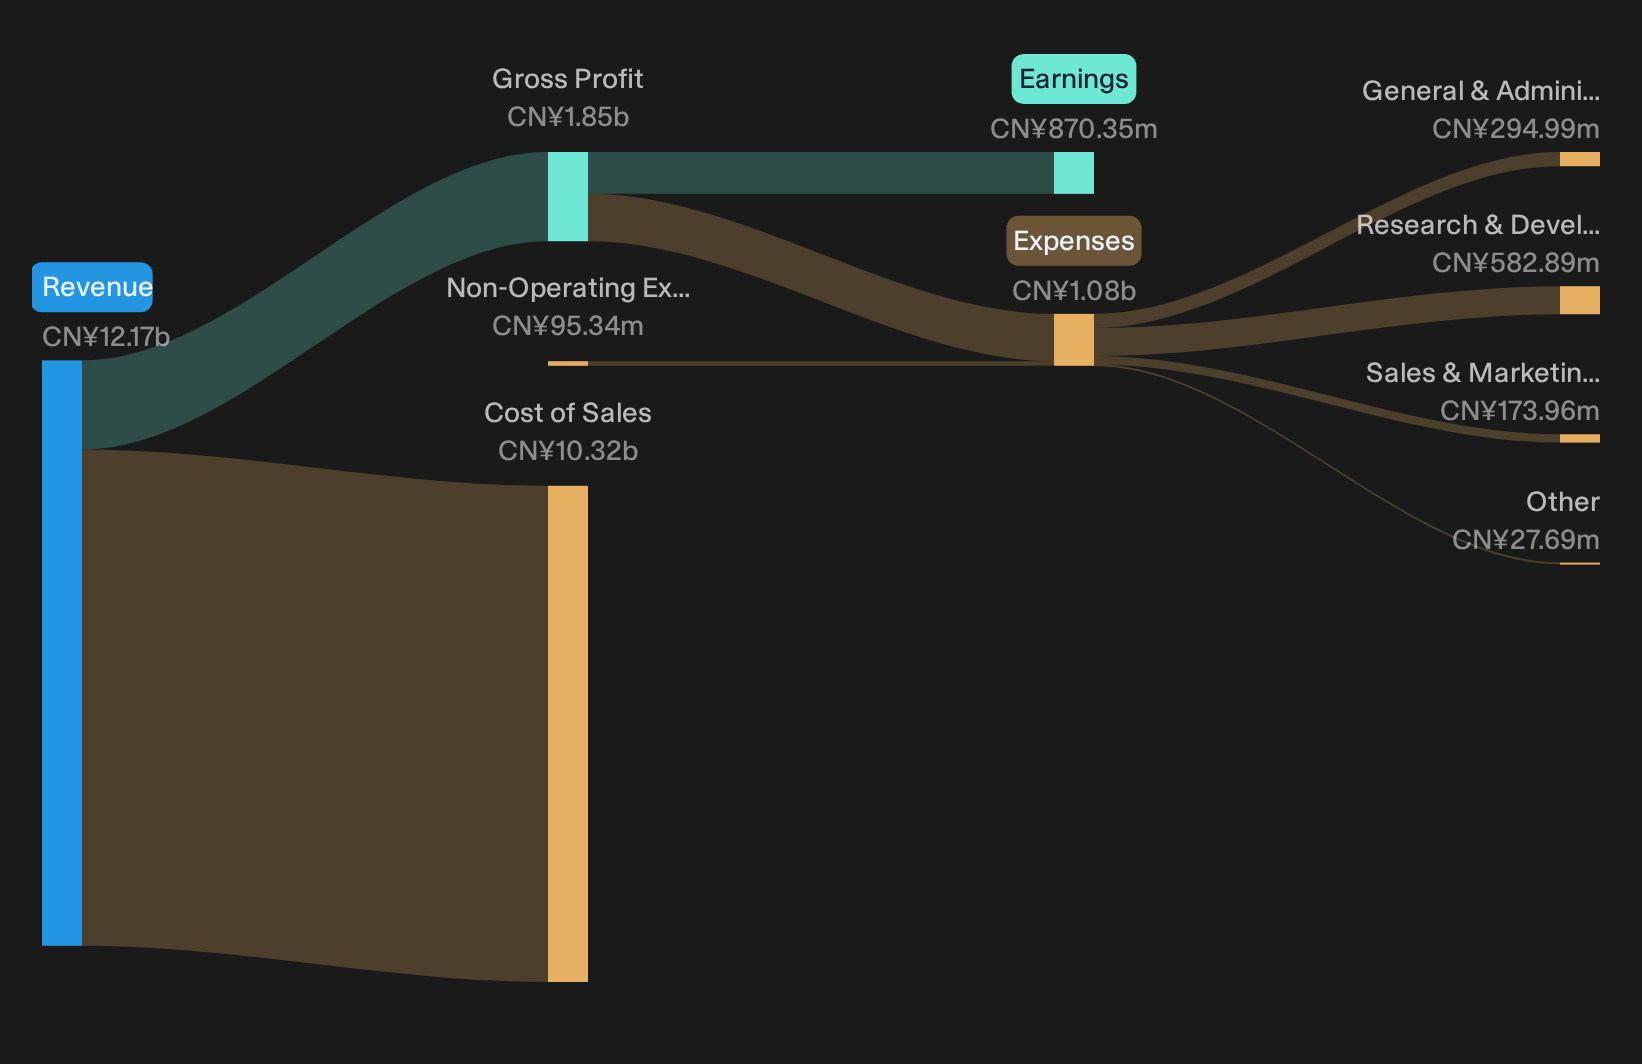
First Tractor’s Q3 supports a cautious bull case
For anyone leaning positive on First Tractor, the latest quarter gives some backing. Revenue is higher than a year ago and net profit and basic EPS both move in the same upward direction. That combination suggests the product set is still finding buyers and the income statement can carry higher volume. Net margin on a trailing view is a touch lower at 7.2% compared with 7.5%, so profitability is not racing ahead. Even so, higher earnings alongside only mild margin pressure broadly fit a moderate long term modernization story.
Margin squeeze keeps the First Tractor bear case alive
Bears will point straight to that softer net margin. A trailing 7.2% versus 7.5% lines up cleanly with the idea that this is a tough, cyclical industrial where pricing power is limited. The share price picture adds to the caution, with the stock down about 13% over 30 days and about 15% over 90 days. Recent gains over 7 days look more like a short bounce than a trend change. For a cautious reader, the latest figures show volume holding up while profitability and sentiment stay under pressure.
Do you think First Tractor’s cautious bull case holds up against market gloom, or are analysts still trimming expectations? Check the consensus price target analysis for First Tractor.
Hunt Quiet Dislocations In Plain Sight
First Tractor recently showed how steady reported performance and a drifting share price can sit together. The real opportunity is studying stocks that could be undervalued before markets reassess them.
- Company 1 - 33% below our estimate - expands its residential launch pipeline and industrial clusters while linking presales directly to cash collection.
- Company 2 - 26% below our estimate - embeds chips and software at key points for data processing, connectivity and security across digital infrastructure.
- Company 3 - 34% below our estimate - tightens its cost-to-serve model while scaling membership and recommerce through its own integrated reverse supply chain.
That is three of the list. See the full list of 197 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com