


Axcelis Technologies (ACLS) Faces An Earnings Test As Its Undervalued Narrative Holds
Axcelis Technologies (ACLS) has been in focus after its shares slipped 1.5% in the latest session, as investors prepare for the November 5 earnings release and weigh fresh executive appointments.
That short term pullback sits against a choppy backdrop, with a 7 day share price return of 6.95% after a 30 day decline of 12.95% and a 90 day fall of 14.08%. Axcelis Technologies still shows a 30.07% year to date share price gain and a 36.88% 1 year total shareholder return, which suggests that investors are weighing recent Korea expansion plans and the Veeco linked leadership reshuffle as both an opportunity and a source of execution risk.
Scan Axcelis Technologies alongside a curated group of peers under pressure or poised to break out with the 30 high quality undervalued stocks.
Bulls point to Axcelis Technologies’ Korea build out, Veeco merger plans and recent earnings record. Bears focus on the share pullback and execution risk. The current valuation math shows which side has more support.
Most Popular Narrative: 25% Undervalued
Against a last close of $112.02, the prevailing narrative anchors Axcelis Technologies to a fair value of $150, implying meaningful upside if those assumptions hold.
Emerging requirements for higher voltage and advanced power management in data centers, including 800V architectures, together with 5G and renewable applications are now reflected in stronger DRAM and silicon carbide related bookings and in management’s raised 2026 and 2027 revenue outlook. This ties these usage cases more directly to Axcelis Technologies order growth and potential future revenue and EPS.
See why 78 investors see Axcelis Technologies as 25% undervalued.
Result: Fair Value of $150 (UNDERVALUED)
Still, the story can change quickly if Axcelis Technologies faces weaker orders from China, or if the planned Korea facility ends up underused and pressuring margins.
Find out about the key risks to this Axcelis Technologies narrative.
Another View: Cash Flows Paint A Harsher Picture
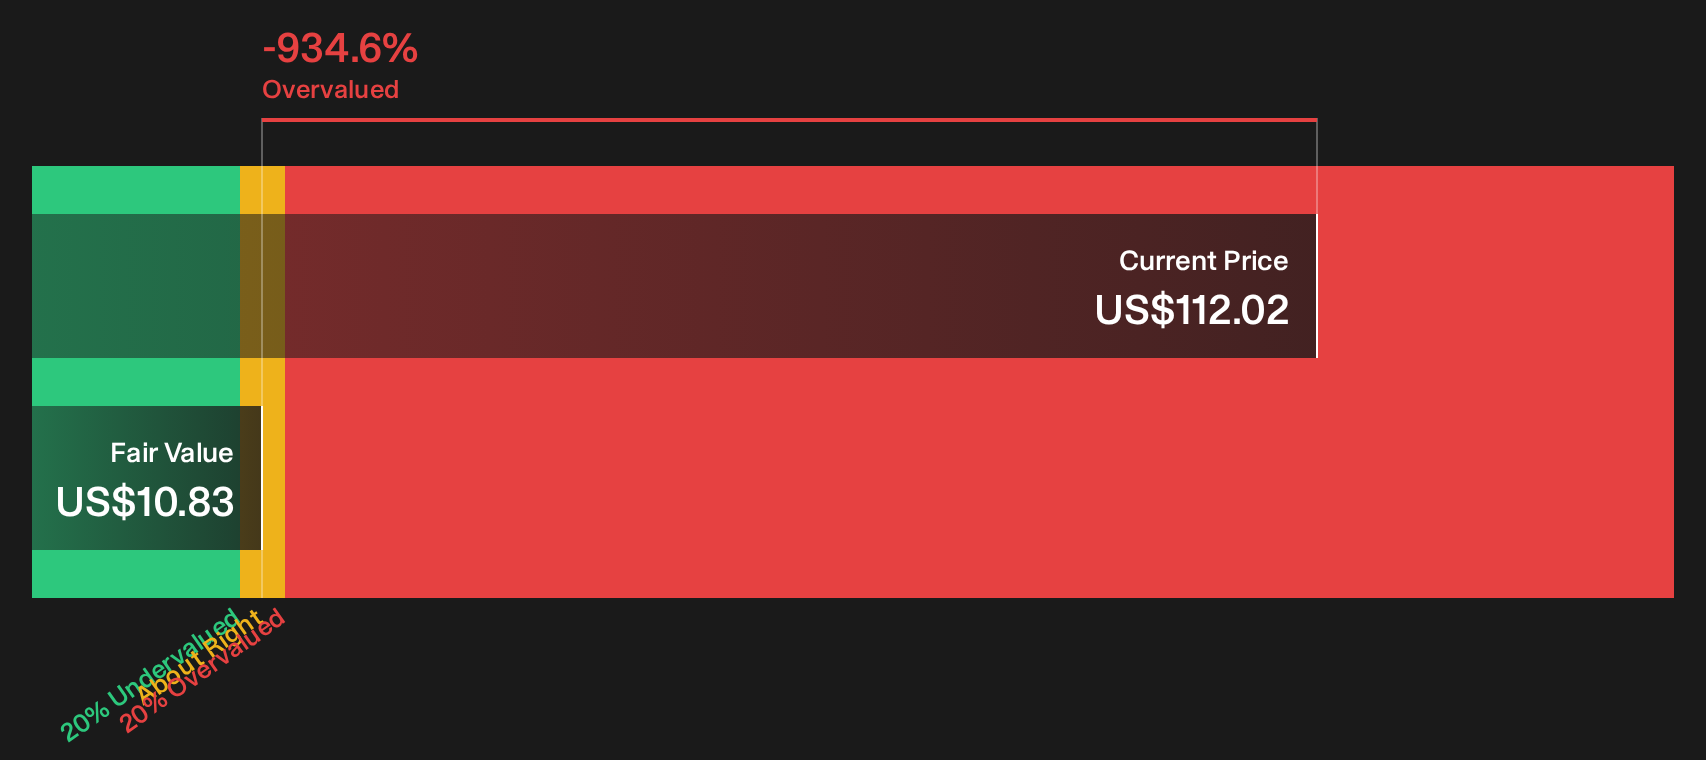
While the Axcelis Technologies narrative leans on a $150 fair value from analyst assumptions, the SWS DCF model tells a very different story. On that cash flow view, the estimated value comes out at $10.83 per share, which points to Axcelis trading well above that number today. Which framework do you give more weight to when the gap is this wide?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Axcelis Technologies for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals across Axcelis Technologies can be confusing, so consider reviewing the full picture yourself promptly by weighing both the risks and the potential upside set out in the 3 key rewards and 1 important warning sign.
Looking for more Axcelis Technologies sized opportunities?
If you are only tracking Axcelis Technologies, you might miss other compelling setups. Cast the net wider now so you are not late to the next move.
- Target durable balance sheets and steady fundamentals through a focused list of solid balance sheet and fundamentals (23 results) to help reduce blow up risk in your portfolio.
- Hunt for mispriced businesses trading below their implied worth by running a quick pass using the 30 high quality undervalued stocks before the crowd notices.
- Unearth off the radar prospects with strong financial traits by scanning the 18 high quality undiscovered gems while they still sit outside the mainstream spotlight.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com