


Trial Wins Might Change The Case For Investing In Bayer Stock (XTRA:BAYN)
- Bayer reported new clinical data from its OASIS trials for Lynkuet on sleep disturbance in menopausal women and interim Phase III DASL-HiCaP results showing Nubeqa plus standard therapy improved metastasis free survival and prostate specific antigen outcomes in high risk prostate cancer.
- These trial readouts reinforce how Bayer’s newer therapies target specific unmet needs in women’s health and prostate cancer, which directly connects to efforts to refresh the pharma portfolio as older products face pressure.
- We will examine how Bayer’s investment narrative is affected by these Lynkuet sleep and Nubeqa metastasis results as well as by broader pipeline execution.
Scan how Bayer’s targeted menopause and prostate cancer therapies compare with other focused healthcare plays by running your next idea through our hand picked 130 healthcare AI stocks.
Bayer Investment Narrative Recap
To own Bayer, you need to believe the pharma pipeline and Crop Science overhaul can eventually translate into cleaner earnings and steady free cash flow despite heavy legacy issues. The short term swing factor is still execution on cost and working capital in Crop Science and keeping litigation cash outflows from grinding progress.
The fresh Lynkuet and Nubeqa data supports the idea that Bayer is steadily rebuilding its prescription portfolio, but it does not remove the main near term overhangs. Litigation payments, large capex such as the planned Ohio site, and any hiccups in the crop restructuring remain the biggest risks to the story right now.
The Nubeqa update in high risk prostate cancer appears most relevant for the nearer term Bayer equity story. The interim DASL HiCaP readout showed a statistically significant 58% reduction in metastasis or death risk versus placebo plus standard therapy, and a 4 year metastasis free survival rate of 95% versus 88% on conventional imaging.
For a shareholder, that kind of data goes directly to the question of whether new oncology and specialty drugs can offset older product pressure and support the longer term margin mix. The commercial upside still depends on label changes, physician uptake and competition, so this result strengthens the pharmaceutical pipeline narrative rather than changing the broader risk profile.
Bayer's current analyst narrative points to revenues of €49.0b and earnings of €3.7b by 2029, based on 2.6% yearly top line growth and an earnings swing of €5.4b from an earnings loss of €1.7b today.
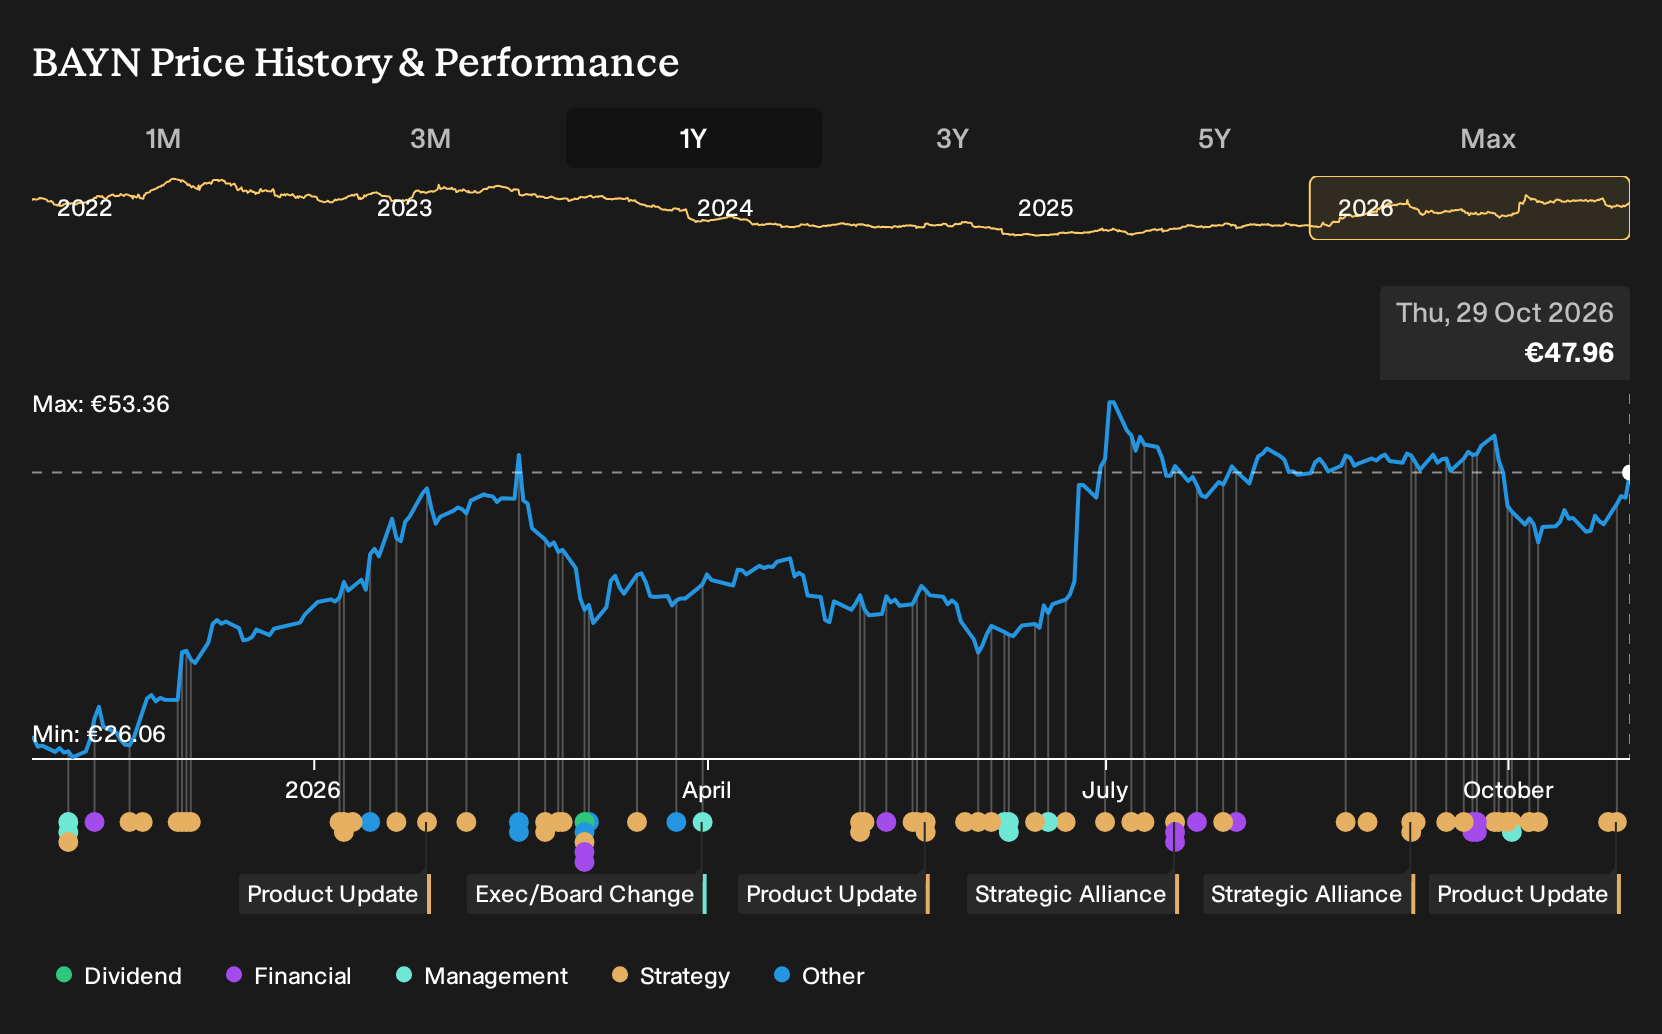
Uncover how Bayer's fair value indicates a 21% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some bullish analysts treat Bayer’s AI and data driven pipeline as the real swing factor for your thesis, more than any single Lynkuet or Nubeqa update. Before this news, the most optimistic group was already penciling in revenue of about €50.8b and earnings of €6.0b by 2029. That is far above the consensus view, which expected €49.0b of sales and €3.7b of earnings. These projections were set before the recent menopause and prostate cancer data, so you should expect opinions, and possibly those forecasts, to move as more investors reassess Bayer’s story from different angles.
Explore 6 other Bayer fair value estimates, including one that suggests up to 201% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Bayer research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Bayer. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bayer's overall financial health at a glance.
Looking For More Investment Ideas Beyond Bayer?
Once you have formed a view on Bayer, it can help to compare that thesis against a few very different types of opportunities so you see where the risk and reward really feel worth it.
- If capital protection sits high on your list, check out a group of companies with relatively resilient profiles through the 229 resilient stocks with low risk scores.
- For investors hunting for mispriced quality, scan a curated set of potential bargains with the 195 high quality undervalued stocks.
- If you prefer durable balance sheets and cleaner fundamentals, filter for candidates with stronger financial footing using the list of solid balance sheet and fundamentals (207 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com