


Methanex (TSX:MX) Stock May Be 50% Undervalued As A 5% Buyback Starts
Methanex has delivered a powerful run over the past year, and the latest buyback announcement puts the focus squarely on what its cash flows are really worth. With the share price at $87.77 as of the last close, the key issue is whether that market tag still lines up with the cash the business can generate over time.
- The stock has returned 87.9% over the past year, which puts a lot of expectations into the price and raises the question of whether the underlying cash flows can support that kind of re-rating.
- Management has launched a plan to repurchase up to 5% of outstanding shares, a move that can lift per share cash flow metrics if the cash used for buybacks proves well timed relative to the firm’s intrinsic value.
- What if you looked at Methanex through its earnings instead? See why Methanex's 54.9x P/E tells a different valuation story.
The issue now is whether Methanex's current share price is justified by its cash flows when judged against an intrinsic value estimate based on a Discounted Cash Flow (DCF) approach.
If this renewed focus on Methanex's cash flows has your attention, it can be useful to compare it with a focused list of 4 high quality undervalued stocks.
Is Methanex Still Cheap on Cash Flow?
The Discounted Cash Flow (DCF) approach here looks at the cash Methanex can return to shareholders over time, then discounts it back to today. On the latest twelve month numbers, the business produced roughly $800 million of free cash flow, which is a solid base for any intrinsic value model. Forecasters then expect free cash flow to settle into a lower but still sizeable range rather than climb steadily, so the DCF uses a recovering then easing profile rather than an aggressive growth story.
The projections, combined with the current CA$87.77 share price, mean the DCF model puts Methanex's estimated intrinsic value substantially above where the equity trades today. Because the Q3 2026 update came with a 5% buyback plan funded by strong recent cash generation, the market reaction around that news helps explain why the price has moved closer to, but not all the way up to, the cash flow estimate. Readers who want to see how those cash flow assumptions translate into a per share value can review the full model and comparison here. Find out what Methanex could be worth using our Discounted Cash Flow (DCF) estimate.
The Methanex Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Methanex valuation puzzle leaves off by spelling out which expectations for future growth, profitability and earnings would need to hold for the shares to be worth meaningfully more or meaningfully less than today’s price on the Community page. Each scenario links a fair value estimate to a particular storyline about Methanex's potential catalysts and main risks, so you can track over time which version is actually playing out.
One of the top community narratives on Methanex: roughly fairly valued
"Methanex's production and efficiency improvements, together with the OCI acquisition, are expected to expand capacity and improve earnings power over time…"
Discover why this Narrative puts Methanex at roughly fairly valued.
Methanex’s valuation story is only part of the picture
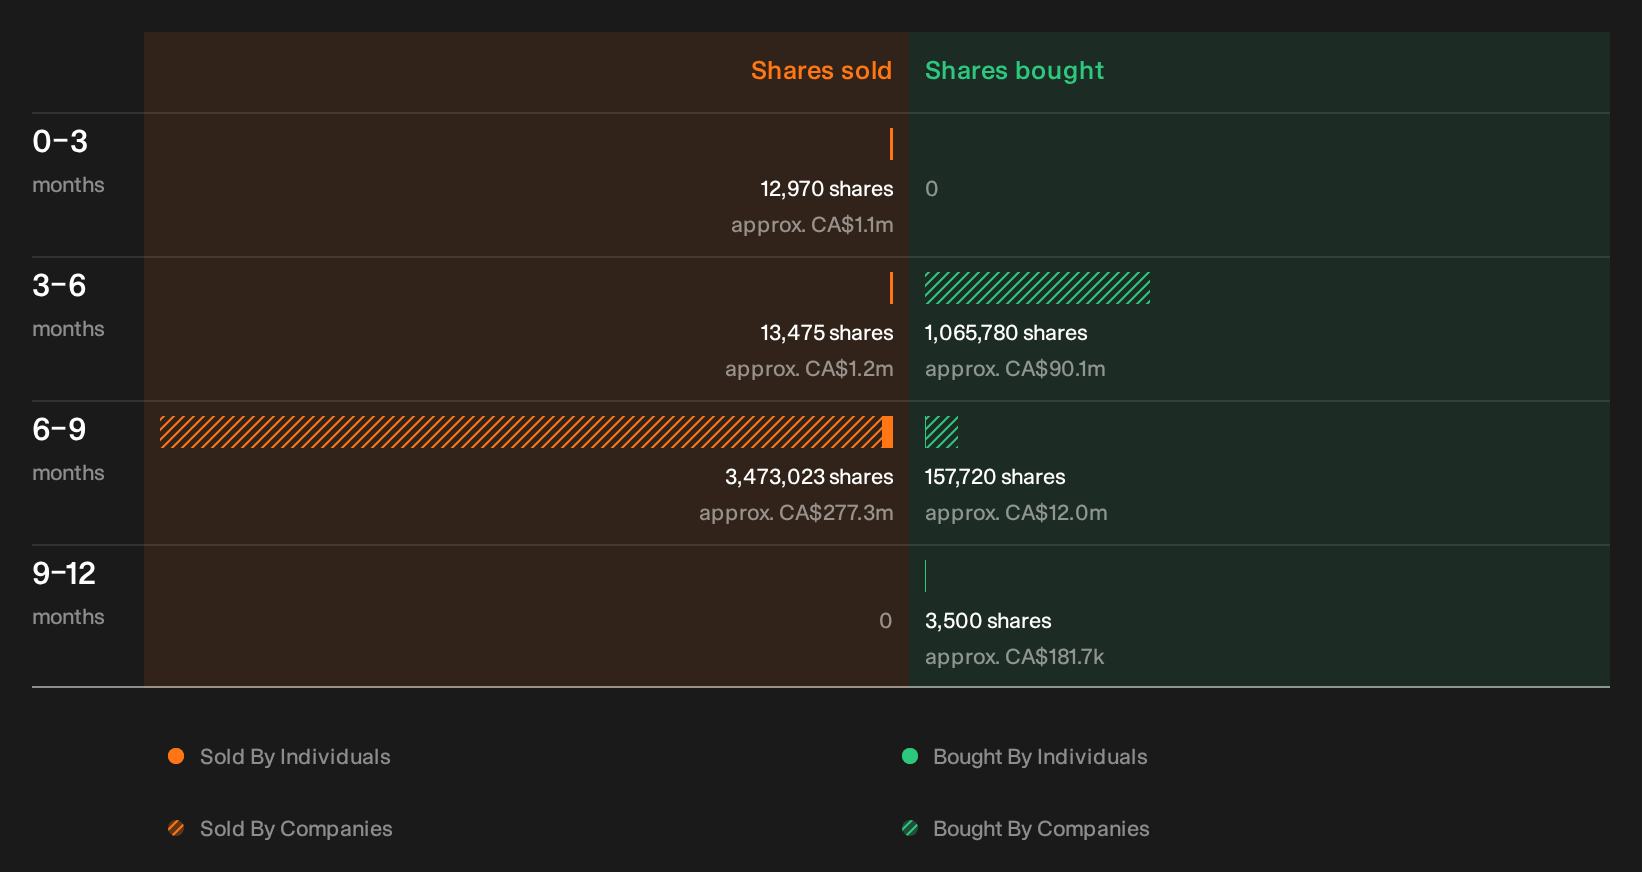
Price and cash flow tell one story for Methanex, but the recent trading activity by key insiders raises a separate question about how those closest to the business are acting with their own holdings. See the recent insider selling flagged for Methanex.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com