


What Resolute Mining Bulls Got Right
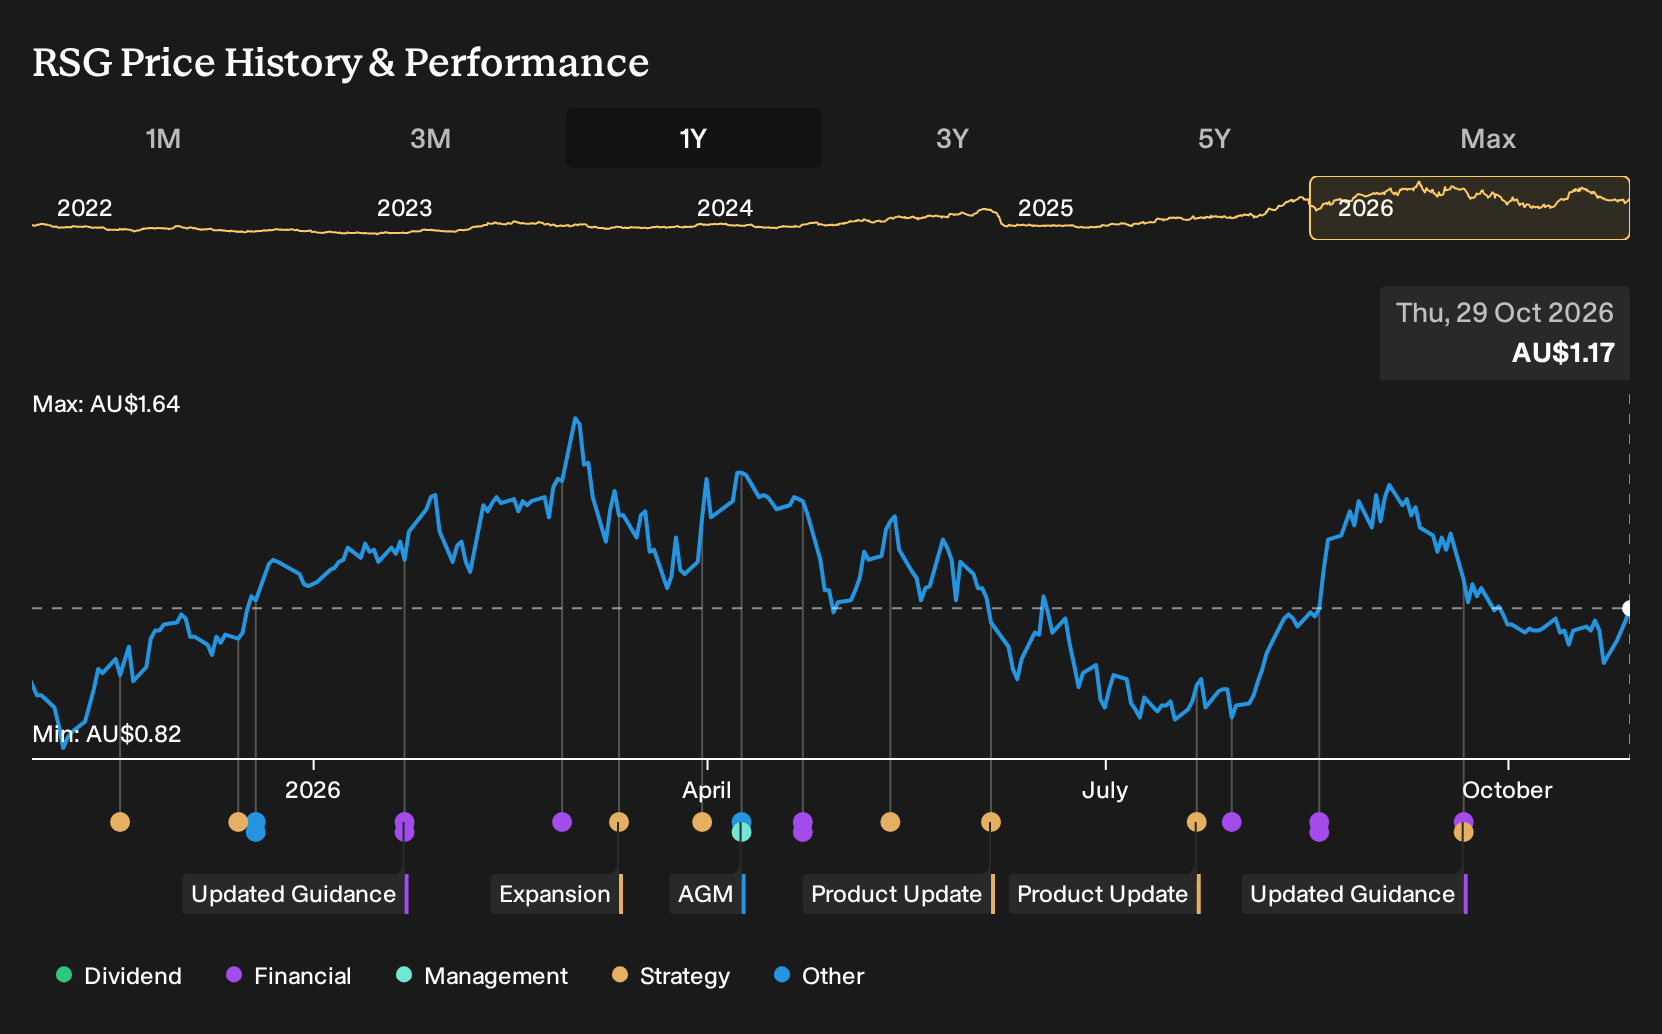
If you had bought Resolute Mining on 29 October 2025 and simply sat tight, the outcome looks deceptively clean. Holding Resolute Mining over the past year would have returned 22.5%, including dividends. That result sits between bullish talk of automation and Doropo-driven growth on one side, and warnings about West African risk, security issues, and permitting delays on the other. If you were weighing those trade offs back then, which side of the argument would have felt more convincing?
Resolute Mining is not the only name tied to this theme. Zero in on 35 elite gold producer stocks and compare how each one is priced.
The Two Futures Investors Saw For Resolute Mining
The shares cost A$0.98 at the start of the period, so every forecast for Resolute Mining had to be judged against that live market quote.
The bullish story argued that automation and new projects could reshape the business. That view pointed to a Fair Value near A$1.8, essentially the price implied if operational efficiency, the Doropo ramp up and a larger production profile all played out as hoped.
The cautious camp saw more fragility. This bear narrative pointed to a Fair Value around A$0.75, reflecting concerns about West African political risk, cost pressure at Syama and potential dilution from future Doropo funding.
What The 2026 Evidence Did To The Resolute Mining Argument
The key test for Resolute Mining was whether West African risk would overwhelm the growth story. Syama production setbacks in Mali, tied to security and supply issues, challenged the bullish view that operations could run smoothly. At the same time, H1 2026 results showed revenue and net income above H1 2025, with net margin rising from 13.1% to 21.9%, and Doropo staying on schedule. Overall, the evidence cut both ways.
The episode turned on one assumption investors made in October 2025: operational execution would justify higher Fair Value targets. When you assess another miner, focus on how production volumes, project timelines and reported net margin track against the original promise, rather than letting short term share moves tell the story for you.
What Today's Price Already Assumes About Resolute Mining
Resolute Mining now trades at A$1.17 after a 22.5% gain over the past year, with this Narrative’s Fair Value sitting above that quote rather than below it.
The Narrative leans on Doropo and ABC turning today’s project list into a bigger, lower cost West African producer. The question is whether Doropo construction and ABC drilling really can deliver those extra ounces at controlled all in sustaining cost.
"The main requirement is successful execution on Doropo construction and ABC drilling and studies, while keeping group AISC under control despite higher fuel and royalty costs and operational risk in Mali. The growth narrative relies heavily on Doropo and the ABC project lifting group production from 2028."
One Narrative disagrees with today's price. → See where this Narrative says Resolute Mining should trade
Looking One Step Beyond Resolute
Resolute Mining ties your returns to gold, geology and West African politics. You could stop there. Or you could ask what else miners need.
Gold projects rely on steady fertilizer supply in the background. Farmers still need crop nutrients that do not depend on the same regions Resolute does.
One smaller operator is trying a different approach to supplying potash. It uses horizontal drilling and solution mining to reach nutrient-rich seams underground.
The idea is simpler, cheaper surface works with less waste left behind. If it works at scale, that nutrient stream could matter far beyond any single gold stock.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 61% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com