


What SES (ENXTPA:SESG)'s CANAL+ Renewal Means For Shareholders
- SES reported that CANAL+ has renewed and extended its satellite capacity agreement through 2040, covering video and pay TV delivery across Europe, Africa and the Caribbean to more than 40 million subscribers in 70 countries.
- The long-dated CANAL+ renewal signals demand for SES’s video distribution infrastructure at multiple orbital positions and helps anchor capacity utilisation in a segment where structural pressure and contract churn have been key concerns.
- This article reviews how SES’s long term investment narrative is influenced by the extended CANAL+ capacity agreement and revenue visibility.
Scan how SES compares with other long-contract broadcasters by reviewing the hand-picked 607 high quality undiscovered gems that also rely on multi-year distribution deals for visibility.
SES Investment Narrative Recap
To own SES, you need to believe the multi orbit connectivity plan can turn heavy projects like O3b mPOWER, meoSphere and IRIS2 into durable cash flow, while the video arm remains a useful cash engine rather than a drag. The extended CANAL+ agreement supports that view by adding visibility in a segment under structural pressure.
In the near term, the key catalyst is execution on Networks, where Mobility and Government already account for most revenue, and on integrating Intelsat to reach the targeted €210 million cost synergies. The biggest risk remains financial strain, with interest and an 11.57% dividend not well covered by current earnings or free cash flow.
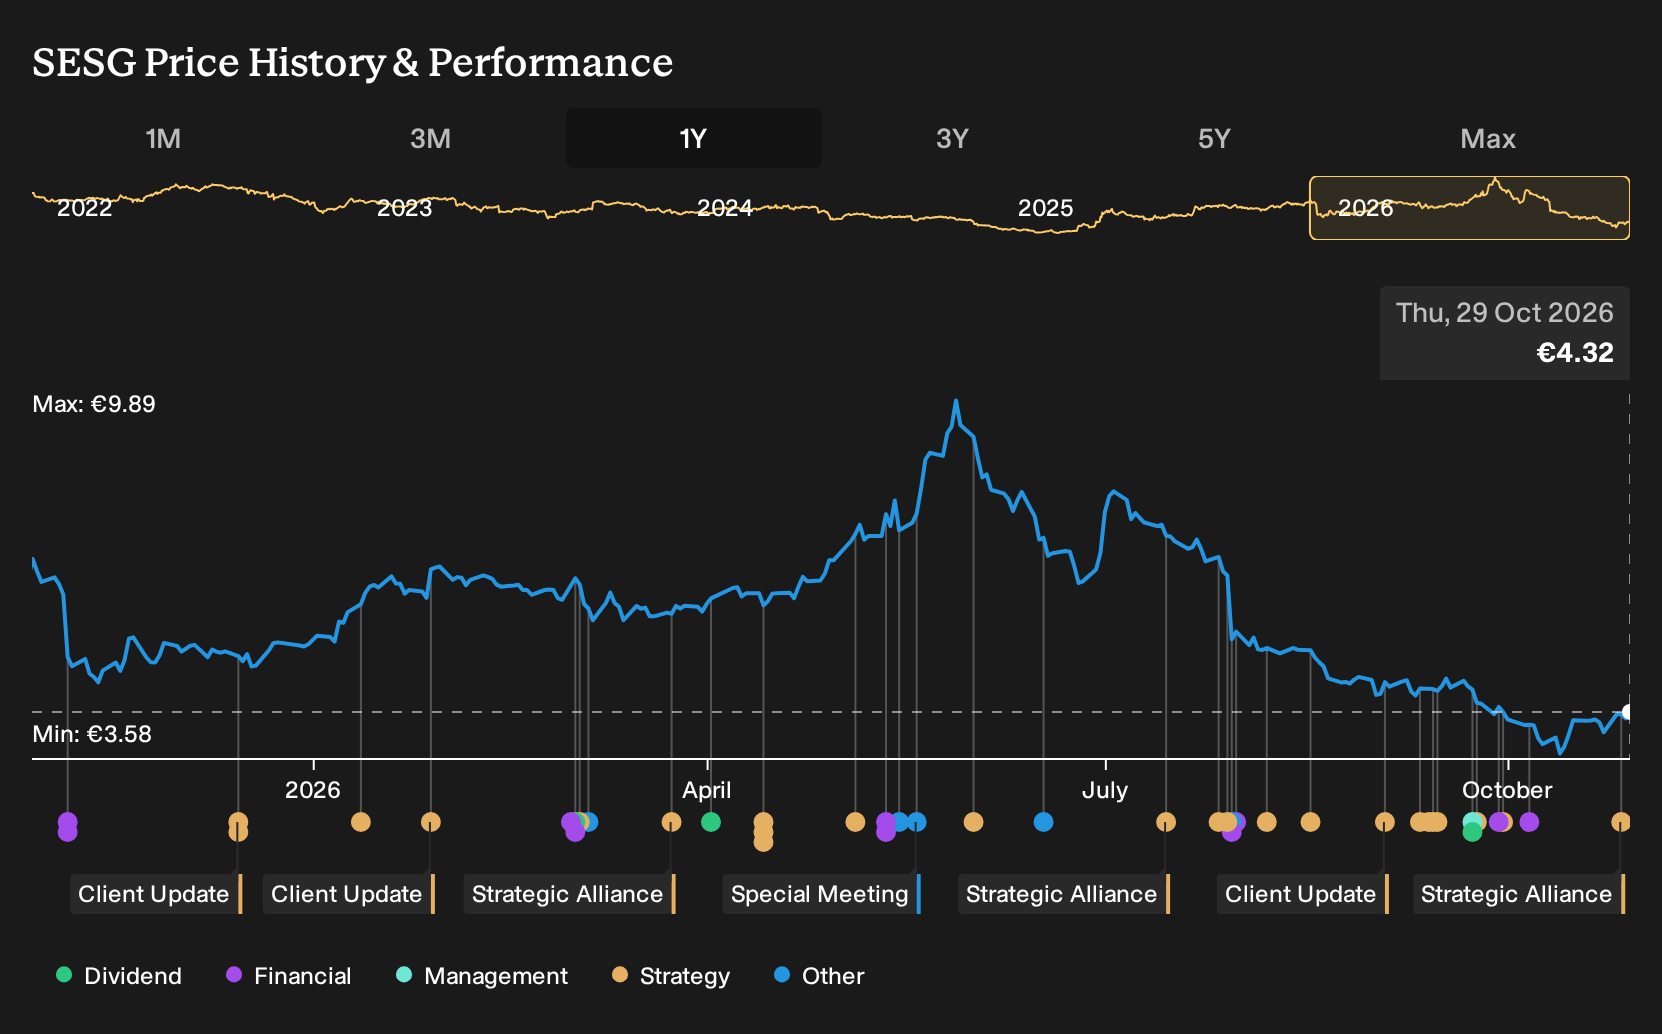
Among recent developments, the front loaded 2026 CapEx plan of about €700 million is the announcement that really frames this CANAL+ renewal. SES is committing substantial spend into software defined multi orbit constellations while still reporting a loss of €305 million on €3.251b of revenue and carrying an adjusted net debt to EBITDA ratio of 4.1x.
In that context, the long CANAL+ contract looks more like a stabiliser than a growth story. It complements ARD and other long dated video renewals, helping underpin cash generation while SES focuses on Government, Mobility and IRIS2 opportunities that depend on lumpy awards and careful capacity redeployment to avoid weaker margin usage and delay in deleveraging.
SES' narrative projects €3.4b revenue and €81.6 million earnings by 2029. This assumes 5.1% yearly revenue growth and an earnings improvement of about €233 million from a loss of €151.0 million today.
Uncover how SES' fair value indicates a 91% potential upside to its current price that could narrow quickly if sentiment turns.
Exploring Other Perspectives
Some of the lowest SES analysts focus less on contract wins and more on the risk that meoSphere slips and leaves current fleets harder to fill. Before this CANAL+ deal, that group was modelling revenue drifting to about €3.1b by 2029 with earnings anywhere between €144.1 million and a €91.1 million loss. That is a far more cautious story than the consensus view. It shows how strongly opinions can differ, so treat this new agreement as a fresh input and compare these contrasting forecasts for yourself.
Explore 2 other SES fair value estimates, including one that suggests it could be worth just €7.50!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your SES research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for SES. The report includes a comprehensive fundamental analysis summarized in a single visual called the Snowflake, which makes it easier to evaluate SES' overall financial health at a glance.
Looking for more SES sized investment ideas?
If SES has helped clarify what you want from a long term holding, it can be useful to widen the lens and see how other companies with different strengths line up against that checklist. The Simply Wall St Screener lets you move from a single story to a whole watchlist built around the traits that matter most to you.
- If resilience matters most to you, check out a curated 228 resilient stocks with low risk scores that may appeal if you prefer calmer portfolio swings.
- If dependable balance sheets feel more important than headline growth, scan a targeted list of solid balance sheet and fundamentals (207 results) that could help you focus on financial strength first.
- If you want income to play a bigger role in your returns, review a focused 228 dividend fortresses that prioritises higher yielding payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com