


Ryerson (RYI) Stock Rallies On Q3 Earnings Beat Despite Debt Pressure
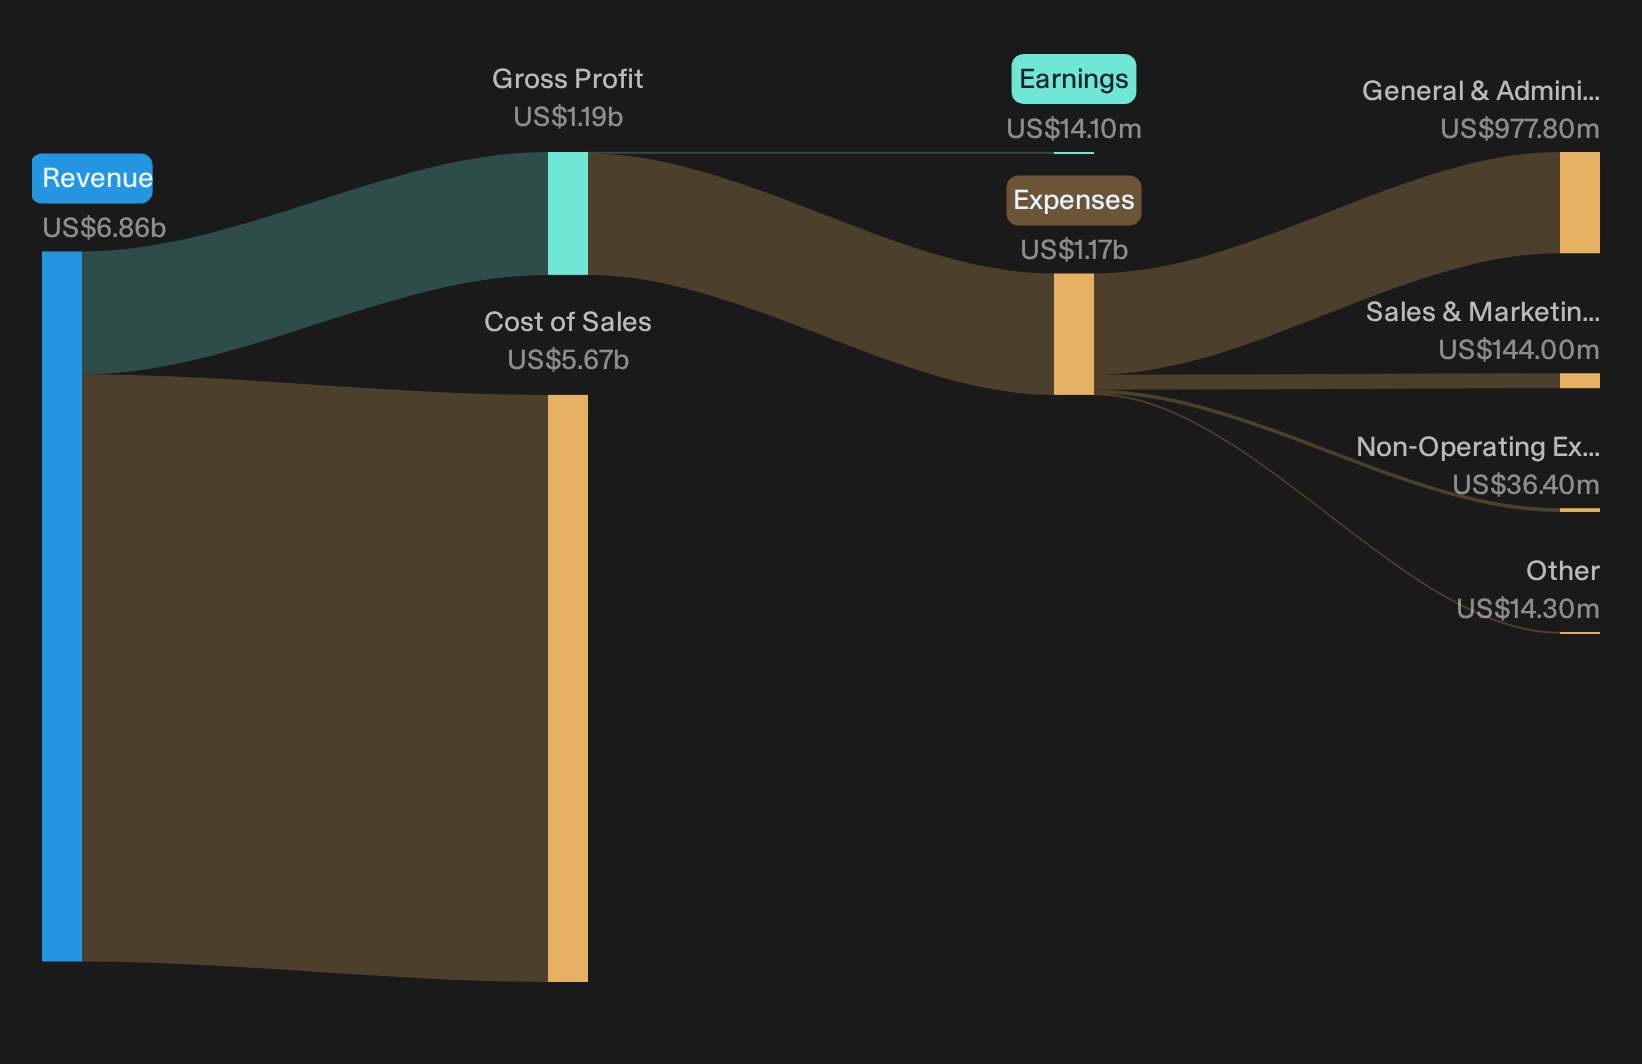
Ryerson stock jumped 4.5% to about $31 today after the Q3 2026 report hit, a strong move for a cyclical metals distributor that usually trades on shipment tons and pricing spreads rather than headlines alone. The quarter delivered the market a clean story. Revenue came in at roughly $2.2b and net income reached $32m, helped by adjusted EBITDA of $115m that topped management’s own guidance. Short term traders see a beat. Longer term investors see a business trying to rebuild credibility after prior losses, with valuation and balance sheet strain still front of mind.
Love the clean Q3 beat from Ryerson Holding but concerned about a cyclical distributor with balance sheet strain and prior losses on your radar? Consider filtering for companies that pair solid fundamentals with stronger financial footing in our list of solid balance sheet and fundamentals stocks (22 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): US$2,177.8m vs. US$1,161.5m (very large increase in reported quarterly sales)
- Net Income (Excl. Extra Items, Q3 2026 vs Q3 2025): US$32.0m vs. a loss of US$14.8m (swing from loss to profit)
- Basic EPS (Q3 2026 vs Q3 2025): US$0.62 vs. a loss of US$0.46 per share (move back into positive earnings per share)
- Adjusted EBITDA excluding LIFO (Q3 2026 vs Q3 2025): US$115m vs. not disclosed for Q3 2025 (indicator of core earnings strength excluding LIFO inventory accounting impact)
Prefer clean visuals over another wall of earnings tables and inventory jargon? See Ryerson Holding’s full financial picture with an easy-to-scan view of its balance sheet strength in the interactive company report for Ryerson Holding.
Ryerson bullish story meets cleaner earnings
Ryerson looks closer to that diversified industrial backbone idea when you line up Q3 with the narrative. Revenue of about US$2.2b and net income of US$32m came in ahead of guidance, and adjusted EBITDA of US$115m points to healthier underlying economics. Integration of Olympic is driving early synergy benefits and same store shipments outpaced industry benchmarks, which supports the value added processing angle. Recent share price strength over 7, 30 and 90 days suggests investors are at least tentatively rewarding better execution rather than treating this as a purely cyclical trade.
Bear case still circles leverage and cyclicality
Concerns about a cyclical distributor with a stretched balance sheet are not fully answered yet. Net debt of about US$966m and leverage above 3x keep financial risk on the table even as management targets lower levels. Working capital used cash in Q3 and rising material costs pushed LIFO expenses higher, which shows how quickly inventory and pricing can work against Ryerson. Q4 guidance implies softer shipments and lower net income than Q3, so earnings still lean heavily on cycle sensitive volumes and spreads rather than a fully de risked model.
After a quarter where leverage, interest cover and working capital swings all matter, it helps to see whether these are isolated issues or part of a broader pattern. Review the independent risk analysis for Ryerson Holding which shows 5 important warning signsHunt For Quiet Fundamental Shifts
Ryerson Holding just reported a cleaner quarter that clarified leverage, inventory and guidance. The real opportunity is finding stocks that could be undervalued before updated figures prompt investors to reassess expectations.
- Company 1 - 43% below our estimate - sells large-scale LED systems for sports, commercial and transport projects as demand shifts toward integrated, software-linked display networks.
- Company 2 - 46% below our estimate - turns an attention-focused platform into an AI-driven system that decides what content appears and which products are surfaced to users.
- Company 3 - 32% below our estimate - supplies high-end accelerators for AI data centers as customers retool power-intensive infrastructure and software stacks around its specialized computing platform.
That is three of the list. See all 30 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com