


3 Reshoring Stocks Investors Are Watching As USMCA Rules Shape North American Manufacturing
North America’s reshoring push is no longer just a policy headline; it is starting to shape where factories get built, where data is stored, and which companies sit in the slipstream of USMCA talks. That shift could leave some stocks quietly exposed to a powerful trend while others are left behind. This article spotlights three reshoring related opportunities, all filtered from our screener, and explains how current policy signals may matter for each one.
The stocks covered below are only a starter pack. The full reshoring screen surfaced 26 more industrial and manufacturing companies with equally strong supply chain narratives that are not detailed in this article. To identify your own highest conviction reshoring plays, head straight into the North American Advanced Manufacturing & Supply-Chain Reshoring screener
Benchmark Electronics (BHE)
Overview: Benchmark Electronics provides design, engineering, manufacturing, testing, and supply chain services that help original equipment manufacturers regionalize and secure production.
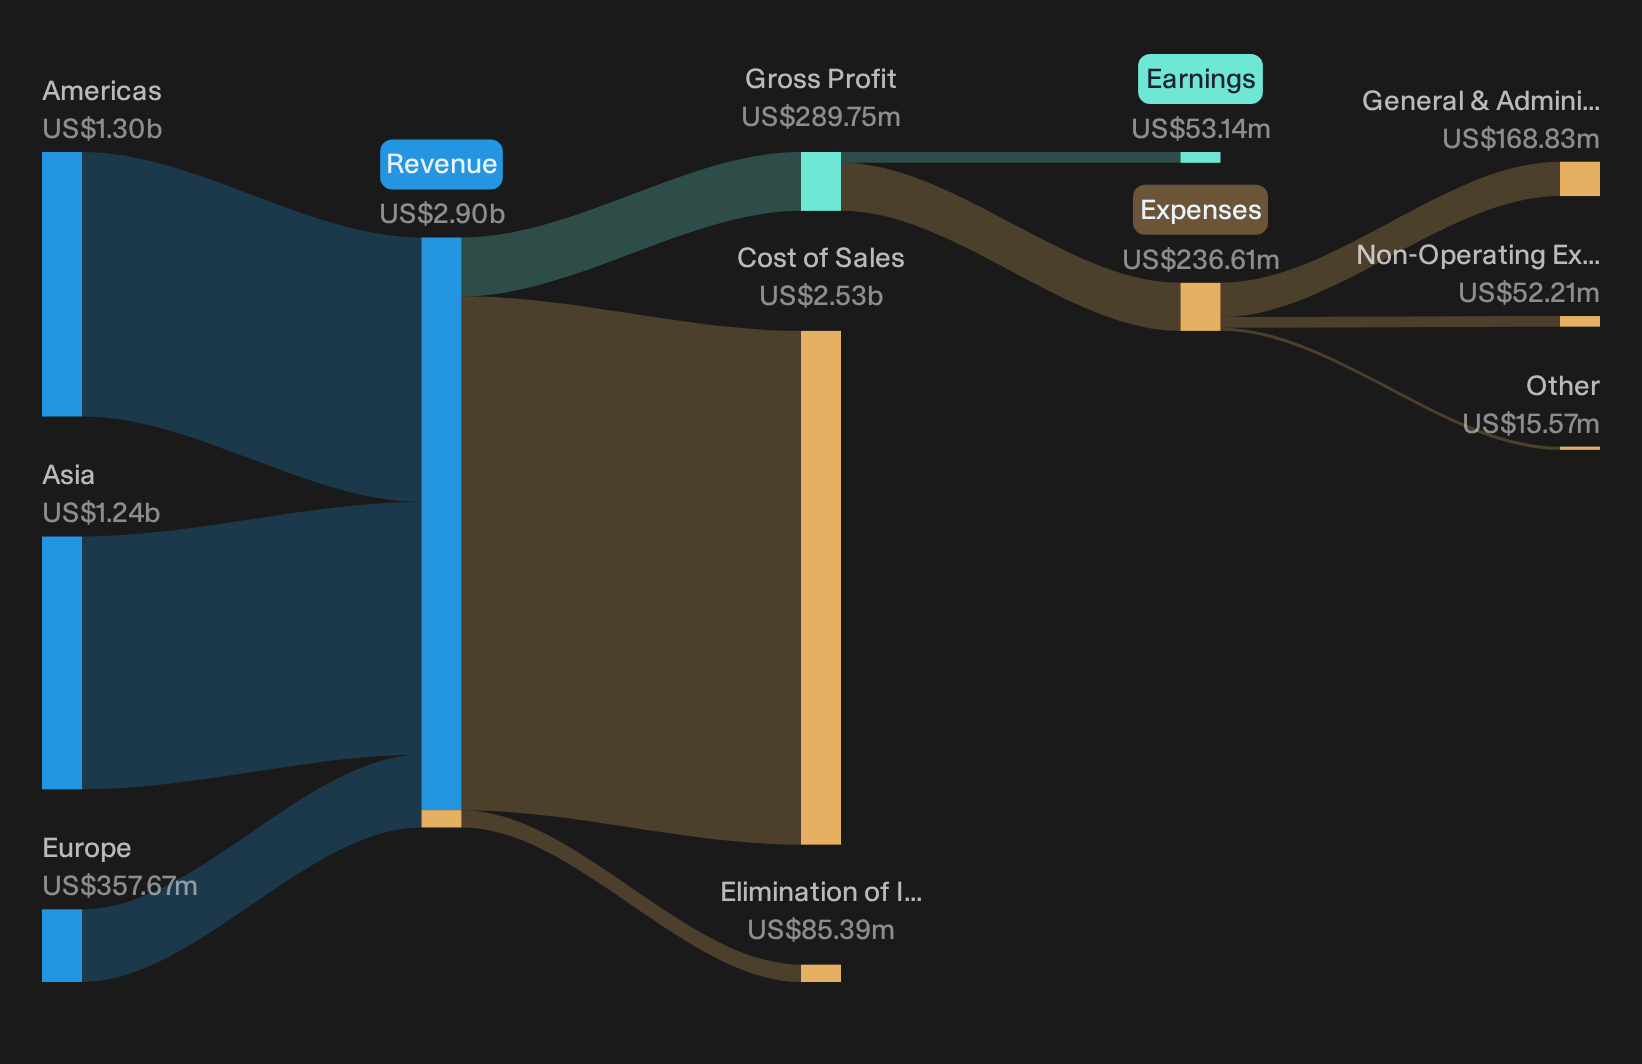
Operations: Benchmark generates about US$1.3b in revenue from the Americas and US$1.2b from Asia, with roughly US$358 million from Europe.
Market Cap: US$2.5b
Benchmark Electronics matters for this reshoring screen because its North American footprint and engineering depth give OEMs practical ways to shift production closer to end customers.
"Benchmark Electronics is positioned to benefit from surging demand for advanced computing and AI infrastructure, now supported by 41% and 71% year-over-year AC&C revenue growth in Q1 and Q2 2026, driven by clustered AI and on prem cloud programs and by recognition as HPE’s 2026 Manufacturing Partner of the Year."
What happens to margins and cash generation if a single, fast growing piece of this AI and medical mix changes direction?
That margin question is exactly what the full narrative for Benchmark Electronics unpacks, showing how reshoring, AI programs, and medical demand could be accelerating or masking the next leg of returns for Benchmark Electronics.
ATS (TSX:ATS)
Overview: ATS Corporation builds, automates, and services complex manufacturing lines, helping North American producers retool plants for regional reshoring under USMCA.
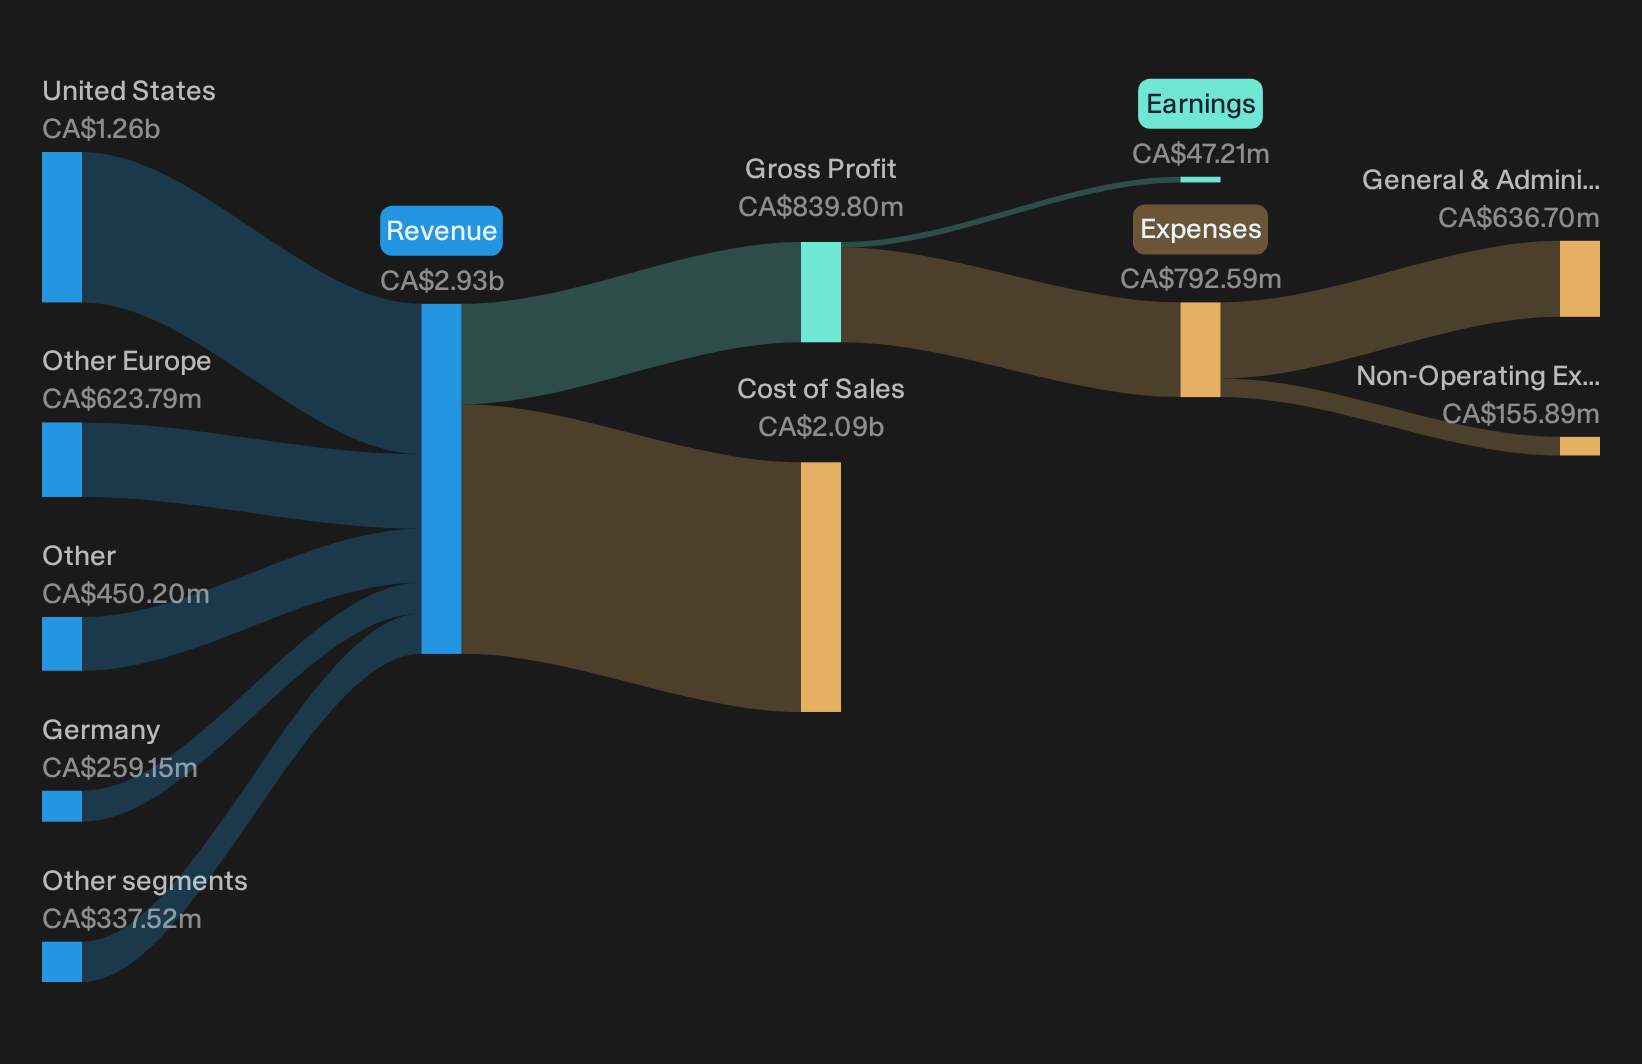
Operations: ATS generates about CA$2.9b from Automation Systems, with sales concentrated in the United States at CA$1.3b and further exposure across Europe and Canada.
Market Cap: CA$2.6b
ATS matters for this reshoring screen because its automation platforms and factory software help manufacturers redesign cross border production so goods qualify cleanly under USMCA rules.
"The ongoing mix shift toward higher margin aftermarket, services, and other recurring or faster turn revenue, where services already support higher gross margins and the goal is to move closer to peers with more than 40% aftermarket exposure, can gradually raise ATS’s gross margin and support more stable earnings."
The real swing factor is what happens if one quiet piece of that reshoring heavy project mix falls short of the margin story investors expect.
If that quiet piece interests you, zoom into the full narrative for ATS to see how reshoring projects, service mix and execution risk are really interacting for ATS.
Jabil (JBL)
Overview: Jabil provides engineering, manufacturing, and supply chain services that help global brands regionalize production across the U.S., Mexico, and Canada.
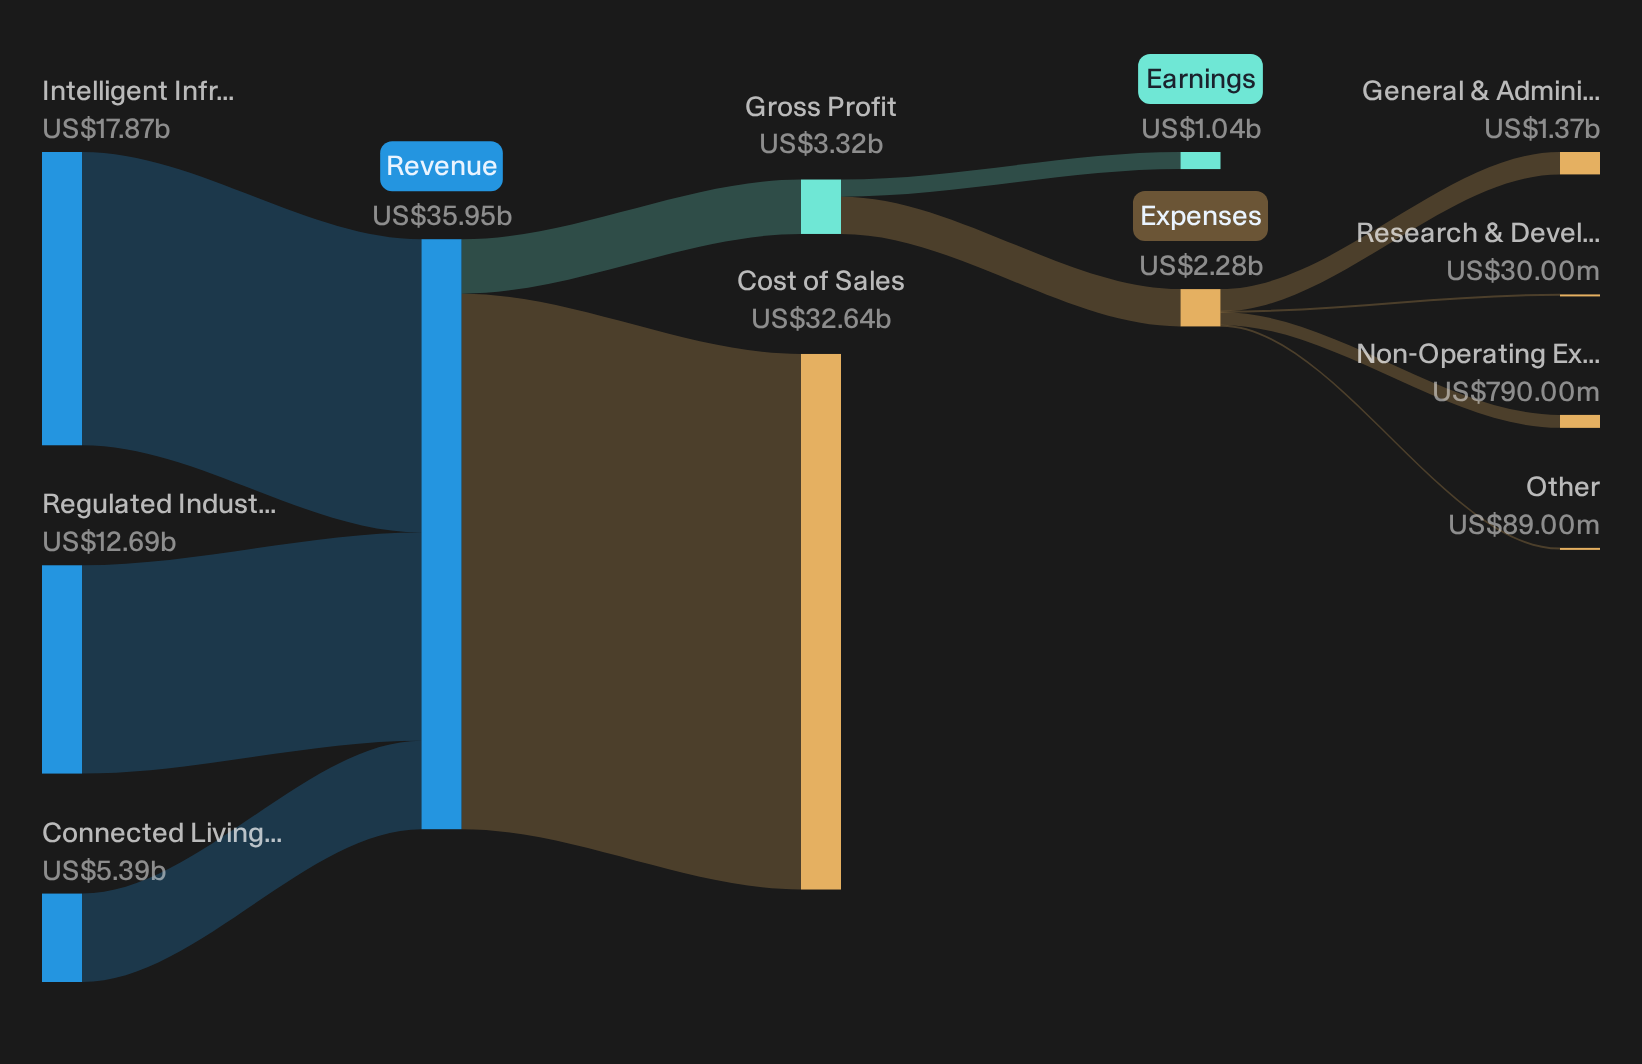
Operations: Jabil generates about US$12.7b from Regulated Industries, US$17.9b from Intelligent Infrastructure, and US$5.4b from Connected Living and Digital Commerce.
Market Cap: US$29.2b
Jabil matters for this reshoring focused screen because its large North American production footprint and contract manufacturing model give global customers a practical way to rewire supply lines under a more predictable USMCA framework.
"Jabil's significant U.S. manufacturing footprint still provides room to shift production in response to tariff or trade changes. This flexibility can help protect revenue and support earnings if customers move more programs onshore."
The open question is how much that flexibility can support margins if one pressure point in AI infrastructure demand or working capital turns sharply.
That pressure point is exactly where the full narrative for Jabil pulls the story together, showing how Jabil’s reshoring exposure and AI programs could be accelerating or masking future returns.
Seeking Alternatives Before Everyone Else?
Fresh themes move first, then momentum takes over and late money gets caught chasing breakout stories. Scan under the radar ideas while it still matters and get in early.
- Spot steady compounders before yield hunters crowd in and comb through 6 dividend fortresses to highlight income opportunities that might hold up when momentum cools.
- Track real-world AI adoption rather than headlines and work through 38 profitable AI stocks that aren't just burning cash to focus on businesses where revenue and cash flow already support the story.
- Position for the next leg of electrification and grid hardening and review the curated 43 power grid technology and infrastructure stocks that points to utilities suppliers and equipment players tied to that build out.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com