


Should Earnings Upgrades Require Action From Synopsys Stock Investors?
- Synopsys recently attracted attention after analysts revised earnings estimates upward and highlighted the company’s exposure to complex chip design trends and Ansys powered multiphysics tools.
- The renewed focus on Synopsys’s recurring software and IP model, along with integration of Ansys and AI centric EDA, underscores how execution on these themes is shaping expectations for future profitability.
- We will look at how Synopsys’s refreshed earnings estimates and Strong Buy ratings intersect with its existing AI and Ansys driven investment narrative.
Ride Synopsys’ breakout and see how other AI centric chip enablers measure up by scanning our hand picked 54 AI infrastructure stocks.
Synopsys Investment Narrative Recap
To own Synopsys, you need to believe its electronic design automation, Design IP and Ansys powered simulation portfolio can keep attracting complex chip and systems projects as AI centric designs spread. The short term swing factor is whether integration work, restructuring and cost actions translate into cleaner margins even as IP growth remains more muted than EDA and Ansys.
The recent breakout above key moving averages and higher earnings estimates speaks more to sentiment than to a change in the underlying thesis. Operating priorities stay the same. Synopsys still has to manage one off items, lower net margins than last year and ongoing legal and index related overhangs.
The most relevant recent data point is the positive revision to earnings expectations that accompanied the move through the 50 day and 200 day moving averages. That reinforces the idea that investors are watching how quickly Synopsys can convert Ansys scale, IP mix shift and AI infused tools into sustained profit metrics and not just revenue expansion.
For you, the key question is whether those higher earnings assumptions feel achievable given the drag from restructuring charges, integration costs and a Design IP segment that management itself frames as recovering more gradually. If Synopsys executes on cross sell, SaaS and AI agent rollouts while keeping further one off items in check, those technical signals could remain a secondary confirmation rather than a primary catalyst.
Synopsys Earnings Assumptions And Valuation Bridge
Synopsys' current analyst storyline hinges on a multi year ramp that ties its AI centric EDA, IP and Ansys footprint directly to higher profit metrics rather than just headline growth. The working model assumes revenue expands at 13.1% a year over the next 3 years while profit margins move from 11.4% today to 19.2%, so the debate is less about whether demand exists and more about how efficiently that demand converts into earnings.
On the earnings side, analysts are penciling in a move from US$1.1b in profit today to US$2.6b by around 2029, with a wide band of views that stretches from US$2.2b at the low end to US$5.1b at the top. That is roughly a 2.4x increase from current earnings, which gives a sense of how much margin expansion and operating discipline the market is effectively baking into Synopsys' integration of Ansys, its restructuring program and its push into AI enabled tools.
Synopsys' narrative projects US$13.6b revenue and US$2.6b earnings by 2029. This requires 13.1% yearly revenue growth and roughly a 2.4x earnings increase from US$1.1b today.
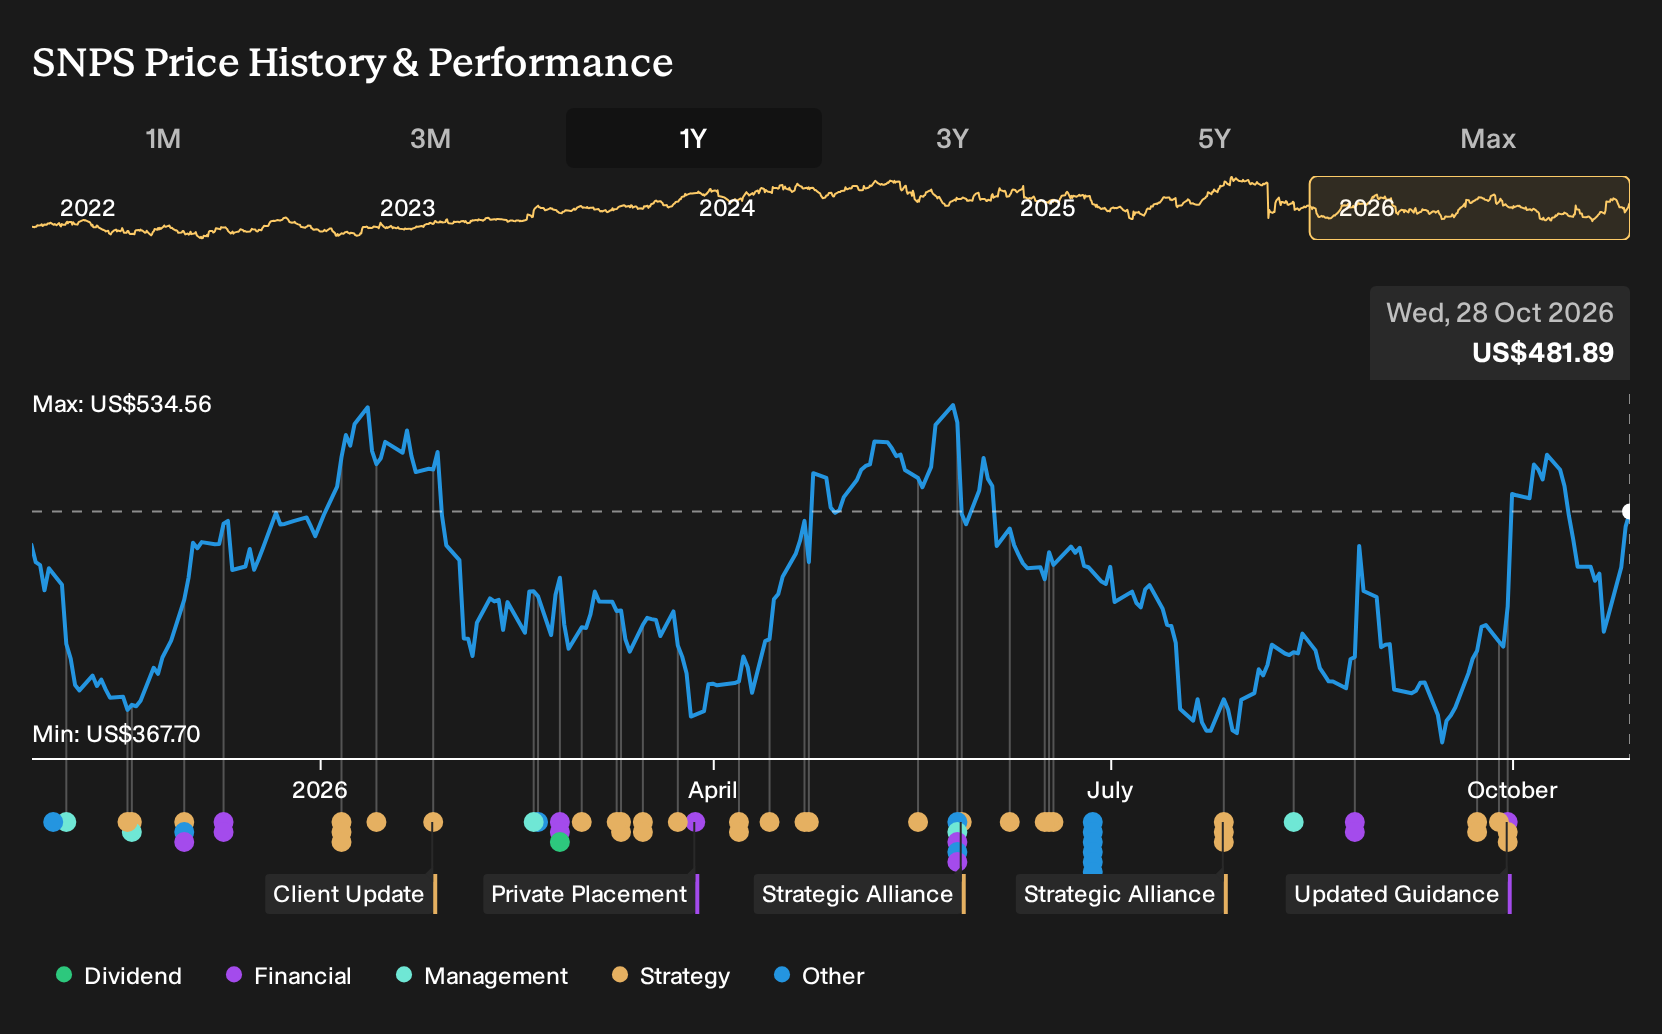
Those same forecasts flow straight into the valuation discussion, where the consensus view assumes the stock is worth US$583.99 compared with a current price of US$454.63. To line up with that target, you would need to accept a 2029 scenario where Synopsys generates US$13.6b in sales, earns US$2.6b in profit and trades on a P/E of 55.4x, which sits well above the current US Software industry multiple of 30.8x even after stepping down from about 80.9x today.
Price target dispersion is wide, with the most optimistic analysts at US$700.00 and the most cautious at US$475.00, which mirrors the spread in earnings expectations. Rather than treat any single figure as gospel, it is more practical to see this range as a menu of possible outcomes, then pressure test whether Synopsys' cost actions, Ansys integration pace and Design IP recovery path line up with the level of earnings power implied by the multiple you are willing to pay.
Uncover why Synopsys' fair value indicates a 21% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
The two fair value estimates from the Simply Wall St Community cluster tightly between about US$583.99 and US$584.80, so private investors here are unusually aligned on what Synopsys might be worth. You still need to weigh that against integration risk from Ansys and muted IP growth, then explore several contrasting viewpoints before acting.
Explore another Synopsys fair value estimate, including one that suggests it could be worth just $583.99!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Synopsys research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Synopsys. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Synopsys' overall financial health at a glance.
Looking for more investment ideas beyond Synopsys?
Once you have a view on Synopsys, it can help to compare that thesis with a few very different types of opportunities pulled from the wider market using the Simply Wall St Screener.
- If capital preservation is high on your list, start with sturdier balance sheets and see which companies make the cut in our 32 resilient stocks with low risk scores.
- If dependable income matters more to you, scan for higher yielding payers that pair dividends with business resilience through the 6 dividend fortresses.
- If you want potential mispriced opportunities, look across a curated set of fundamentally strong companies trading below their estimated worth via the 26 high quality undervalued stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com