


0% Above Fair Value? AbbVie (ABBV) On Fresh Qulipta Phase 3 Data
AbbVie (ABBV) stock is trading against a busy backdrop of clinical news, highlighted by fresh Phase 3 TEMPLE data in The Lancet Neurology that put migraine drug Qulipta up against established preventive therapy topiramate.
That clinical drumbeat has arrived alongside firm price momentum. AbbVie shares now trade at US$285.99, with a 30-day share price return of 7.40% and a year-to-date share price gain of 24.72%. The 1-year total shareholder return of 30.83% and a very large 5-year total shareholder return above 7x suggest that longer term investors have already seen considerable value creation.
Spot similar healthcare momentum stories by scanning our curated list of 36 healthcare AI stocks.Bulls point to AbbVie’s packed late stage pipeline and strong recent share gains. Bears focus on a rich multiple and dependence on a handful of key franchises. Which side does current valuation actually support?
Most Popular Narrative: 0% Overvalued
Against AbbVie’s last close at $285.99, the most followed narrative pegs fair value at about $284.79, which places the stock almost exactly in line with that framework while still tying the story to pipeline execution and cash flow durability.
Ongoing post Humira diversification, where management reports that Humira erosion of about US$18b has been offset by roughly US$28b of growth from other platforms and that 2026 guidance is almost US$10b above the pre Humira peak, reinforces the case that newer franchises can keep supporting overall revenue and adjusted EPS. Increased R&D spending toward about US$9.8b in 2026, along with the completed Apogee acquisition that adds late stage respiratory immunology assets described as a mega blockbuster opportunity, underpins expectations that AbbVie can build additional high value products that support revenue growth and maintain net margins over time.
See why 337 investors see AbbVie as 0% overvalued.
Result: Fair Value of $284.79 (ABOUT RIGHT)
Still, AbbVie’s story can shift quickly if drug price reforms bite harder than expected or if key pipeline assets stumble against rivals or in late stage trials.
Find out about the key risks to this AbbVie narrative.
Another View: AbbVie Through The P/E Lens
The SWS DCF model points to AbbVie trading at a discount to its estimated future cash flow value of $500.46, yet the P/E story pulls the other way. At 80.6x earnings versus a fair ratio of 46.3x and a US Biotechs average of 18.8x, the share price embeds a lot of optimism. Which signal do you trust more?
For investors weighing that gap between cash flow estimates and earnings multiples, Look into how the SWS DCF model arrives at its fair value.
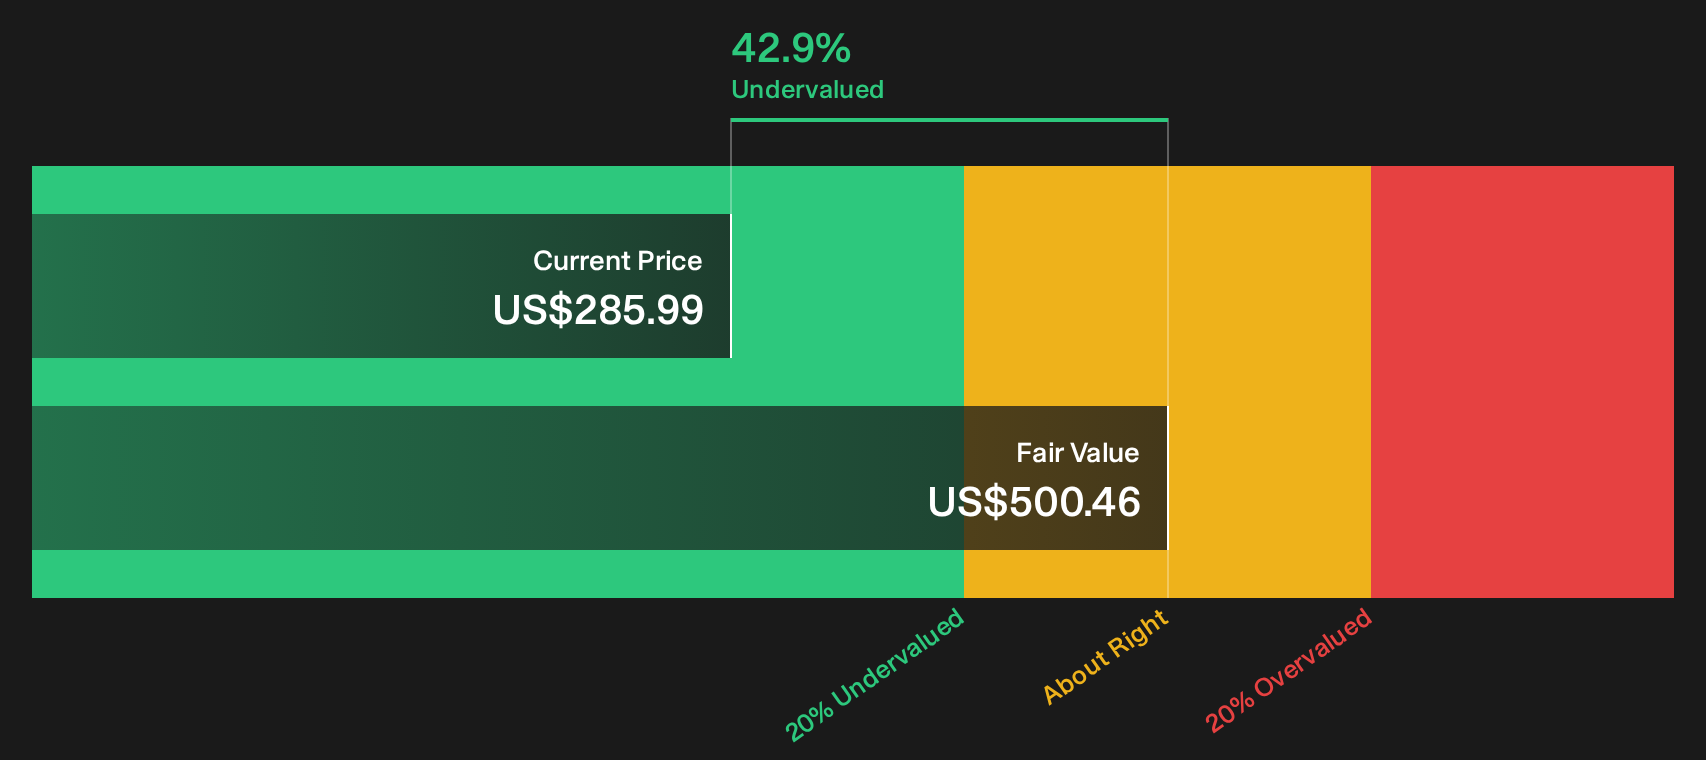
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out AbbVie for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 26 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on AbbVie so far, or just a complex story waiting to be unpacked? Act while sentiment is split and weigh both sides through the 3 key rewards and 4 important warning signs
Looking for more investment ideas beyond AbbVie?
If AbbVie has your attention, do not stop here. Fresh opportunities sit across the market, and a few minutes with a focused screener can reshape your watchlist.
- Target potential mispriced opportunities by scanning a curated mix of resilient businesses through the 26 high quality undervalued stocks.
- Strengthen your income focus by zeroing in on companies that feature 6 dividend fortresses.
- Prioritise resilience by filtering for companies with robust finances using the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com