


Ahead of Chevron Earnings, Here's What Barchart Data Says Comes Next for CVX Stock
Higher oil prices have been a boon for Chevron (CVX) stock in recent months, and the next near-term catalyst that drives it higher could be the company’s earnings on Oct. 30, according to Barchart’s options data. Consensus is for the company to report $4.78 in earnings per share (EPS) for its third quarter, which would represent an exciting 158% increase on a year-over-year basis.
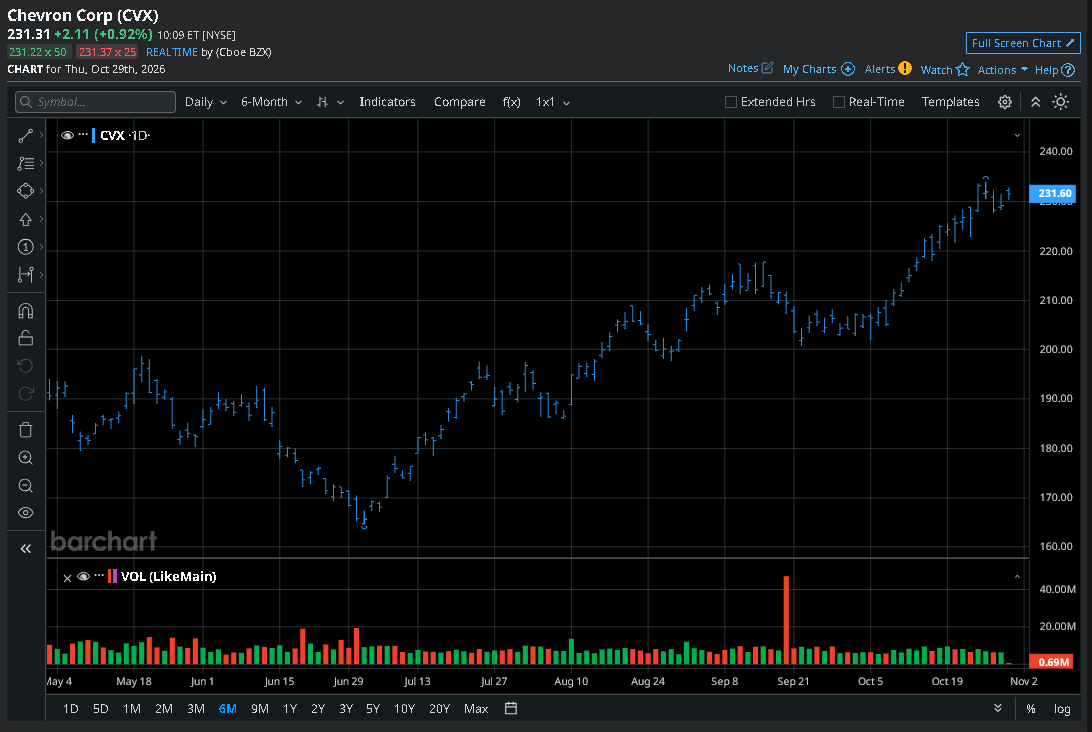
At the time of writing, Chevron shares are up about 50% versus the start of this year.
Options Sentiment Is Bullish for Chevron
Options traders seem fully convinced that CVX shares will extend gains following the earnings event on Friday. This is evidenced by the put-to-call ratio of 0.56x on contracts expiring Nov. 6. A reading under 1.00x is typically characterized as in favor of the bulls.
Barchart’s data also pegs the upper price on those derivative contracts at nearly $238, indicating Chevron could rally as much as 3.63% through the end of next week.
The oil stock also pays a lucrative dividend yield of 3.11% currently, which makes it even more attractive for income-focused investors.
William Blair Is Bullish on CVX Shares
Heading into the quarterly release, William Blair analysts assumed coverage of Chevron stock with an “Outperform” rating.
As of this writing, the NYSE-listed energy company is trading for about a 5.8x EV/EBITDAX multiple, but its global scale and asset base warrant a premium, the analysts told clients.
They expect CVX to trade at a multiple as high as 7.5x, which would translate to a per-share price of about $326, or roughly 43% above current levels.
Investors should also note that Chevron is currently trading at a forward price-to-earnings (P/E) ratio of under 13x, which makes it relatively cheaper to own than peer Exxon (XOM).
What’s the Consensus Rating on Chevron?
Wall Street firms are also convinced that CVX stock’s ongoing rally still has further room to the upside.
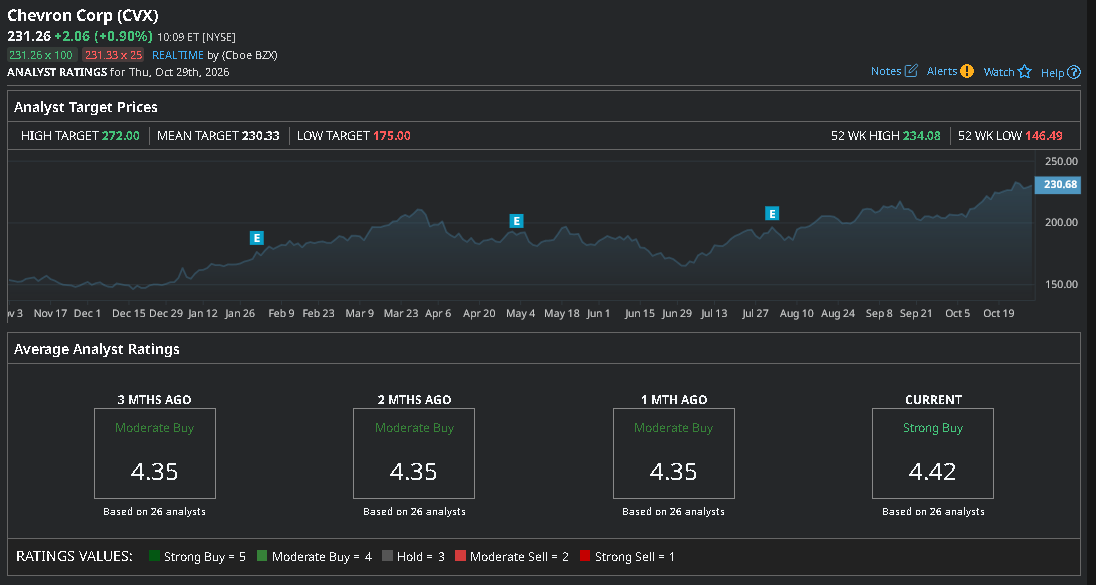
The consensus rating on Chevron sits at “Strong Buy,” with price targets as high as $272 indicating potential upside of roughly 18% from here.
On the date of publication, Wajeeh Khan did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.