


Panasonic Holdings (TSE:6752) Following Battery Buzz And CF FC7 Launch Still Looks Undervalued
Panasonic Holdings (TSE:6752) is back in focus after two product driven storylines: fresh attention on its role in thin film and printed batteries, and the Let’s note CF-FC7 laptop launch in Europe.
Recent headlines around thin film batteries and the CF-FC7 launch arrive after a sharp 30-day share price return decline of 15.56%, even though the year-to-date share price return is 78.30% and the 3-year total shareholder return is 194.48%. This suggests long-term momentum remains strong despite a near term reset.
Scan beyond Panasonic Holdings and review hand picked 54 AI infrastructure stocks that could also benefit from rising demand for AI ready hardware and power solutions.
So after a 15.56% pullback against a powerful 3 year return and solid recent revenue and net income growth, does Panasonic Holdings still offer enough upside in the valuation to compensate for the reset in sentiment?
Most Popular Narrative: 25% Undervalued
Against the last close of ¥3,706, the most followed valuation view pegs Panasonic Holdings at a fair value of about ¥4,973, suggesting the recent pullback has not closed the gap implied by that model.
Expansion of AI related devices and systems with a FY29 sales target of ¥1.4tn, backed by substantial customer awards and around ¥500bn of planned capex over FY27 to FY29, is intended to support scale benefits and higher segment profit contributions to consolidated earnings.
See why 26 investors see Panasonic Holdings as 25% undervalued.
Result: Fair Value of ¥4,973 (UNDERVALUED)
Still, Panasonic Holdings faces two clear swing factors: weaker EV battery demand in North America, and any shortfall in the planned ¥145b fixed cost savings.
Find out about the key risks to this Panasonic Holdings narrative.
Another View: Panasonic Holdings Through Market Multiples
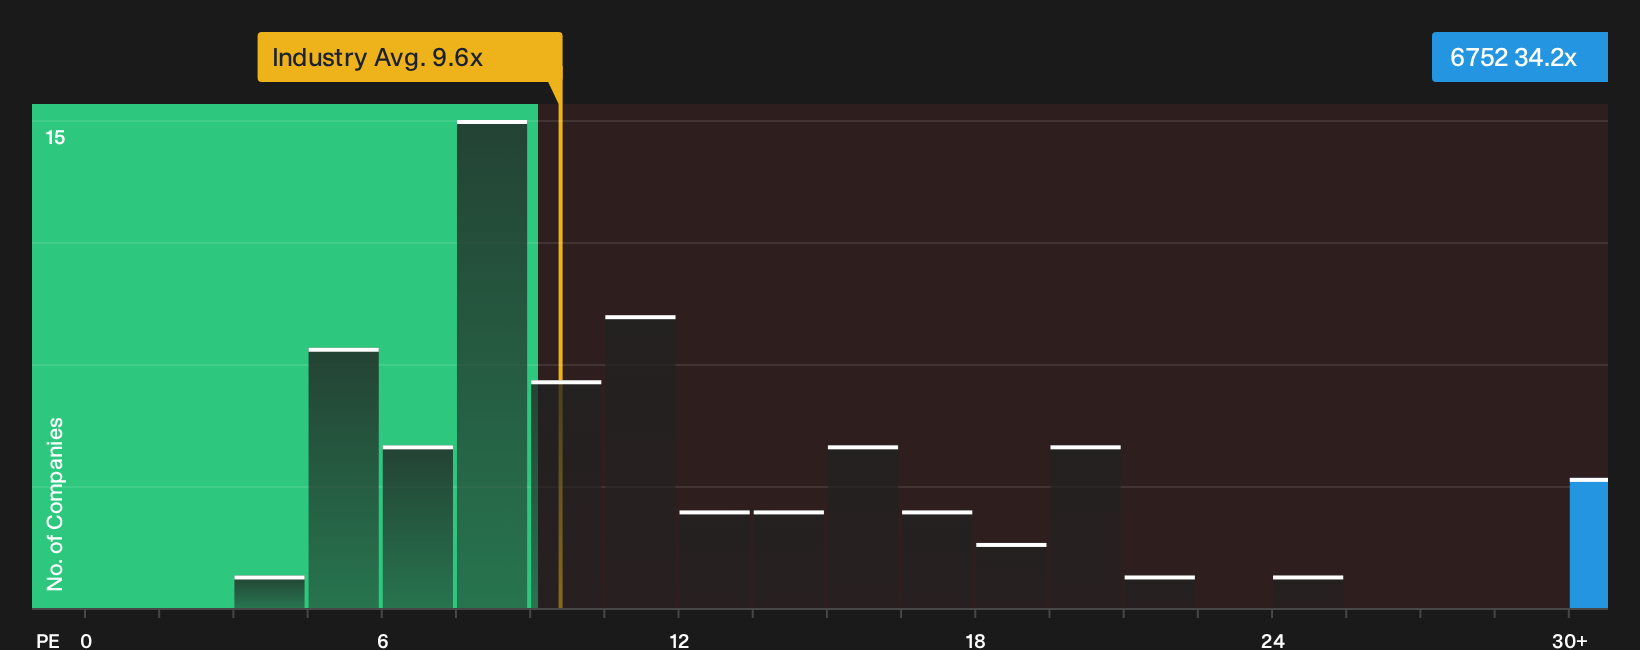
The discounted cash flow work points to Panasonic Holdings trading below an estimated value, yet the market is attaching a rich P/E of 34.2x. That is higher than both the Consumer Durables industry on 9.6x and a fair ratio of 32.6x. This raises the question of whether investors are already paying up for the AI and battery narrative.
See what the numbers say about this price in more detail with our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Panasonic Holdings is clearly mixed, with sharp gains on one side and fresh concerns on the other. Move quickly, test the data against your own risk tolerance and time horizon, then weigh the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Panasonic Holdings?
Do not stop at Panasonic Holdings. Use this pullback as a prompt to refresh your watchlist with fresh, data driven ideas tailored to your own style.
- Target resilient compounding potential by reviewing a 29 dividend fortresses that can help you focus on income opportunities backed by higher yields and balance sheet strength.
- Hunt for mispriced quality by scanning a 72 high quality undiscovered gems that surfaces financially solid opportunities the broader market may not be watching closely yet.
- Dial up defense in uncertain periods by leaning on a 25 resilient stocks with low risk scores that highlights companies with sturdier risk profiles and steadier fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com