


Globe Life (GL) Issued 2026 And 2027 Guidance, Is The Pullback A Valuation Opportunity?
Globe Life (GL) has just paired fresh 2026 and 2027 earnings guidance with its latest quarterly results, giving investors new numbers on premium revenue expectations, earnings power, and segment level sales momentum.
The stock has pulled back, with a 7 day share price return of down 6.6% and a 90 day share price return of down 13.5%. However, the year to date share price return is up 14.4% and the 1 year total shareholder return sits at 21.2%, suggesting earlier momentum has cooled as investors digest the new guidance, recent earnings and the ongoing governance investigation headlines.
Scan how Globe Life’s guidance compares with peers by lining it up beside a curated 32 resilient stocks with low risk scores that have been holding up through recent volatility.
Globe Life now trades at a clear discount to both analyst targets and some intrinsic value estimates. Is that a mispriced payout on updated guidance, or a fair caution premium on governance risk and softer earnings, as the valuation work below explores?
Most Popular Narrative: 16% Undervalued
Globe Life closed at $158.37 while the most followed narrative pegs fair value near $187.82. As a result, the story hinges on whether operational catalysts justify that gap given current sentiment and the governance headlines in play.
The planned establishment of a Bermuda reinsurance affiliate is expected to significantly increase parent company free cash flow and financial flexibility by 2027 and beyond, providing greater capacity for share repurchases and/or strategic investments, positively impacting earnings per share.
Planned deployment of AI applications across administration, underwriting and sales support is aimed at lowering the administrative expense ratio from about 7.3% of premium and lifting agent productivity, which could support higher net margins and net operating income over time.
See why 11 investors see Globe Life as 16% undervalued.
Result: Fair Value of $187.82 (UNDERVALUED)
Still, Globe Life’s reliance on agents as online life sales weaken, along with rising health claims pressure, could quickly flip this undervaluation story on its head.
Find out about the key risks to this Globe Life narrative.
Another View on Globe Life’s Valuation
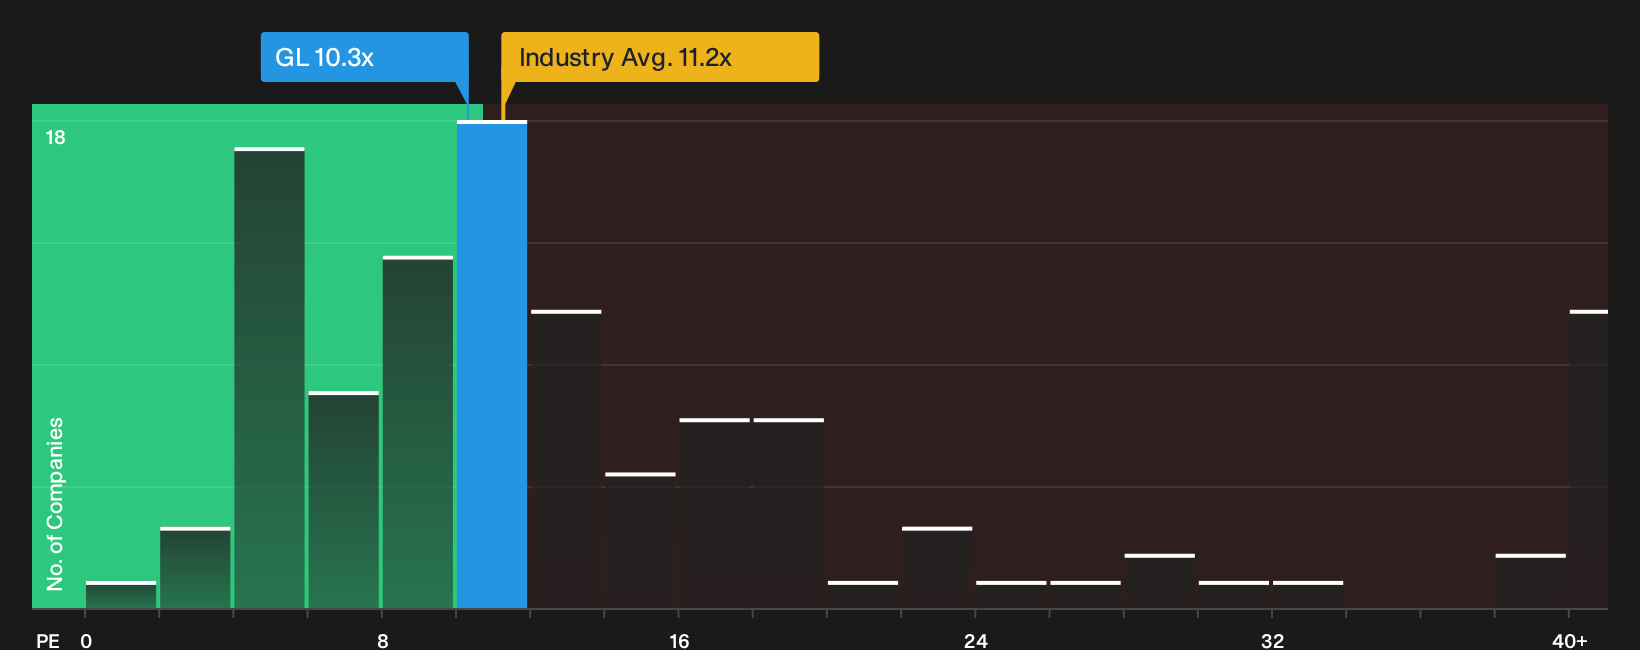
That 16% narrative discount leans on earnings and growth assumptions, yet Globe Life’s current 10.3x P/E sits only a touch above its fair ratio of 10.2x and below the US Insurance average of 11x and peer average of 36.1x. Is this a genuine margin of safety or just a thin valuation cushion if earnings disappoint?
To see how this pricing gap could close in practice, compare Globe Life with companies on a similar footing. Then stress test your own expectations using the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Views on Globe Life are still mixed. If you prefer to base your stance on your own analysis rather than headlines, start by weighing the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Globe Life?
Do not stop your research at Globe Life alone. Broaden your watchlist with a few targeted screens that surface different types of opportunities across the market.
Use these curated stock lists as jumping off points for your own due diligence and avoid leaving potential ideas on the table as conditions shift.
- Target potential mispricing by scanning a curated universe of resilient businesses through the 26 high quality undervalued stocks that may offer a margin between price and fundamentals.
- Strengthen your income watchlist by focusing on dependable payers using the 6 dividend fortresses that highlight companies prioritising meaningful cash returns to shareholders.
- Prioritise financial resilience with a list of solid balance sheet and fundamentals (24 results) that can help you focus on companies carrying manageable debt and robust financial positions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com