


What Ceconomy Stock's CFO Appointment Means For Shareholders
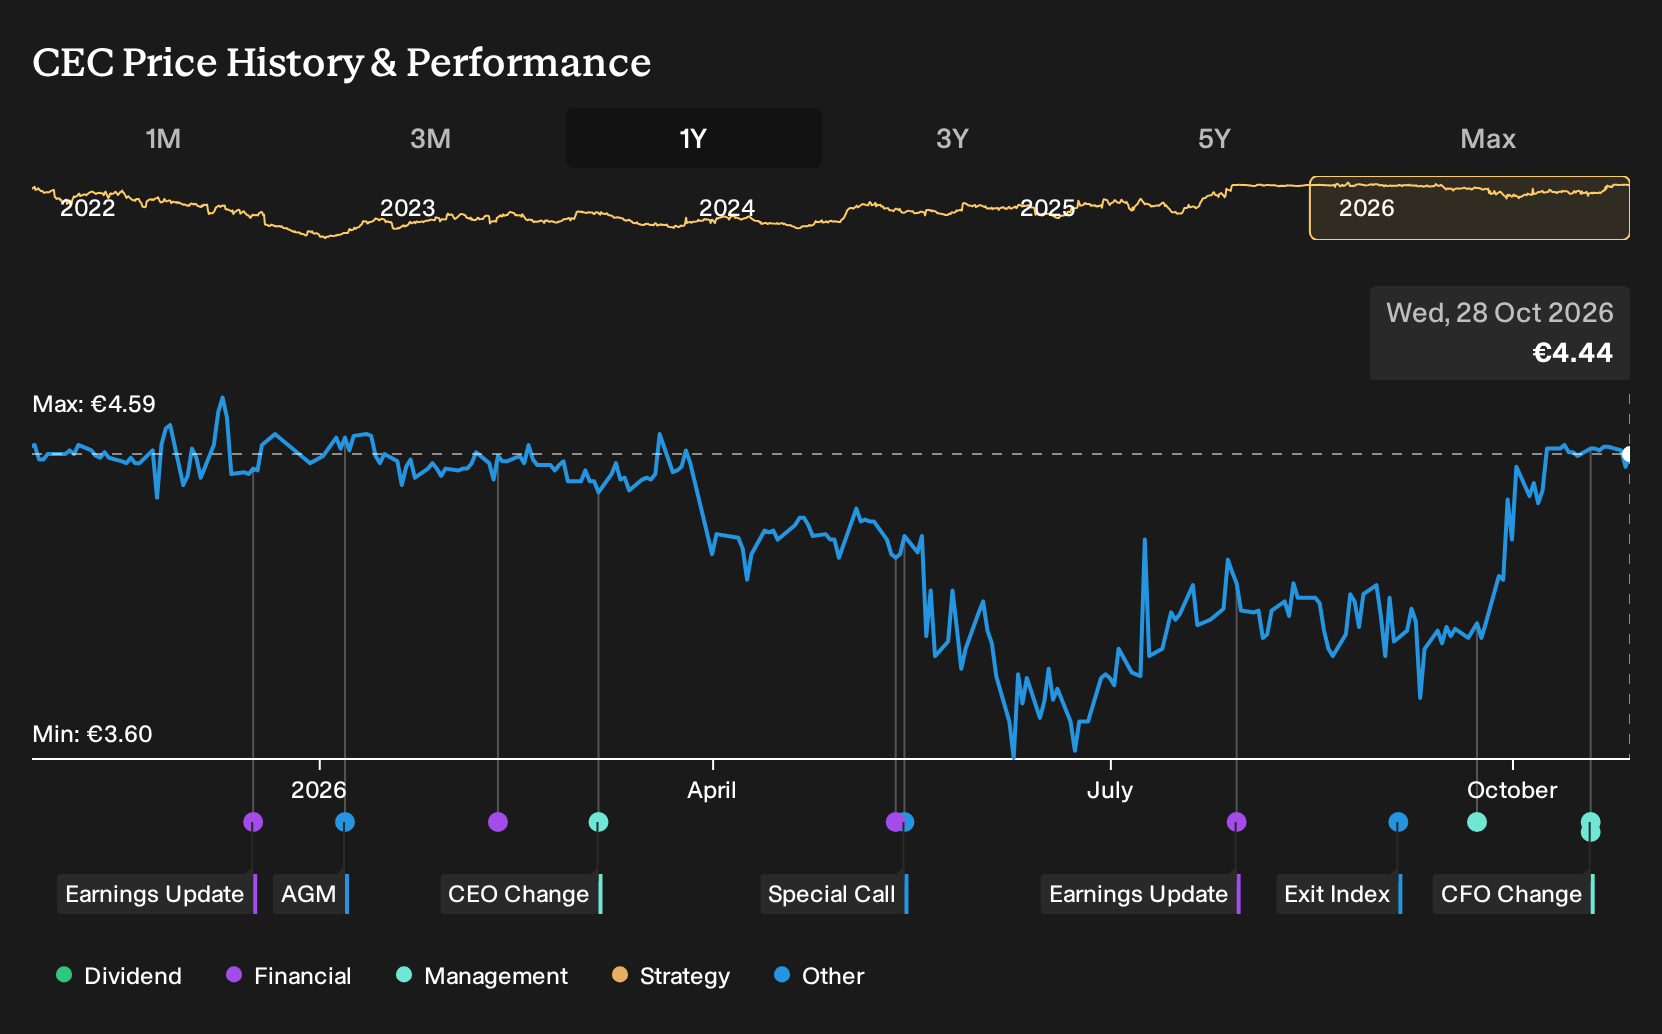
- Ceconomy has appointed Virpy Richter as Chief Financial Officer and Executive Board member, effective 1 January 2027, following Supervisory Board approval.
- Richter’s more than 25 years in senior finance roles at Awin AG and Conrad Electronic Group indicates a focus on seasoned leadership in Ceconomy’s finance division.
- We will look at how Ceconomy’s investment narrative could shift as Virpy Richter takes charge of the finance organisation and board seat.
Scan how other electronics and retail stocks are repositioning their finance leaders by reviewing the hand picked list of solid balance sheet and fundamentals (206 results) alongside Ceconomy’s latest CFO shift.
Ceconomy Investment Narrative Recap
To stay invested in Ceconomy, you need to believe the omnichannel push, services mix shift and marketplace build out can turn a currently loss making retailer with €23,786.0m in sales and a €14.0m loss into a consistently profitable operator. The CFO change itself does not alter that core thesis. In the near term, the key swing factor still looks like execution on store productivity, online conversion and cost control.
The biggest operational risk remains dependence on the planned JD.com partnership while regulators run an in depth review that could delay or derail the deal. Richter’s appointment and the handover from Remko Rijnders do not materially change that risk. They simply set up a clearer split between finance leadership and day to day operational management.
The JD.com process is the announcement that matters most around this CFO move, because it interacts directly with Ceconomy’s main catalysts. Management is aiming to use JD logistics and technology to support higher sales density, more efficient fulfilment and potentially better EBIT over time. Any timing change to that deal would feed straight into how those operational goals are achieved.
Regulatory scrutiny and rival pushback on JD.com’s concessions add uncertainty around margins and economics from the partnership. Your focus as a shareholder is less on the symbolism of a new finance chief and more on whether Ceconomy can keep growing higher margin Services & Solutions, marketplace and retail media activities while managing funding risk and interest coverage during a period of heavy transformation.
Ceconomy's narrative projects €24.8b revenue and €531.9m earnings by 2029, based on analysts assuming 1.4% yearly revenue growth and an earnings swing of about €545.9m from a €14.0m loss today to the forecast profit.
Uncover how Ceconomy's fair value indicates a 4% potential upside to its current price, which could narrow quickly.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Ceconomy research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Ceconomy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ceconomy's overall financial health at a glance.
Looking For More Ideas Beyond Ceconomy?
Once you have a view on Ceconomy, you can widen the lens and test that thesis against other businesses with different balance sheets, earnings profiles and risk levels by using the Simply Wall St Screener.
- For readers who want potential bargains with solid fundamentals, review our hand picked list of 191 high quality undervalued stocks and see how they compare to Ceconomy on quality and pricing.
- If resilience and capital preservation rank higher for you than high octane returns, filter for 229 resilient stocks with low risk scores and measure their stability next to Ceconomy's transformation story.
- To broaden your watchlist beyond the usual tickers, scan 608 high quality undiscovered gems and find lesser known businesses that still show robust financial characteristics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com