


3 Energy Stocks With Rising Production and Cash Return Potential
Shell’s latest quarter put the energy sector back in the spotlight, with US$10.81b in adjusted earnings and record refining margins of US$42 per barrel reminding investors how powerful these integrated oil and gas giants can be when supply stays tight and geopolitics keep markets on edge. Investors who ignore this may miss important clues about where capital is flowing next. This article walks through three stocks from our Integrated Oil & Gas Majors screener that appear especially sensitive to the same forces now shaping Shell’s profits. The goal is to help you decide which stories you want exposure to and which you would rather watch from the sidelines.
The three companies in focus below are just a starting sample, and the full Integrated Oil & Gas Majors screen surfaced 24 more large cap players with equally compelling narratives that are not covered here.
If you want to identify, compare, and analyze which integrated producers best fit your own risk and income profile, head straight to the Integrated Oil & Gas Majors screener.
Parex Resources (TSX:PXT)
Parex Resources plugs into the Integrated Oil & Gas Majors theme as a pure upstream and marketing player, giving you focused Colombian oil exposure rather than a fully diversified refiner. That is exactly why its production plans and capital returns matter so much right now.
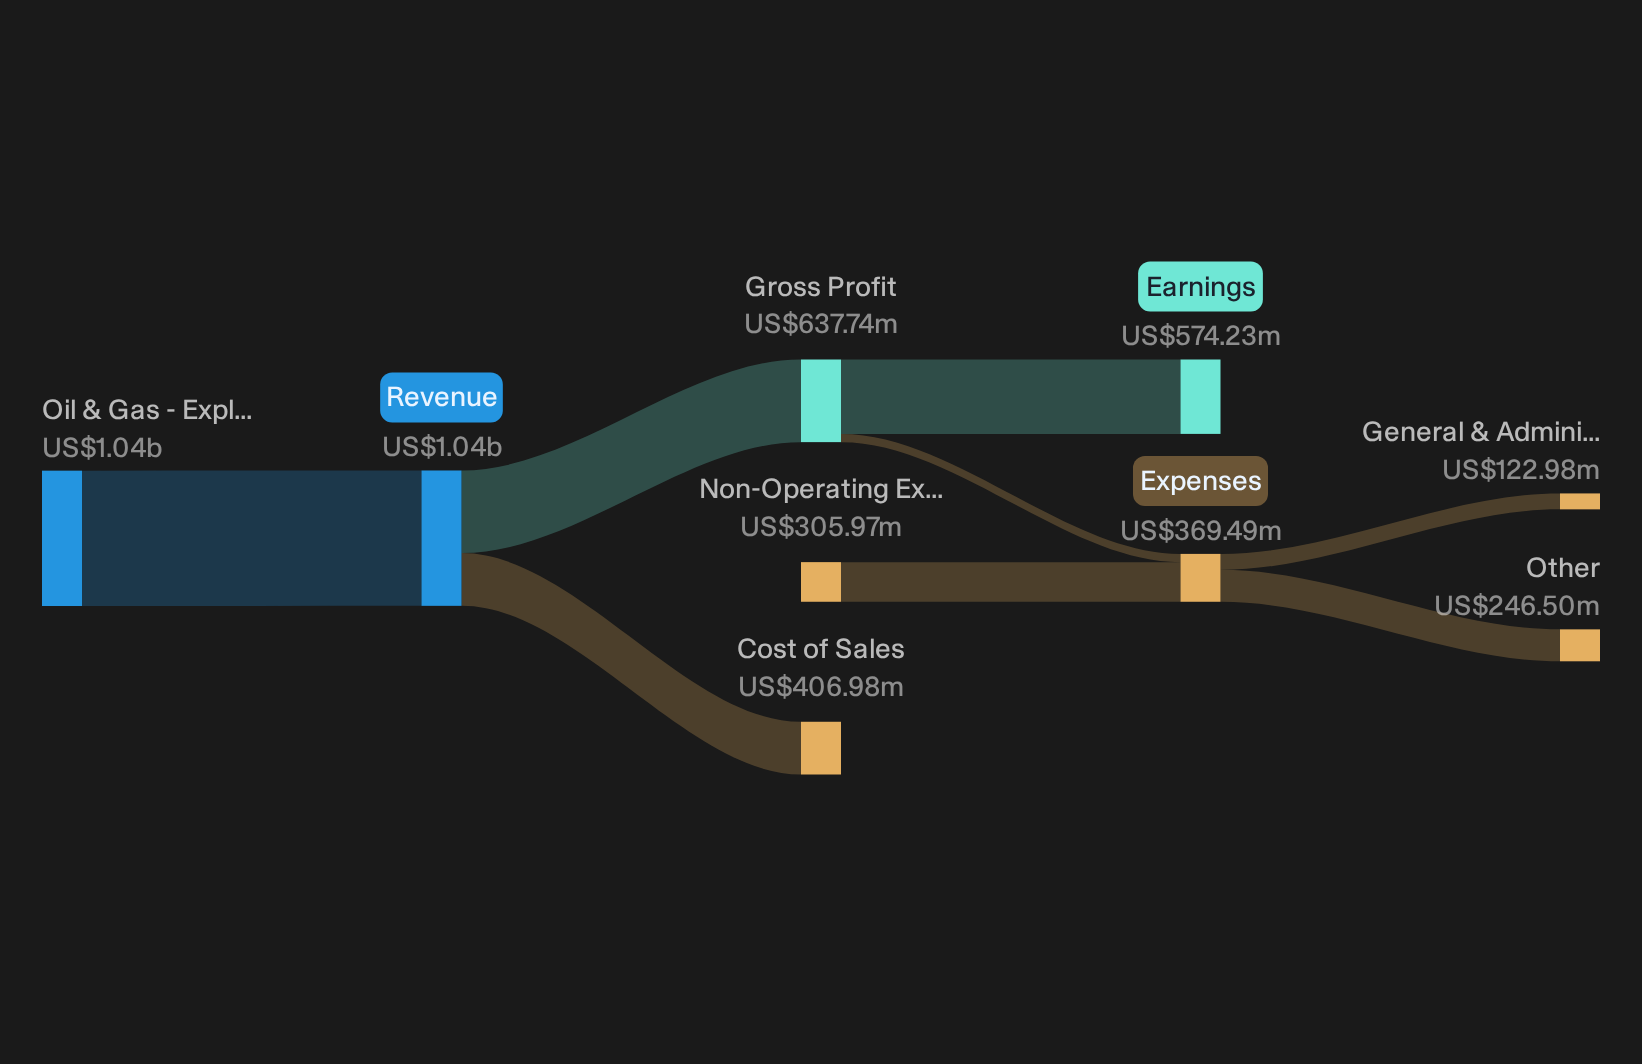
Parex Resources generates about US$1.04b from oil and gas exploration and production, almost entirely from Colombia, and has a market value near CA$2.7b. It offers investors a concentrated, mid sized upstream profile within a large cap leaning majors screen.
Parex Resources is scaling up production capacity after the Frontera acquisition and revised 2026 guidance to 82,000 to 91,000 boe/d for the second half. This increases the volume base that can feed into future revenue and funds flow from operations.
What happens when that bigger production base meets one unresolved pressure on future margins will go a long way to shaping the payoff here.
That margin question is where the real story starts, and the full narrative for Parex Resources outlines how Parex Resources could translate a larger production base into accelerating cash returns or increased downside risk.
Ovintiv (OVV)
Ovintiv fits the Integrated Oil & Gas Majors theme as a large upstream producer, giving you direct exposure to commodity prices through its oil and gas development and marketing across the Permian, Anadarko and Montney plays, with about US$6.0b from USA Operations, US$3.6b from Canadian Operations and a roughly US$19.6b market value.
Where Shell’s quarter highlights the value of scale and capital returns across the integrated chain, Ovintiv offers a purer upstream angle on the same energy story. Its operations are tightly focused on squeezing more from each well rather than owning refineries.
Ongoing efficiency gains in Ovintiv's Permian and Montney programs, including cube development, real time frac optimization, Simul frac, AI driven drilling control, and wet sand, are supporting more than a 10% improvement in oil productivity per foot since 2023 and D&C costs below $600 per foot in the Permian and $500 per foot in the Montney. These gains can feed into stronger net margins and earnings over time.
How that operational edge performs against any persistent pressure on future pricing and cash returns will be important for investors to watch.
That tug of war on future pricing and cash returns is exactly what the full narrative for Ovintiv unpacks in full, including where Ovintiv’s edge could quietly accelerate.

Matador Resources (MTDR)
Matador Resources gives you pure U.S. upstream exposure within the Integrated Oil & Gas Majors theme, with most of its US$3.5b revenue coming from exploration and production and about US$750 million from midstream services, all backed by a roughly US$7.3b market value.
Matador Resources sits in the same energy crosscurrents as the global majors, but it leans on tight Delaware Basin execution and a growing midstream footprint rather than integrated refineries to turn commodity cycles into shareholder returns.
Expanding midstream scale through the Cardinal assets and higher San Mateo and wholly owned midstream EBITDA expected in 2026 increases fee based revenue, supports additional financing options and can lift Matador Resources’ consolidated earnings power.
What happens if one still unresolved pressure on future free cash flow collides with that bigger, fee based backbone will be crucial for investors.
When that pressure on free cash flow finally hits, the full narrative for Matador Resources shows where Matador Resources could be quietly compounding or where risks start masking the upside.

Curious To Explore Alternative Opportunities?
Fresh ideas move first. Stocks with building momentum, early breakout potential, or quietly dropping risk often get caught by screens before headlines. Scan new angles while it matters and get in early.
- Spot resilient cash generators before the crowd by running the list of solid balance sheet and fundamentals (6 results) and filter for businesses where financial strength backs every growth plan.
- Chase high income opportunities with staying power using the 3 dividend fortresses and focus on companies aiming to keep payouts flying while others hesitate.
- Track accelerating infrastructure trends by checking the 43 power grid technology and infrastructure stocks and pinpoint essential players tied to grid upgrades while they are still under the radar for now.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com