


Woori Financial Group Shares Rose Even As Profit Fell
Woori Financial Group just pulled off an awkward mix. Revenue in the latest quarter was higher, yet net income and net margin both went the wrong way. For Woori Financial Group shareholders, the return over the past year was 26.2%, including dividends. If you had been weighing that upside against warnings about margin pressure and credit risk back in October 2025, what exactly were you being paid to believe about this business?
The easy part of this move is behind Woori Financial Group. Zero in on 191 high quality undervalued stocks for companies trading below our estimates.
The Two Stories Investors Had To Choose Between On Woori Financial Group
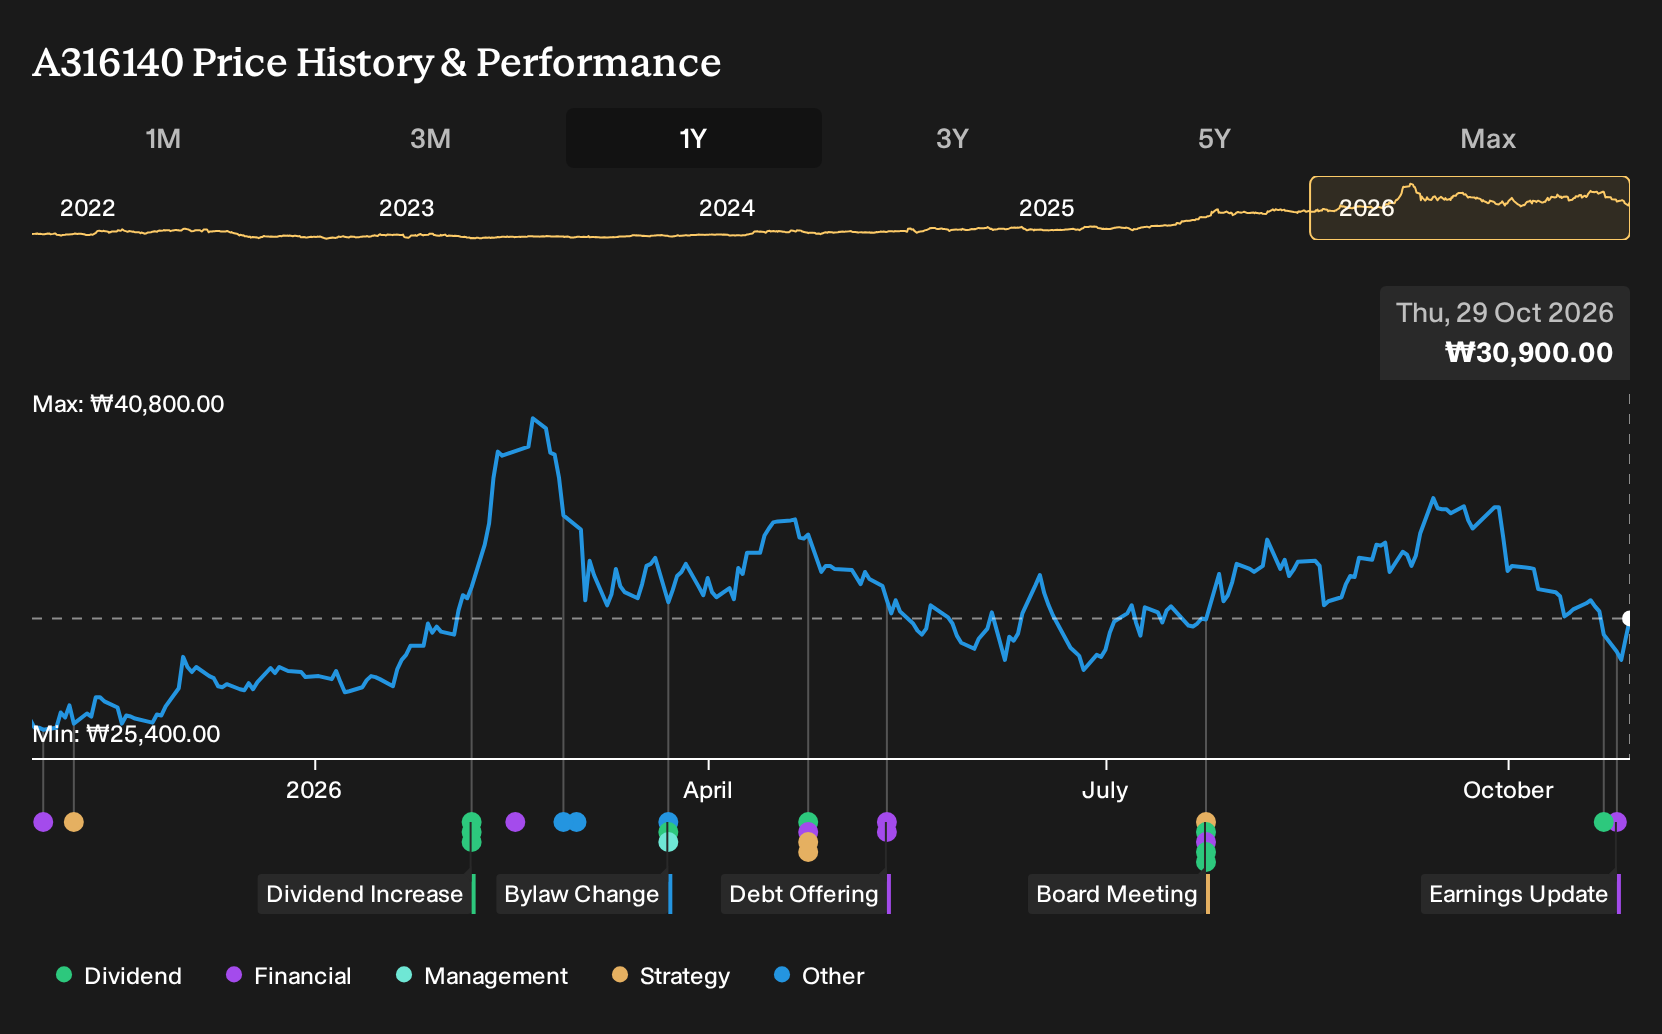
The shares cost ₩25,550 at the start of the period, and anyone buying Woori Financial Group then was really choosing between two very different stories.
The bullish view pointed to a Fair Value of ₩29,095, a level that simply reflected what that camp thought the assumptions implied. This view was built on 4.6% annual revenue growth and profit margins reaching 31.4% through digital expansion and broader insurance and securities income.
The bearish camp anchored on a Fair Value of ₩18,000 and focused on South Korea's aging population, slower lending demand, and pressure on margins as younger customers shifted toward independent digital competitors.
What The Results Changed For Woori Financial Group
The clearest new fact was simple. Woori Financial Group reported Q3 2026 revenue of ₩2,643,000m and net income of ₩1,049,000m, with net margin at 39.7% versus 48.9% a year earlier. Higher sales with weaker profitability leaned toward the cautious case that warned about pressure on returns, so the optimistic margin story was not confirmed.
The takeaway travels well. When a thesis rests on richer profitability, you track reported net margin and earnings, not just top line, and see whether each quarter actually moves those ratios toward the claimed target.
What Woori Financial Group's Price Already Assumes
Today's Woori Financial Group share price is ₩30,900. The selected Narrative sees Fair Value above that level and ties the gap to a bigger role for non bank earnings, stronger capital and continued use of buybacks and dividends.
The core question for anyone paying today's price is whether Woori Financial Group can keep lifting non bank profit contribution while holding the cost to income ratio near current levels.
"Expansion of Woori Financial Group’s non bank businesses, with non interest income reaching KRW 1,063b in H1 2026 and non bank units contributing 22.3% of group net income, points to a more diversified earnings mix that can support revenue stability and smoother earnings over time."
One Narrative disagrees with today's price. → See where this Narrative says Woori Financial Group should trade
Go Straight To The Source
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 31% below our estimate - converts targeted tax-efficient fundraising pipelines into scalable fee-based real asset funds.
- Company 2 - 48% below our estimate - lifts mined grades and restores underground extraction rates to extend reserves and reduce costs.
- Company 3 - 43% below our estimate - scales multi brand electric models and robotics by localising production and broadening sales channels.
Three companies from the same screener. Open every one of the 206 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com