


Citi Says the NAND Shortage Will Last Until 2028. Here’s Why Sandisk Stock Is Still So Cheap.
On October 1, Citi reaffirmed its Buy rating on SanDisk (SNDK) following Micron’s (MU) results showing a 42% quarter-over-quarter increase in NAND revenue and roughly 30% higher prices. Citi forecasts that the NAND industry will remain supply-constrained through 2028. SanDisk’s own results already reveal how quickly market conditions have shifted.
Contracts Built to Outlast the Cycle
SanDisk reported a 372% year-over-year revenue increase to $8.97 billion last quarter, with higher prices contributing two-thirds of the sequential growth. Data center now represents 38% of its bits, compared with 12% a year earlier, reflecting growing AI demand for flash storage.
The risk is that price-led growth can reverse with the cycle. Citi noted that Micron’s supply growth is higher than SanDisk’s mid-teens industry expectation, and it forecasts industry bit shipments growing in the mid-20% range in 2027 and 2028. What stands out is the company’s response. It is responding by locking in demand through 10 multi-year agreements with eight customers. These deals are worth at least $93.9 billion at floor pricing and are supported by $16.5 billion in financial guarantees. Together, they cover more than half of fiscal 2027 bits and approximately two-thirds of fiscal 2028 bits. The floors protect less than current earnings.
A 6.9x Multiple Prices In a Downturn
SanDisk trades at a forward P/E of just 6.9x, roughly 68% below the sector median of 21.72x. This discount likely reflects fears that current memory earnings are close to their cyclical peak. Analysts forecast a 203% jump in EPS this fiscal year, followed by slower growth of 23.96% in fiscal 2028 and a 3.58% decline in fiscal 2029. Investors are typically reluctant to pay a premium for earnings they believe are near a cyclical peak.
In my view, the stock looks undervalued if its contracts remain intact. The CFO expects attractive margins even at floor pricing, with contract margins around 80%. The company also has $4.76 billion in cash, almost no debt, and a $15.5 billion buyback authorization.
If its contracts protect margins, I believe SanDisk is trading below a reasonable valuation for a five-year investment.
About SanDisk Stock
Headquartered in Milpitas, California, SanDisk is a leading global provider of NAND flash memory solutions. The company designs and manufactures SSDs, memory cards, and embedded storage used in consumer electronics, enterprise systems, and data centers. With a market capitalization of $207.6 billion, SanDisk plays a key role in modern digital infrastructure. It benefits from strong demand driven by AI, cloud computing, and big data, where hyperscalers increasingly rely on high-performance, scalable storage to support growing data workloads and advanced computing needs.
Shares of the memory chip maker have delivered a dramatic performance over the past 52 weeks, up 4,043%. In fact, in 2026, SNDK stock has surged 601%, making it one of the standout momentum names in the broader market. In contrast, the iShares Semiconductor ETF (SOXX) was only up 57% over the same period.
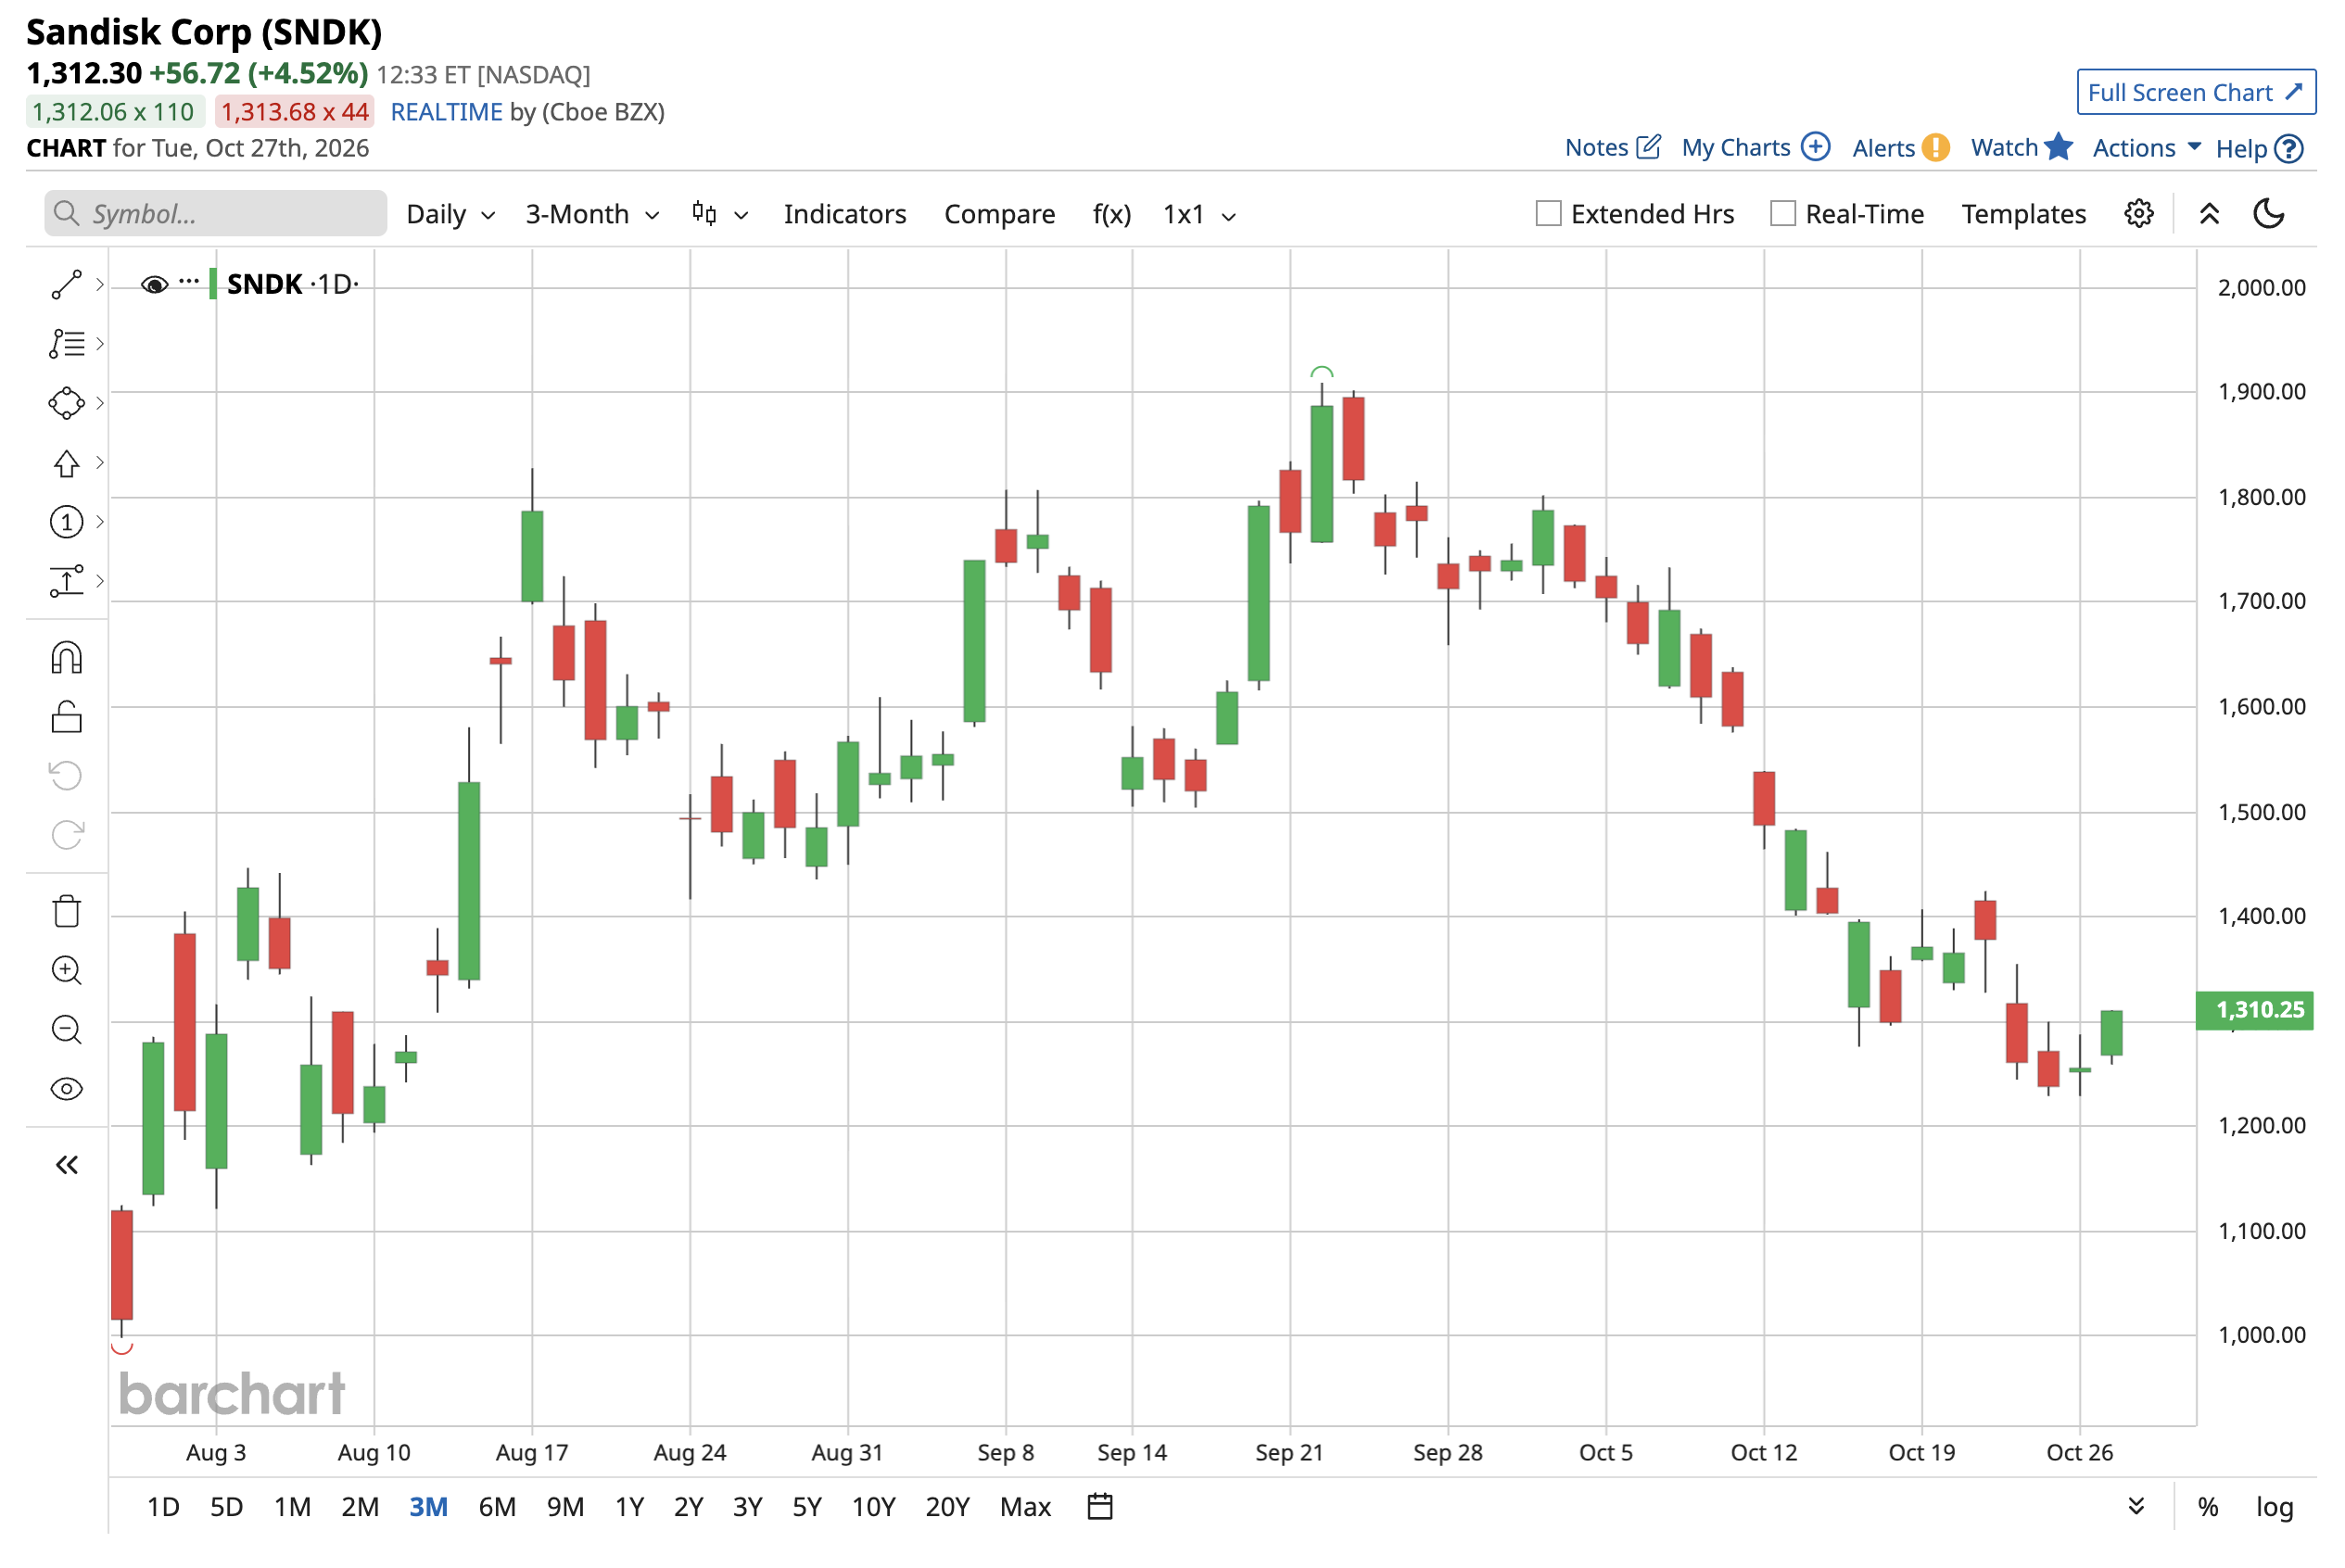
SanDisk Forecasts Another Quarter of Strong Growth
SanDisk reported its fourth-quarter fiscal 2026 earnings on August 4, with revenue of $8.97 billion, up 51% from the prior quarter and 372% year-over-year (YOY). Management said this strong result came from increased sales and better prices, thanks to a healthy market for NAND products. Data-center demand played a key role. SanDisk reported $2.98 billion in data-center revenue for the quarter, up 103% sequentially. For fiscal 2026, revenue stood at $20.25 billion, a 175% YOY increase driven by data-center revenue growth of 437%. These numbers highlight how quickly the company has gained from the rising need for storage infrastructure.
Looking forward, SNDK guided revenue between $10.3 billion and $10.8 billion for the first quarter of fiscal 2027. Non-GAAP gross margin is expected to be between 83% and 85%. CFO Visoso said the company expects non-GAAP EPS between $44 and $46. NAND market is expected to exceed $300 billion in revenue in calendar year 2026 and approach $500 billion in revenue in calendar year 2027. CFO Visoso said demand from customers is growing faster than the company’s supply.
What Do Analysts Expect for SNDK Stock?
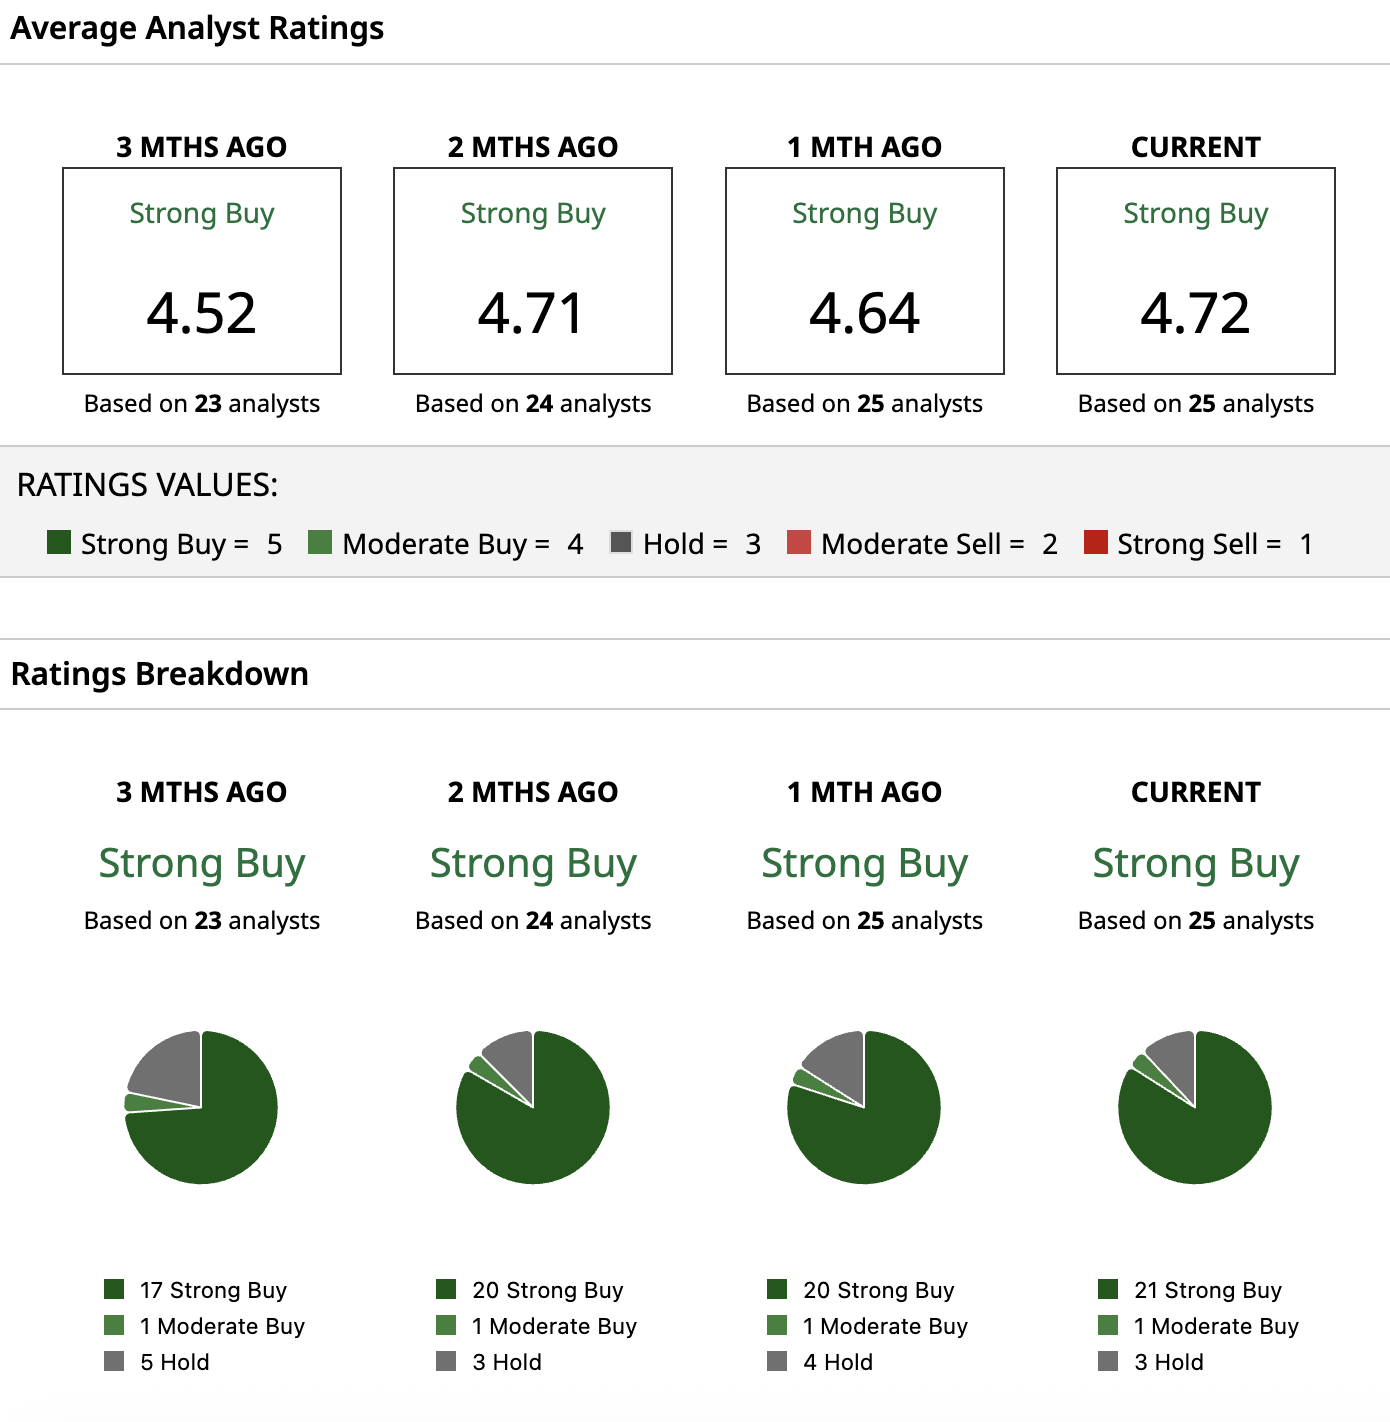
On Wall Street, SNDK stock has a consensus “Strong Buy” rating overall. Of the 25 analysts covering the stock, 21 recommend a “Strong Buy,” one analyst has a “Moderate Buy,” and three suggest a “Hold” rating. The average price target of $2,154.17 suggests potential upside of around 74% from current levels, while the Street-high estimate of $3,000 indicates SNDK stock could gain as much as 142% this year.
On the date of publication, Jabran Kundi did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.