


Joby Aviation (JOBY) Could Be 72% Undervalued As ARK Buys And 2026 Outlook Rises
Cathie Wood’s ARK Investment Management added Joby Aviation (JOBY) shares for a second straight day after the air mobility firm lifted its 2026 revenue outlook due to expected Blade helicopter demand and commercial flight progress.
Joby Aviation’s recent news arrives after a volatile run, with the share price up 1.40% over the last day and 9.48% over the past week, yet down 16.86% over 30 days and 29.83% over 90 days. At a US$5.08 share price, the year to date share price return has declined 64.62%, while the 1 year total shareholder return has fallen 70.17%. This suggests that the latest buying interest and upgraded 2026 outlook are being weighed against earlier concerns about execution risk and commercialization timing.
Scan how Joby Aviation compares with other high-transportation bets by reviewing a hand-picked 19 high quality undiscovered gems that investors are not widely focused on yet.
Bulls view Joby Aviation’s raised 2026 outlook and ARK’s recent buying as indications that the worst may be over, while bears highlight the company’s steep losses and sharp share price decline. The key question now is which narrative the valuation will support next.
Most Popular Narrative: 72% Undervalued
Compared with Joby Aviation’s last close of $5.08, the most followed narrative anchors on a Fair Value of $18, which frames today’s price as heavily discounted and puts the focus firmly on what needs to go right operationally.
The combination of around US$2.3b in cash and guided second half cash use focused on certification, eIPP operations and commercialization gives Joby Aviation room to fund additional programs such as new routes or service models that are not yet reflected in current revenue or earnings expectations.
See why 16 investors see Joby Aviation as 72% undervalued.
Result: Fair Value of $18 (UNDERVALUED)
Still, the bullish Joby Aviation story runs into two hard constraints: heavy 2026 cash use guidance and an adverse US$116.9 million legal verdict that could tighten funding options.
Find out about the key risks to this Joby Aviation narrative.
Another View: Joby Aviation Looks Expensive On Sales
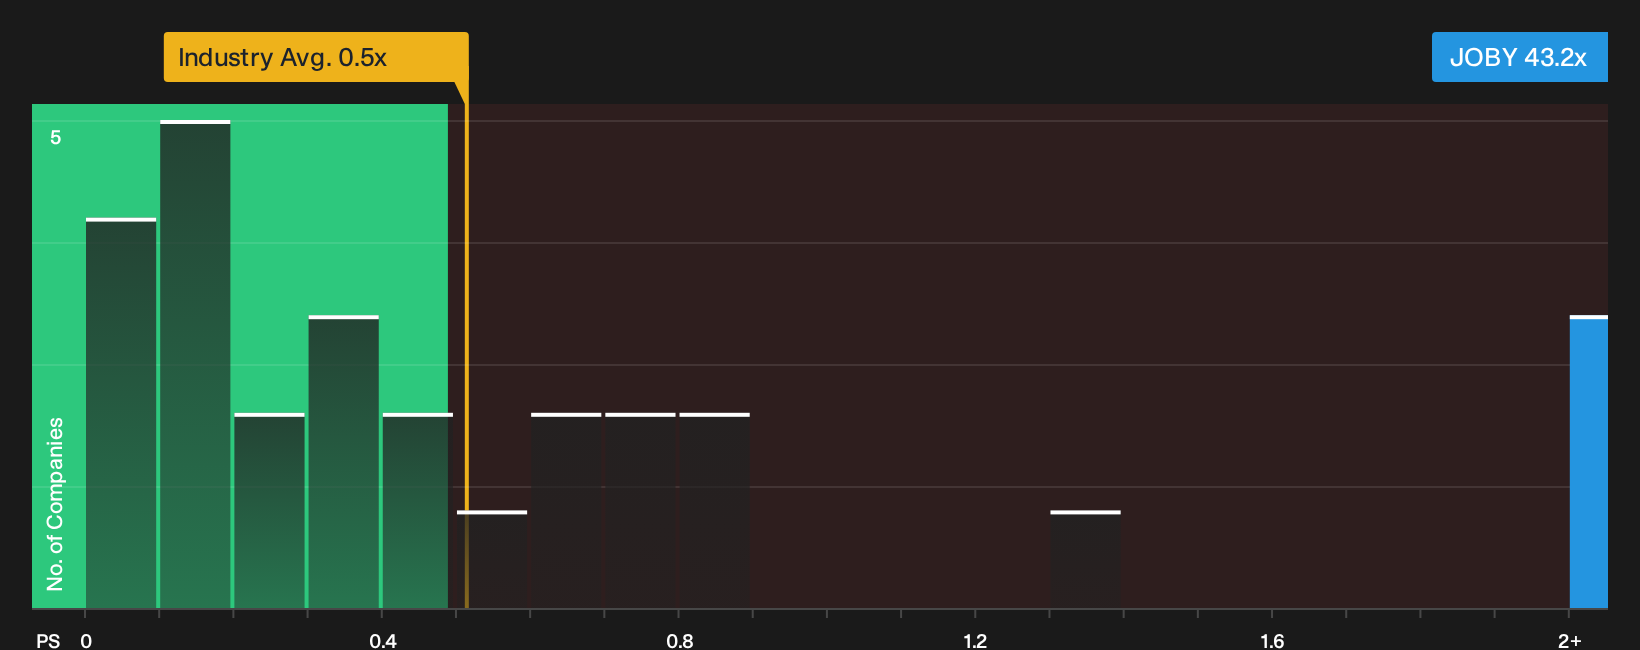
The story shifts when the lens moves from fair value estimates to simple sales based pricing. Joby Aviation trades on a P/S ratio of 43.2x, compared with a peer average of 0.7x, a global airlines average of 0.5x, and a fair ratio of 2.7x that the market could eventually gravitate toward. That gap points to valuation risk if sentiment cools or revenue falls short, so the open question is whether investors are being paid enough for that kind of stretch.
To see how this sales based view lines up with the wider valuation work, take a closer look at our breakdown, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and concern feels familiar, consider acting while the facts are fresh and pressure test Joby Aviation against your own framework using 1 key reward and 1 important warning sign.
Looking For More Ideas Beyond Joby Aviation?
Do not stop with a single high conviction story. Use the Simply Wall St screener to compare different return profiles, risk levels, and income potential while the Joby Aviation thesis is front of mind.
- Target higher upside potential by reviewing a curated set of 9 elite penny stocks with strong financials that meet tighter financial quality checks than most early stage bets.
- Focus on value first and stress test your thesis against a wider pool of 26 high quality undervalued stocks selected for both quality and pricing support.
- Prioritise resilience by lining up Joby Aviation alongside 32 resilient stocks with low risk scores that pair sturdier balance sheets with more measured risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com