


TJX Companies (TJX) Is Back In Focus, But What Is Driving The Attention?
TJX Companies (TJX) is back in focus after a planned leadership transition, as long-time Senior Executive Vice President and Group President Kenneth Canestrari moves toward retirement under an updated employment agreement.
Recent trading tells a mixed story for TJX Companies. The share price has eased over the past week and quarter, with a 7 day share price return down 4.9% and a 90 day move lower by 13.1%, even after a 30 day share price gain of 6.3% and a last close of US$138.39. At the same time, total shareholder return over 3 and 5 years, at 63.4% and 117.4%, points to a much stronger longer term experience. The recent pullback suggests momentum has cooled as investors reassess expectations around the upcoming earnings update and the broader leadership transition.
Spot under-the-radar retailers facing similar leadership and momentum shifts by scanning our curated 19 high quality undiscovered gems that aligns with stories like TJX Companies today.TJX Companies now trades below both its recent peak and the average analyst target, yet above one intrinsic value estimate. Where does a reasonable fair value range really land once those reference points are lined up side by side?
Most Popular Narrative: 18% Undervalued
TJX Companies closed at $138.39, while the most followed narrative anchors a fair value around $169.80. The gap hinges on how durable the growth and margin drivers really are.
Management’s plan to lift long-term store potential to 7,500 locations worldwide and accelerate unit growth to 4% a year adds a concrete expansion path that can widen TJX Companies’ off price footprint and support higher consolidated revenue and earnings over time. The structurally strong home oriented banners, with HomeGoods posting high single digit comps and several hundred basis points of segment margin expansion in recent quarters, point to a larger role for home in the mix that can support company wide net margins and earnings.
See why 68 investors see TJX Companies as 18% undervalued.
Result: Fair Value of $169.80 (UNDERVALUED)
Still, the bullish TJX Companies story hinges on smoother Marmaxx execution and some relief on fuel and freight costs that management already flags as margin headwinds.
Find out about the key risks to this TJX Companies narrative.
Another View: What TJX Companies’ P/E Is Telling You
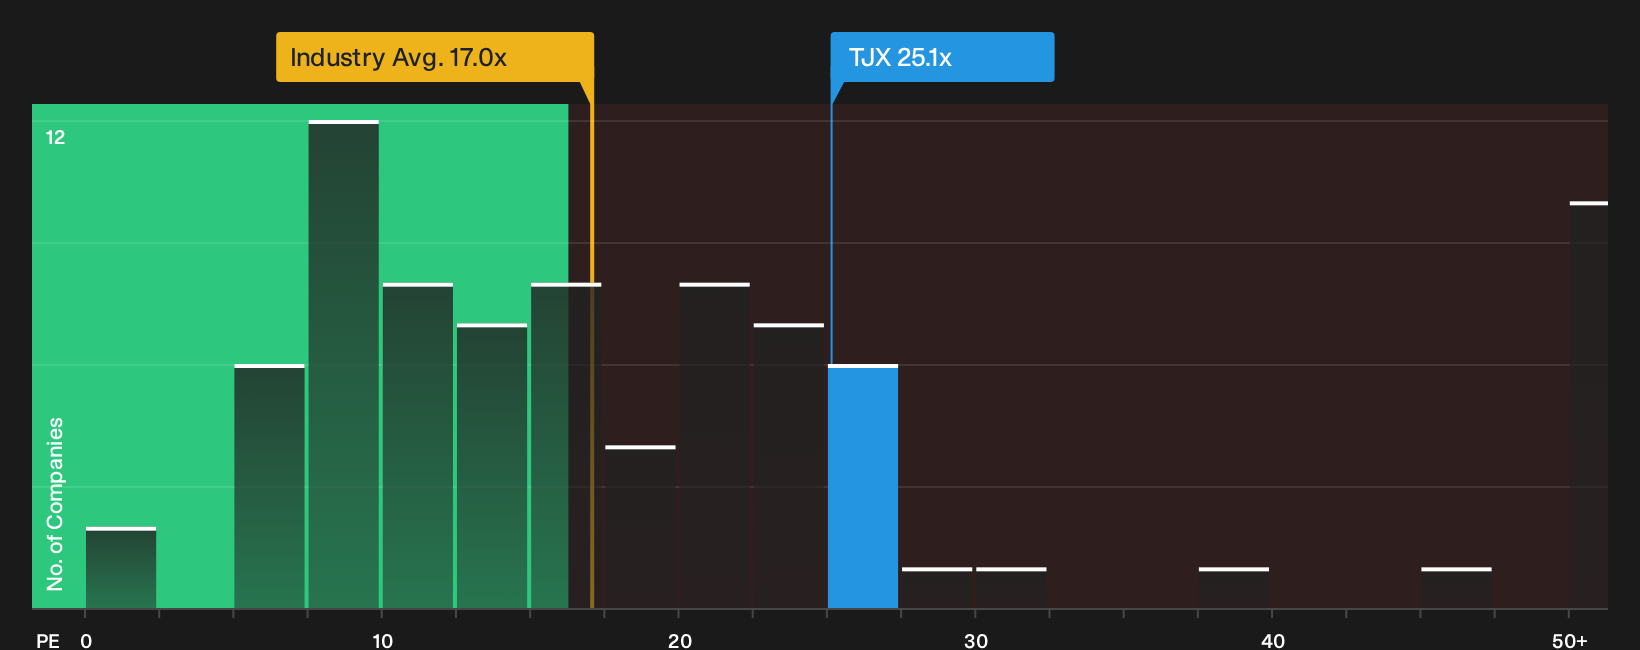
TJX Companies screens very differently once you shift from narrative fair value to simple P/E math. The stock trades at 25.1x earnings against a fair ratio of 19.3x, while the US Specialty Retail group sits near 17x and peers average 16.9x. That richer multiple raises a basic question for investors: Is the extra price you pay today fully backed by the future you believe in?
For anyone weighing that question, valuation ratios can be a useful second opinion on what the market is already pricing in for TJX compared with other retailers, and whether the gap to the fair ratio hints at extra risk if sentiment cools. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and concern around TJX Companies feels familiar, act promptly, review the underlying data, and weigh both sides for yourself with 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond TJX Companies?
Do not stop at TJX Companies. Use the Simply Wall Street Screener to spot fresh opportunities that match your risk tolerance, income needs, and value focus.
- Target potential mispricings by reviewing a curated 26 high quality undervalued stocks that surfaces companies combining quality fundamentals with cautious market expectations.
- Strengthen the income side of your portfolio by scanning a focused group of 6 dividend fortresses built around reliable payout histories and yield.
- Prioritise resilience first and return second by filtering for 32 resilient stocks with low risk scores that aim to keep balance sheets and volatility in check.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com