


Ulta Beauty (ULTA) Stock Looks Pricey After A 63% Run
Ulta Beauty has rewarded long term shareholders, and the current US$619.24 share price puts a spotlight on one key issue for new money coming in. The question is whether that price still lines up with what the retailer is earning today.
- Over the past 3 years the stock has returned 62.8%, which puts real pressure on the earnings story to carry more of the load from here.
- The launch of Ulta Beauty's ChatGPT powered shopping plugin may support expectations for higher spending per customer, which can matter a lot for how investors frame future profit potential.
- There is a second opinion on Ulta Beauty worth weighing. See what analysts think Ulta Beauty's shares could be worth.
The stock's next move may depend on whether Ulta Beauty's current earnings are strong enough to support this price tag.
If you want to stress test Ulta Beauty's earnings story against a broader set of AI exposed retailers, compare it with 36 AI small caps.
Does Ulta Beauty Look Pricey on Earnings?
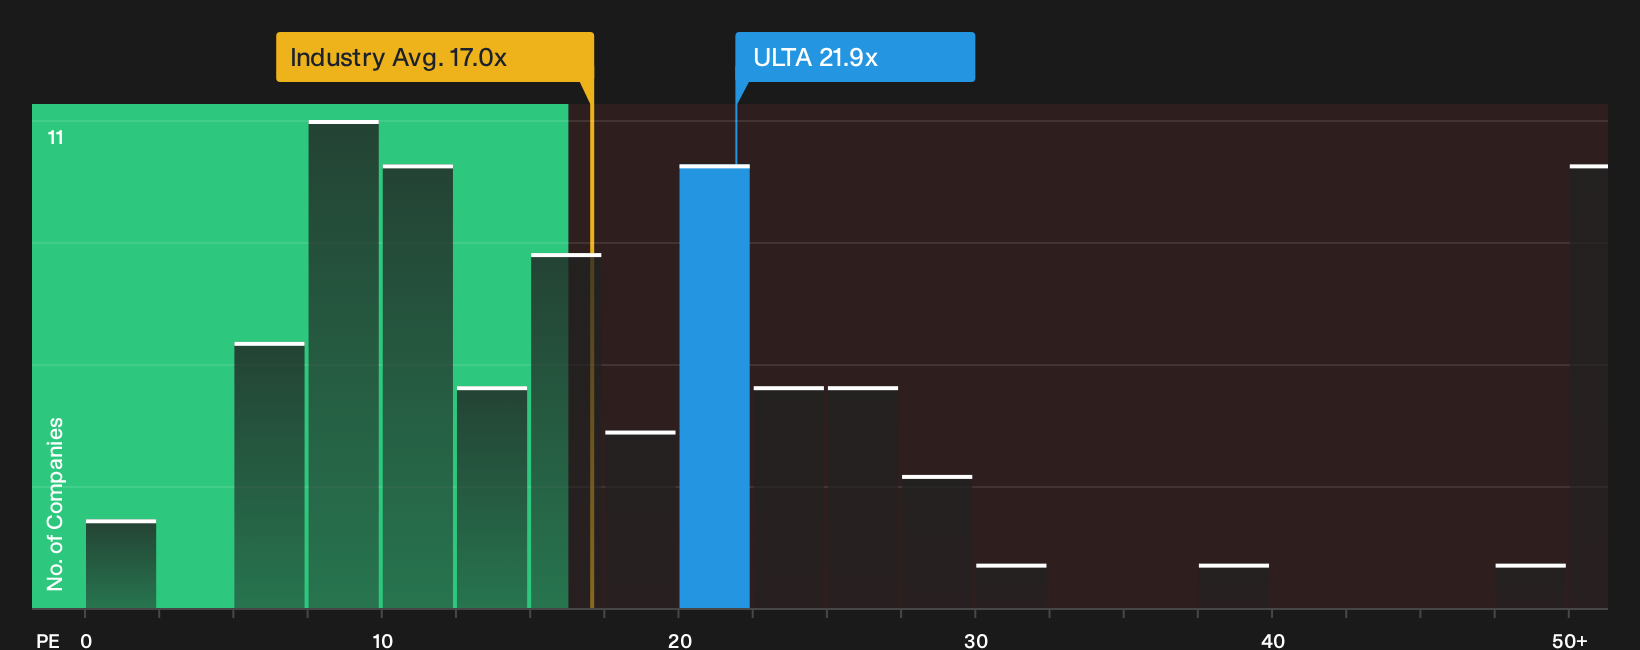
The P/E ratio fits Ulta Beauty well because earnings remain a key anchor for how investors frame this retailer. At roughly 21.9x, the current P/E sits above the Specialty Retail industry average of about 17.0x and also above peers near 20.6x. That points to the market assigning a richer tag to each dollar of profit than the typical competitor in this corner of retail.
The tailored fair P/E implied by the valuation work is lower than where Ulta Beauty trades today, so the stock screens as overvalued on this metric. The recent launch of Ulta Beauty's ChatGPT powered shopping plugin may be feeding optimism into that premium, since it ties the story more tightly to AI driven spending per customer. For anyone weighing an entry point, the current P/E suggests expectations already bake in a lot of good news, which raises the bar for future earnings to keep justifying this kind of multiple. Explore the numbers behind Ulta Beauty's P/E valuation.
The Ulta Beauty Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Ulta Beauty's valuation debate leaves off by spelling out which growth, margin and earnings paths would need to play out for the stock to be worth materially more or less than the current price, and they sit on the Community page. Rather than one headline multiple or single model output, each narrative lays out its own fair value assumptions so you can later compare those inputs with Ulta Beauty's reported results.
Ulta Beauty attracts two very different readings from the community, with one camp seeing more long term firepower in the model than the other.
Bull case: roughly fairly valued
"The loyalty and data ecosystem, with about 47 million active members and 95% of sales coming through the program, is being leveraged into more granular personalization, AI powered search and an Ulta AI shopping agent..."
Discover why this Narrative puts Ulta Beauty at roughly fairly valued.
Bear case: 23% overvalued
"Ulta’s growing use of technology such as license-plate reader tools to combat retail crime has already triggered privacy concerns, which introduces a reputational overhang that could increase compliance and legal costs or dampen member engagement and ultimately weigh on net margins and earnings quality..."
Explore why this Narrative puts Ulta Beauty at 23% overvalued.
One more Ulta Beauty check that sits alongside the share price
Before moving on from Ulta Beauty, it helps to look at who is actually steering the business and how their rewards line up with your interests. See who runs Ulta Beauty and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com