


What Comes Next For Aya Gold & Silver After A 140% Gain
If you had been weighing Aya Gold & Silver in late October 2025, the debate was already sharp. For Aya Gold & Silver shareholders, the return over the past year was 139.7%, including dividends. That kind of move naturally invites a rewind. If you were sitting on cash back then, what would you have focused on more: the claims around Zgounder and Boumadine as potential silver projects, or the warnings about ore dilution and Moroccan risk concentration?
The move put Aya Gold & Silver in the middle of this trade. Scan 10 top silver producer stocks for other companies exposed to it.
The Two Stories Aya Gold & Silver Investors Were Arguing About
The shares cost CA$14.34 at the start of the period, and Aya Gold & Silver sat between two very different stories about what came next.
The bullish script saw Zgounder ramp-up and Boumadine exploration as the key, with a Fair Value of CA$19.71, essentially the price that scenario’s assumptions implied. That view leaned on processing running above nameplate, recoveries near 92%, and expectations for multi-year reserve and production growth.
The bearish side anchored around a Fair Value of CA$12.57 and treated ore dilution and Moroccan concentration as core hazards. That narrative highlighted persistent grade dilution, heavy reliance on a single country, and the risk that higher costs and regulatory shifts could squeeze future margins.
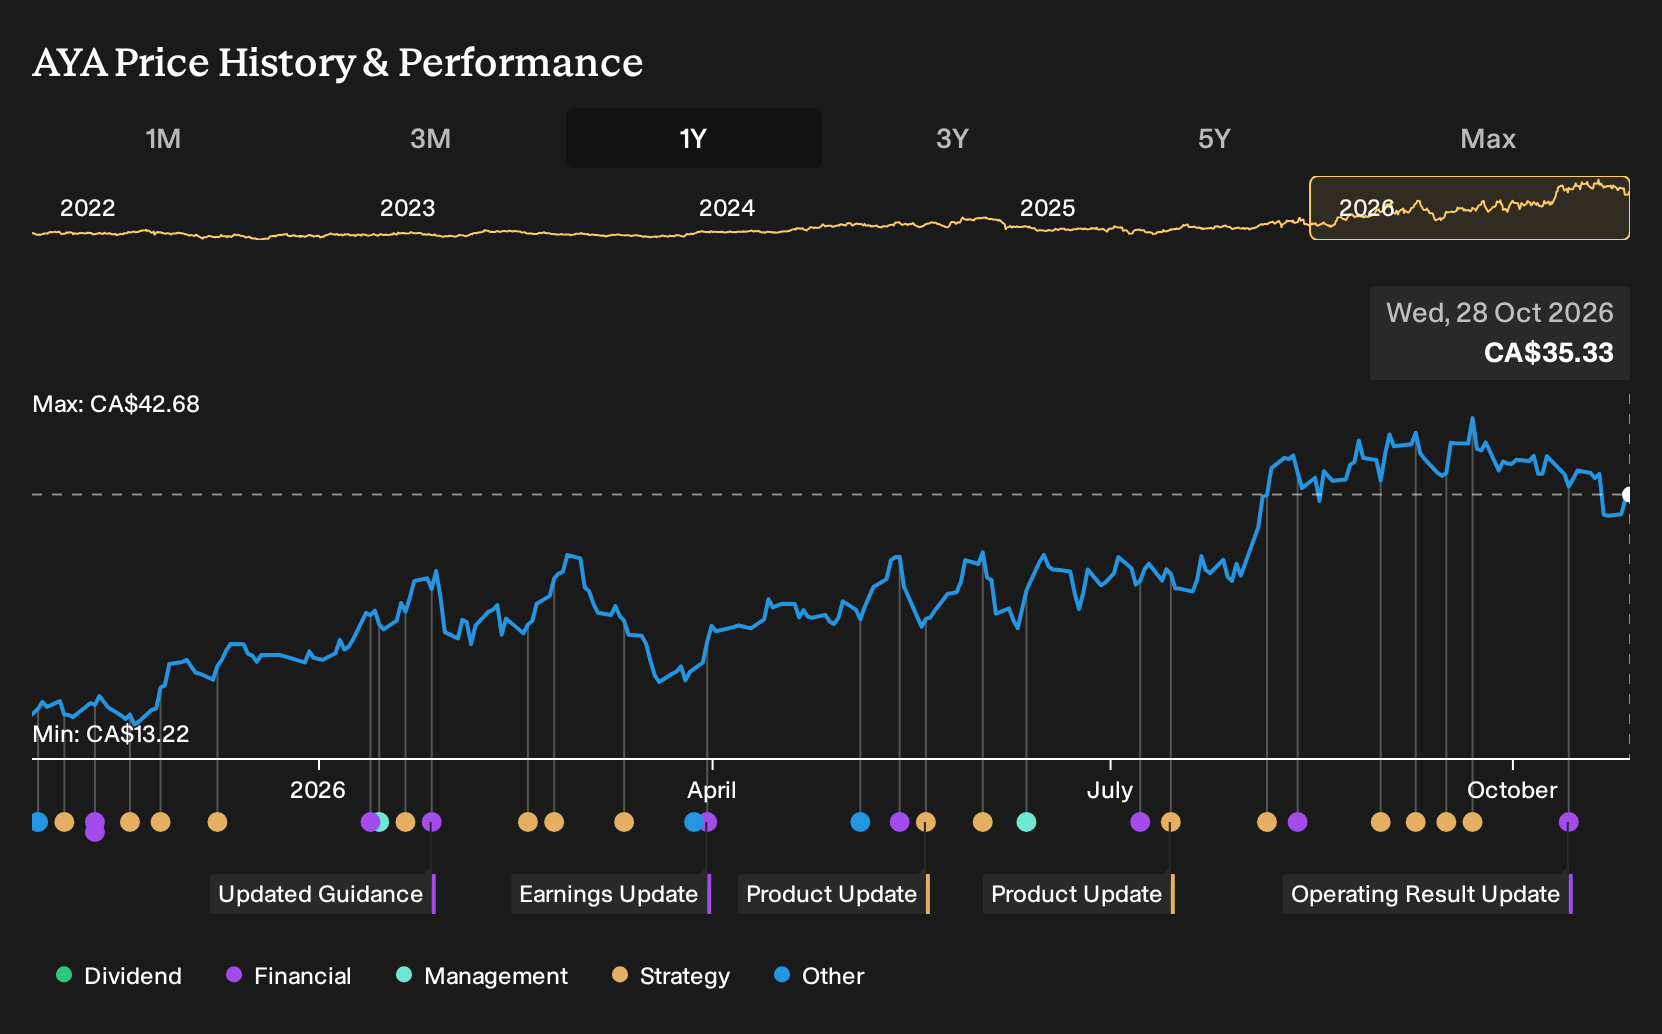
What The Results Changed In The Aya Gold & Silver Debate
The updated Boumadine PEA for Aya Gold & Silver, with an after tax NPV of US$3.5b, longer mine life, and a 93% IRR, leaned toward the optimistic Zgounder plus Boumadine story. Record Q2 2026 revenue of US$96.794m and net income of US$34.588m, with net margin rising to 35.7%, reinforced that side.
The lesson is simple. When a mining pitch hinges on new projects and margin expansion, treat each PEA update and quarterly net margin as the key reality checks to track at any similar producer.
What Aya Gold & Silver’s Run Now Asks You To Believe
Today Aya Gold & Silver trades at CA$35.33, with this Narrative’s Fair Value sitting above that level on its own numbers. The focus is squarely on whether Zgounder cash flow can genuinely underpin a broader Moroccan portfolio rather than a single mine story.
The central question for a buyer now is whether Boumadine truly transitions Aya Gold & Silver into a durable multi asset producer while a high Moroccan tax load remains manageable.
"Key Takeaways: Analysts expect Aya Gold & Silver to continue scaling from the current Zgounder centered operation toward a multi asset mid tier producer as Boumadine advances and district drilling in Morocco continues. The main requirement is that Aya Gold & Silver converts the strong Boumadine study metrics and expanding Moroccan land position into sustained, economically viable production while managing the high Moroccan tax burden."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Aya Gold & Silver And Another Angle
Aya Gold & Silver is a pure precious metals story with clear focus. You could also look sideways at another materials problem.
Clean energy hardware does not just need silver; powerful motors and generators rely on specialised magnetic materials.
One producer is working on a closed loop for those magnets, mining rare earths, processing them and developing recycling capacity.
Government contracts and tech customers use this to secure supply they can trace over time.
The open question is whether that traceable security layer ultimately matters more than the ore.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 72% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com