


UK Stock Market Today: FTSE 100 Futures Slip On Reaccelerating Shop Price Inflation
The Morning Bull - UK Market Morning Update Thursday, 29 Oct 2026
UK stocks look set for a softer open, with sentiment dominated by a fresh inflation warning from the High Street. The key issue is simple: shop prices are rising faster again, just as investors were leaning on a cooling inflation story.
UK shop price inflation reached 2.1% year on year in October, compared with 1.4% in September. Food prices rose 2.9%, while non food inflation registered 1.7%. This combination points to broader price pressure, not just isolated items at the checkout.
When price growth re-accelerates, investors tend to reassess interest rate expectations. Higher inflation can keep borrowing costs elevated for longer, which usually weighs on profit expectations for debt heavy businesses and squeezes disposable income sensitive sectors.
The unresolved question now is how the Bank of England reacts as budget announcements approach. If shop price data feeds into a tougher policy stance, the current cautious mood could harden; a softer tone would instead reopen the debate on rate relief.
Stocks to Watch Before the Opening Bell
Rolls-Royce Holdings (RR.)
The UK government has pledged up to £1.25b to Rolls-Royce for its UltraFan short haul jet engine programme, alongside the group’s own £2.5b decade long investment plan. The project targets around 3,300 UK jobs by 2029. Watch how management phases spending and updates on certification, since timelines can affect cash needs and partnership terms.
Rio Tinto Group (RIO)
Rio Tinto has inaugurated its Fénix 1B and Sal de Vida lithium projects in Argentina after around US$1.4b of investment. Both sites have started output ahead of plan and are scaling toward 25,000 tonnes of lithium carbonate equivalent capacity. The World Bank’s higher copper price outlook also keeps attention on Rio’s exposure to energy transition metals and future capital allocation.
HUTCHMED (China) (HCM)
HUTCHMED has received US FDA Orphan Drug Designation for sovleplenib in primary immune thrombocytopenia, which brings potential US incentives including 7 years of market exclusivity if approved. New Drug Applications for sovleplenib in primary ITP and warm antibody autoimmune hemolytic anemia are under review in China. Investors will focus on regulatory timetables and any partnership news around this asset.
Top Movers
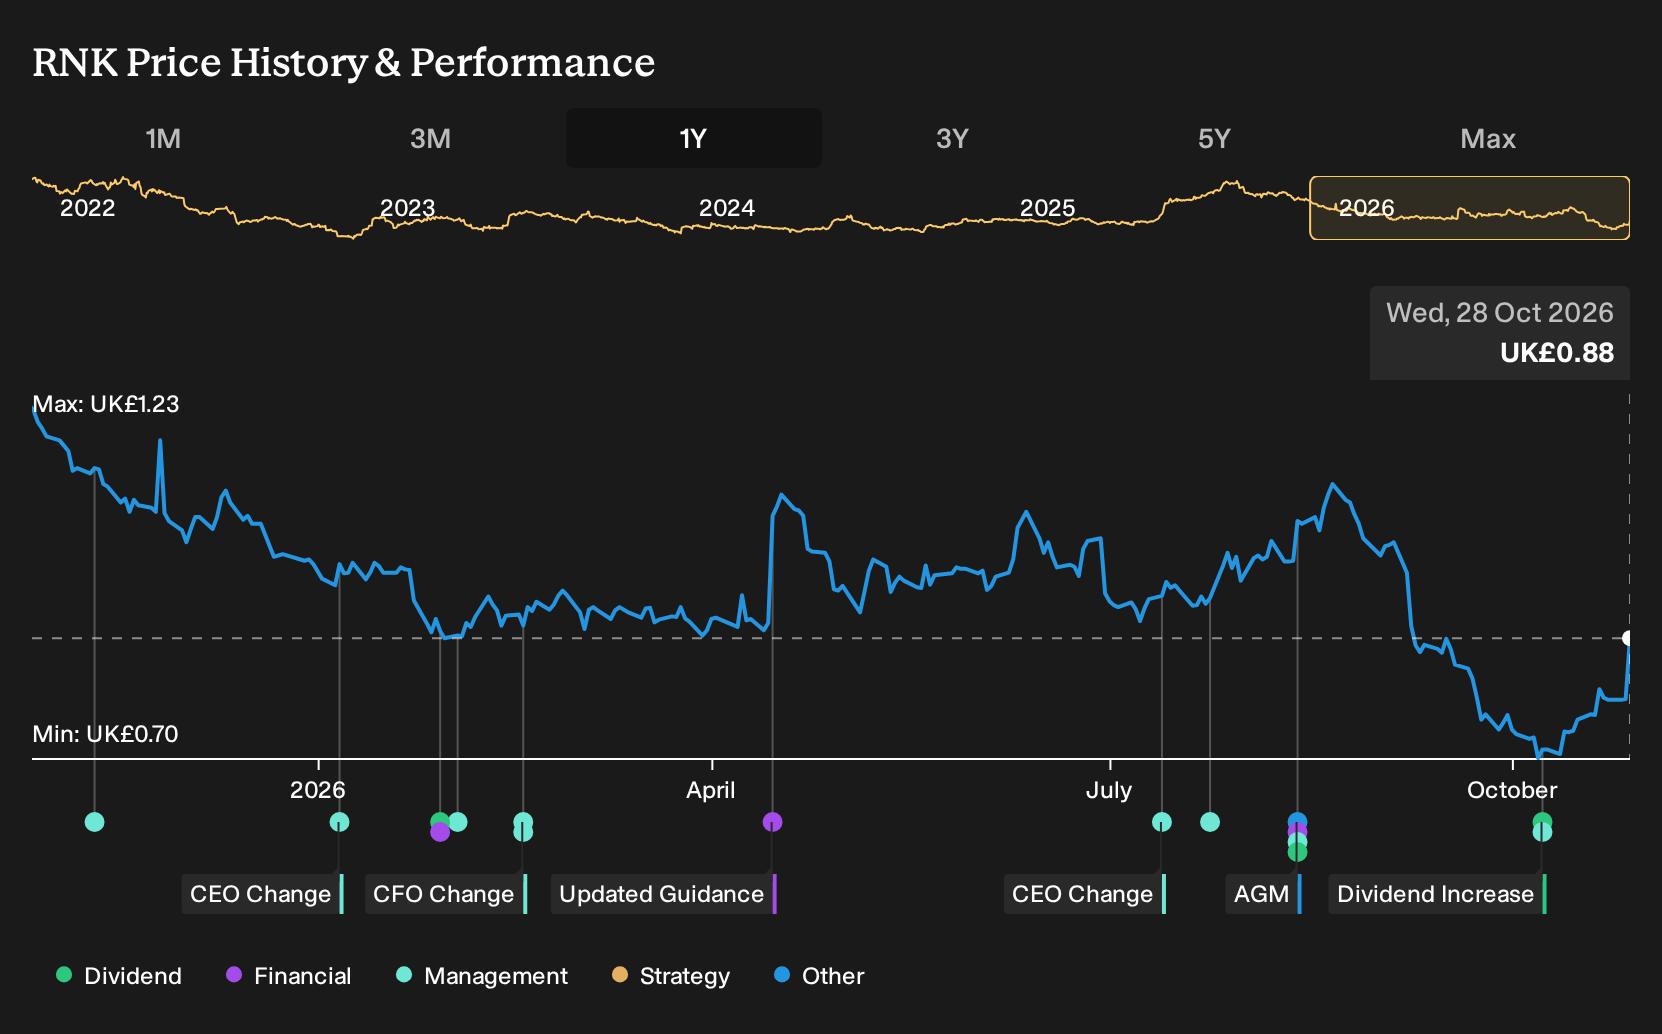
Rank Group (LSE:RNK) jumped 11.66% as mid cap leisure stocks such as Rank Group outperformed in London trading.
Whitbread (LSE:WTB) climbed 5.59% after shareholder Corvex welcomed proxy support for James Gemmel joining the Whitbread board.
SSE (LSE:SSE) advanced 4.58%.
Top Losers
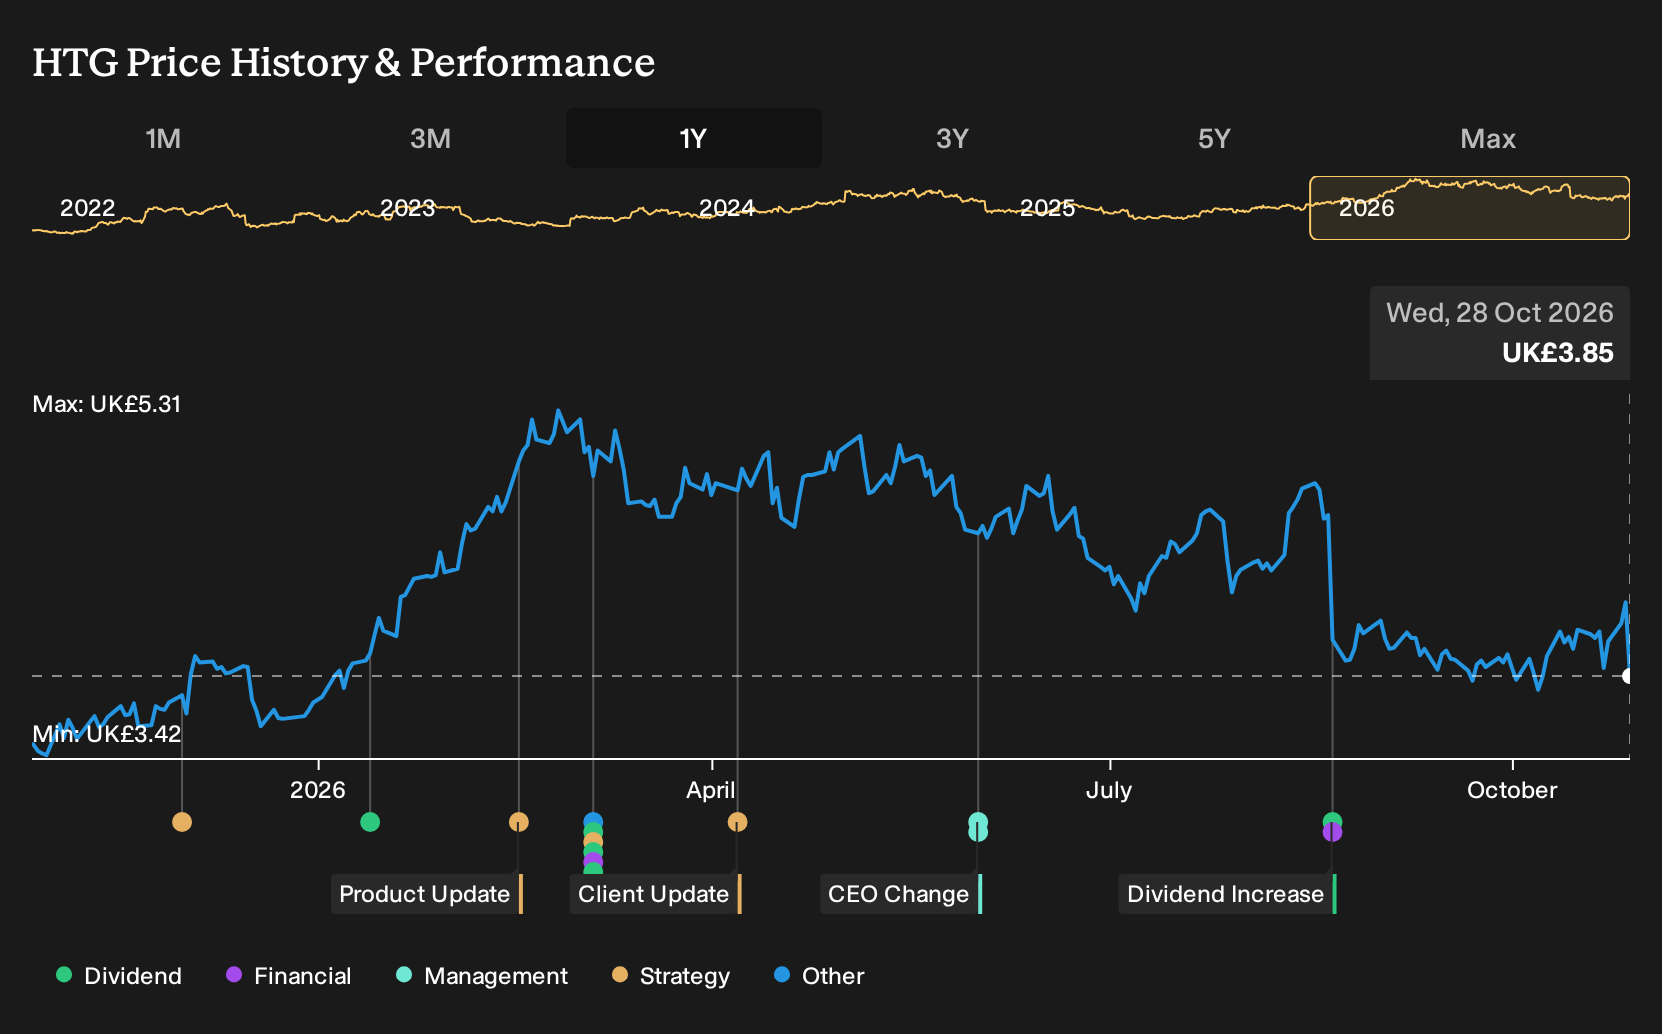
Hunting (LSE:HTG) fell 9.52% after trimming 2026 EBITDA guidance on weaker Middle East and North America activity.
Dar Global (LSE:DAR) declined 6.63% following updates on its expanded global real estate investment focus centred on Dubai.
Vistry Group (LSE:VTY) dropped 5.87% after recent gains linked to the CFO appointment unwound into profit taking.
On The Radar
Over the next few sessions the UK market is pinned between fresh Bank of England signals and a heavy run of domestic bank and consumer facing results.
- BoE Consumer Credit, Thu 29 Oct. A print above the £2.2b consensus would underline resilient borrowing even as shop price inflation runs at 2.1%, which can complicate the case for near term UK rate relief.
- UK Mortgage Approvals and Mortgage Lending, Thu 29 Oct. Figures above the 54k approvals and £4.2b to £4.5b lending markers would point to a firmer housing pulse that can keep pressure on rate expectations and rate sensitive domestically focused stocks.
- Lloyds Banking Group, Thu 29 Oct. Q3 2026 numbers at 7:00 AM UTC matter most for net interest income and credit quality, since this bank is tightly linked to the UK mortgage and consumer credit cycle.
- Shell, Thu 29 Oct. Q3 2026 earnings at 7:00 AM UTC put the focus on cash generation and capital returns, which can sway sentiment across London listed energy producers tied to global oil and gas prices.
- BoE Interest Rate Decision, Thu 5 Nov. The move relative to the current 3.75% rate and the market consensus of 4% will feed directly into pricing for UK banks, housebuilders and any equity where valuations lean on lower discount rates.
Sector & Industry Watch
Energy – Strong year, mixed company signals
Energy has edged higher over the past week and remains one of the stronger UK sectors so far this year. Shell is adding output through existing Gulf of America infrastructure, while Hunting just cut its 2026 profit guidance after softer activity in Saudi Arabia and North America.
If you hold oil related stocks, the main near term swing factor is how global crude prices react to incoming US inflation and growth data, because that feeds straight into cash generation for UK listed producers and your fuel costs.
Banks – Tax change meets rate uncertainty
Banks have declined over the last seven days and over the past month, lagging the wider Financials group. Recent news has been mixed, with Standard Chartered lifting its outlook after stronger profits, while the sector adjusts to a higher 6% UK bank surcharge and fresh shop price inflation at 2.1%.
If you own banking stocks, today’s Bank of England consumer credit and mortgage approvals figures are the key check on how households are coping with higher day to day prices and still elevated borrowing costs.
Real Estate – Gentle climb, housing data in focus
Real Estate has moved higher over the past week and month, outpacing the slightly softer GB Market in the short term. Activity around SEGRO, where a large asset manager has disclosed a sizeable stake, suggests big investors remain engaged even as housing exposed groups such as BRCK Group flag pressure from slower building and inflation.
For property heavy portfolios, today’s UK mortgage approvals and mortgage lending data will show whether this recent rise in listed landlords and house related plays fits with actual buyer demand and available credit.
Food, Beverage & Tobacco – Sector benefits as shop prices rise
Food, Beverage & Tobacco has gained over the past week and month, at a time when UK shop price inflation has picked up to 2.1% and food inflation runs higher still. Companies such as Unilever and Diageo are leaning on brands and premium launches, while MicroSalt is pushing low sodium ingredients that line up with health and regulatory trends.
If you hold supermarkets or branded food and drink stocks, the thing to watch next is how upcoming trading statements describe UK volumes and promotions into Christmas, because that will show whether shoppers are trading down or absorbing higher shelf prices.
Pharmaceuticals & Biotech – Stock specific swings around trial news
Pharmaceuticals & Biotech has inched higher over the past week, although individual shares are moving sharply on news. GSK fell after weaker vaccine sales and a cautious earnings outlook, while HUTCHMED secured US FDA Orphan Drug Designation for sovleplenib and Ondine Biomedical reported encouraging Phase 3 infection data.
If healthcare is a meaningful slice of your holdings, focus on upcoming company commentary about pricing and research spending, since that will show how management teams balance cost pressure with funding new treatments in the current UK inflation backdrop.
Identify The Next Market Leaders
With UK shop price inflation now at 2.1% and food rising 2.9%, income focused investors can stress test their holdings against higher day to day costs using this list of 224 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com