


China Resources Power Holdings (SEHK:836), What Is Behind The Fresh Attention?
China Resources Power Holdings (SEHK:836) released fresh operating data for September and the first nine months of 2026, showing higher total generation and faster growth from its wind and photovoltaic assets.
The operating update lands as the HK$19.03 share price has delivered a 7.94% year-to-date share price return. The 1-year total shareholder return of 10.01% and 3-year total shareholder return of 52.95% point to momentum that has built over a longer horizon, with the recent news likely shaping how investors weigh China Resources Power Holdings’ growth profile against perceived risks.
Track how China Resources Power Holdings fits into the broader move toward cleaner power and compare it with a curated 44 power grid technology and infrastructure stocks that is also geared to the energy transition.
China Resources Power Holdings appears to be a solid operator in both thermal and renewables, and the share price has already moved this year. The key question now is whether that business strength is already fully reflected in the current price of HK$19.03.
Preferred P/E of 7.4x: Is it justified for China Resources Power Holdings?
On simple earnings terms, China Resources Power Holdings trades on a P/E of 7.4x, which lines up with a HK$19.03 share price that looks low compared with both its own earnings record and many peers.
The P/E ratio compares what investors pay for each unit of profit. For a power producer that runs large coal and renewable fleets and reports high quality earnings, this metric helps you see how generously or cautiously the market prices those profits.
Earnings grew 3.1% over the past year and have risen by 25.8% per year over the last 5 years, yet the stock changes hands at 7.4x compared with a peer average of 13.6x and a Hong Kong market P/E of 10.3x. That gap suggests the market could be pricing in slower future progress than the broader sector, even though the estimated fair P/E of 9.8x still sits well above where China Resources Power Holdings trades today.
836 is good value based on its current P/E against the Hong Kong and wider Asian renewable energy industry, and the fair ratio implies meaningful room for the multiple to move closer to levels suggested by the regression model if sentiment or expectations shift.
Explore the SWS fair ratio for China Resources Power Holdings.
Result: Price-to-earnings of 7.4x (UNDERVALUED)
Still, tighter power regulation in the People’s Republic of China and any policy shift affecting coal and renewable tariffs could challenge the current China Resources Power Holdings valuation story.
Find out about the key risks to this China Resources Power Holdings narrative.
Another view on China Resources Power Holdings’ valuation
The P/E work suggests China Resources Power Holdings looks inexpensive, yet the SWS DCF model paints a different picture. At HK$19.03, the share price sits above an estimated future cash flow value of HK$18.40, which frames the stock as slightly overvalued on this lens. Which signal do you treat as more important?
For investors comparing cash flow and earnings based views side by side, it can help to see exactly how the model is built and where the assumptions sit relative to your own expectations. Look into how the SWS DCF model arrives at its fair value.
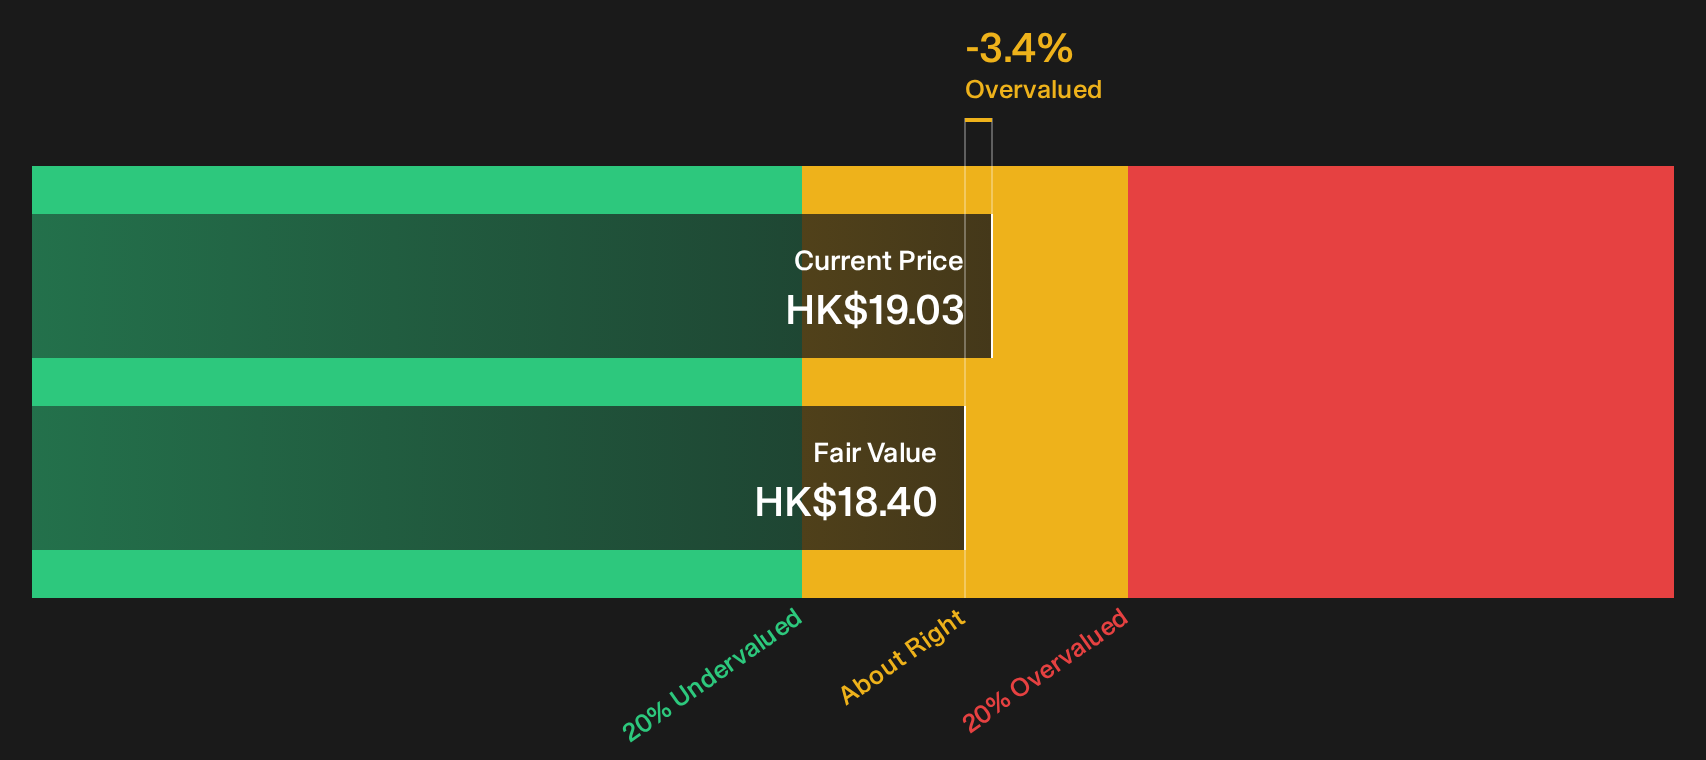
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out China Resources Power Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 191 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Feeling torn between the low P/E signal and the richer DCF result for China Resources Power Holdings is reasonable, so act while the data is fresh and pressure test both sides of the story for yourself with the 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond China Resources Power Holdings?
If you stop with China Resources Power Holdings, you only see part of the opportunity set. Cast the net wider and you might spot ideas others ignore.
- Scan for quality at a discount with a curated 191 high quality undervalued stocks that filters for strong businesses trading on restrained expectations.
- Prioritise resilience by using a focused 228 resilient stocks with low risk scores that highlights companies with steadier profiles when conditions get choppy.
- Hunt for future market leaders through a targeted 609 high quality undiscovered gems that surfaces solid fundamentals before they are widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com