


Veidekke (OB:VEI) Could Be 8% Below Fair Value As NOK 745 Million Contract Lands
Veidekke (OB:VEI) just added a sizeable project to its pipeline after securing a design and build contract with Thon Gruppen worth about NOK 745 million for a mixed-use Vitaminveien 6 development.
Veidekke’s NOK 211.5 share price has eased over the past month, with a 30-day share price return of a 2.98% decline. However, momentum over longer periods remains strong, with a 90-day share price return of 12.26% and a 1-year total shareholder return of 41.17%, signalling that interest has been building for some time.
Scan other construction and infrastructure players showing similar momentum and contract pipelines using the hand picked list of solid balance sheet and fundamentals (203 results)
Veidekke now trades only slightly below both analyst targets and an estimated fair value despite this new NOK 745 million contract win. Is that a cautious market mispricing, or a reasonable pause after a strong run?
Price-to-Earnings of 17x: Is it justified?
Veidekke trades on a P/E of 17x while recent performance has pushed the share price to NOK211.5, only modestly below both analyst targets and an internal fair value estimate.
The P/E ratio compares the current share price with earnings per share and, for a contractor like Veidekke, it reflects what investors are willing to pay for each krone of profit in a sector where growth and contract visibility tend to be steady rather than explosive.
Here, the market is paying more per unit of earnings than for the wider European construction peer group at 15x and more than an estimated fair P/E of 16x. That points to investors factoring in stronger execution, quality of earnings and return on equity than the average, and a valuation level that could move closer to that 16x fair ratio if sentiment or results shift.
Against the European construction industry average of 15x, Veidekke is priced at a clear premium on 17x P/E. It also trades richer than the 15.8x peer average, which signals investors are currently accepting a higher entry multiple than either the sector or the model fair value would suggest.
Explore the SWS fair ratio for Veidekke.
Result: Price-to-Earnings of 17x (OVERVALUED)
Still, Veidekke’s premium P/E and heavy exposure to large construction and infrastructure contracts leave the story vulnerable if project activity softens or if execution disappoints.
Find out about the key risks to this Veidekke narrative.
Another View: Veidekke Through A Cash Flow Lens
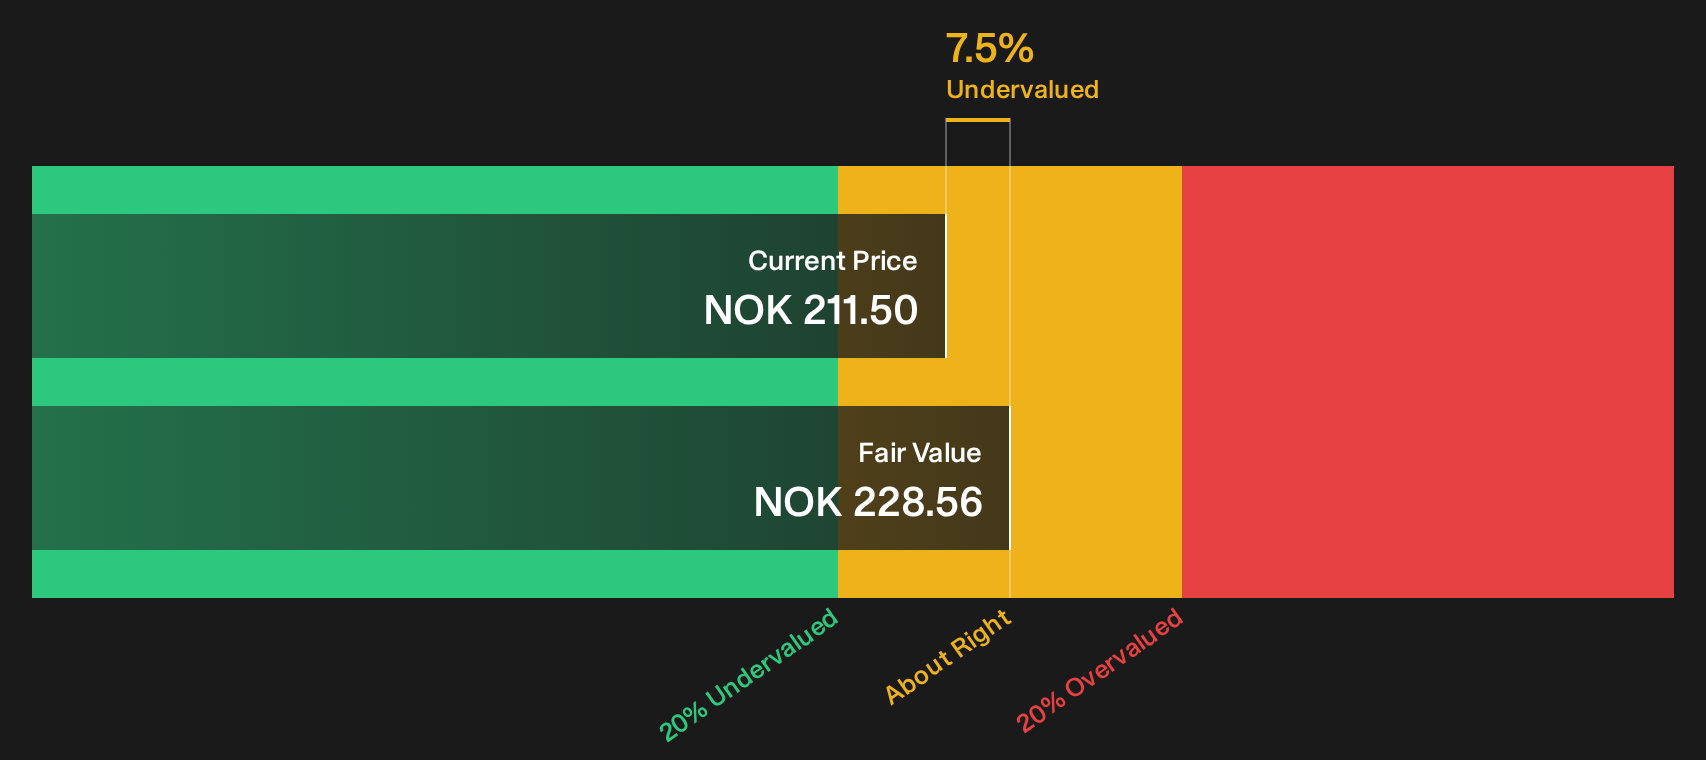
The earnings multiple paints Veidekke as expensive, yet the SWS DCF model points the other way. On this framework, NOK211.5 per share sits about 7.5% below an estimated future cash flow value of NOK228.56. This frames the current quote as a potential discount rather than a stretched entry point.
This raises a simple question for any holder: Are you more comfortable trusting what accounting profits imply today, or the cash flow assumptions sitting inside that DCF model?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Veidekke for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 191 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Veidekke is clearly split, which is exactly when it can be useful to study the facts yourself instead of following the crowd. Consider acting in a timely manner, weighing the contract wins against the potential execution issues, and then decide where you stand after reviewing the 3 key rewards and 1 important warning sign
Looking for more Veidekke-like investment ideas?
If Veidekke has sharpened your focus on quality and timing, do not stop here. Broaden your watchlist now and give yourself more options tomorrow.
- Target potential value opportunities by scanning companies that combine solid fundamentals with attractive pricing using the 191 high quality undervalued stocks
- Strengthen your income stream by reviewing businesses with robust yields and payout profiles through the 226 dividend fortresses
- Prioritise resilience by filtering for companies with healthy finances and durable balance sheets via the 228 resilient stocks with low risk scores
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com