


Aptiv (APTV) Stock May Be Undervalued After Automated Driving Deal
Aptiv has had a rough stretch in the market, and the share price is now well below where many investors might remember it. With the stock under pressure, the key issue is whether the current valuation can be explained by the earnings the business is generating.
- Over the past 5 years, Aptiv shares have fallen 70.8%, which puts the spotlight squarely on whether the current price is still aligned with its underlying earnings power.
- The expanded collaboration with NVIDIA on automated driving may support expectations for future profit streams, since any successful rollout of scalable systems can influence how durable and predictable Aptiv's earnings might look over time.
- The analysts covering Aptiv have run their own numbers. See what analysts think Aptiv's shares could be worth.
For investors, the debate is whether Aptiv's current share price around US$44 is appropriately supported by what the company earns today and what those earnings could reasonably sustain.
If you are reassessing Aptiv after a tough 5 year stretch, it can also help to compare it with a focused list of 96 robotics and automation stocks.
Does Aptiv Look Undervalued on Earnings?
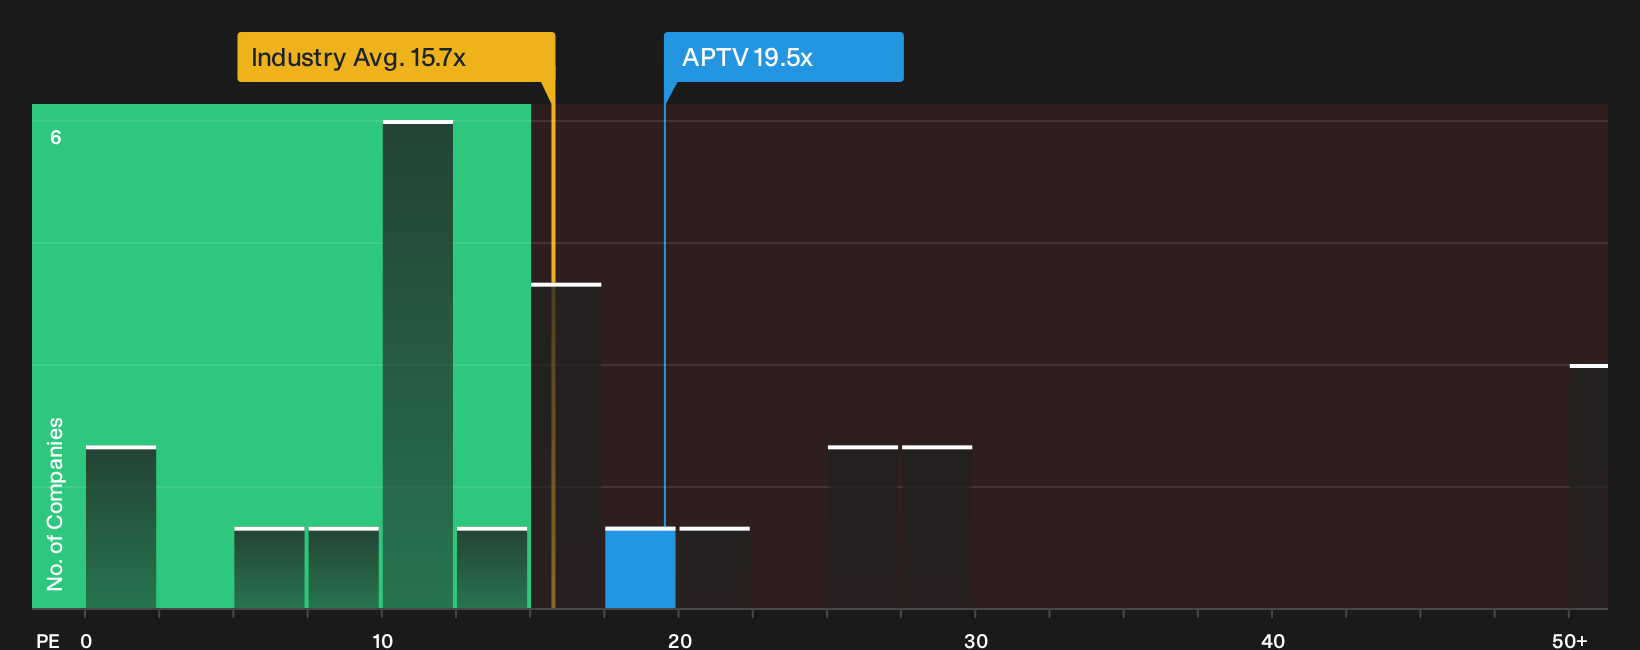
The P/E ratio works reasonably well for Aptiv because earnings remain a core yardstick for how investors weigh the business against other Auto Components stocks. On this measure, Aptiv trades on roughly 19.5x earnings, which is higher than both the peer group average of about 15.7x and the wider Auto Components industry level near 15.7x.
Because the fair multiple suggested by the model is above where Aptiv currently trades, the stock screens as undervalued on this P/E framework even though the absolute ratio is not low against sector benchmarks. The expanded NVIDIA collaboration keeps automated driving in focus for Aptiv. Yet despite that attention, the market is still pricing the shares below what this tailored earnings multiple implies. Explore the numbers behind Aptiv's P/E valuation.
The Aptiv Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Aptiv pick up where this valuation puzzle leaves off by spelling out which future paths for growth, margins and earnings would need to hold for the stock to be worth meaningfully more or less than today’s price on the Community page. Each scenario links a fair value estimate to a clear story about Aptiv's potential catalysts and key risks, so you can track over time which version of events appears to be taking shape.
One of the top community narratives on Aptiv: 31% undervalued
"The main factor that needs to go right is Aptiv successfully scaling its higher-margin non-automotive businesses, including robotics, drones and other diversified end markets..."
Discover why this Narrative puts Aptiv at 31% undervalued.
One more Aptiv check that belongs next to the price tag
Before you weigh Aptiv only on earnings and P/E, it helps to see what the broader fundamental checks are flagging about the business profile and balance sheet. Take a closer look at 3 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com