


Alm. Brand (CPSE:ALMB) Stock Confronts Q3 Earnings Durability Question
Alm. Brand walked into Q3 2026 earnings with the stock at DKK17.63 and a quietly positive tape, up over the past week and month. Then the insurance group dropped a headline number that hits straight at underwriting quality. Management reported the highest insurance service result to date at DKK755m, powered by very low weather and major claims plus strong run off gains. The share price move now reflects a tug of war between traders reacting to that underwriting high point and investors asking how much of this quarter is repeatable.
Love Alm. Brand’s underwriting high point but unsure how much of this quarter’s low claims and strong run off can stick around? Compare that profile with our list of solid balance sheet and fundamentals stocks (204 results)
Q3 2026 Earnings Summary
- Total Revenue (Q3 2026 vs. Q3 2025): DKK 3,112m vs. DKK 3,392m (down 8.3%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): DKK 397m vs. DKK 322m (up 23.3%)
- Basic EPS (Q3 2026 vs. Q3 2025): DKK 0.29 vs. DKK 0.23 (up 28.4%)
- Net Profit Margin (Trailing 12 Months vs. Prior Year): 7.3% vs. 7.6% (down 0.3 percentage points)
Earnings tell one story for Alm. Brand, but investors who care about valuation often put just as much weight on the cash coming through the door. Cash generation can paint a different picture of what the current share price implies.
On Alm. Brand's recent cash flows alone, a hypothetical valuation model suggests the stock could be a dramatic 32% undervalued.
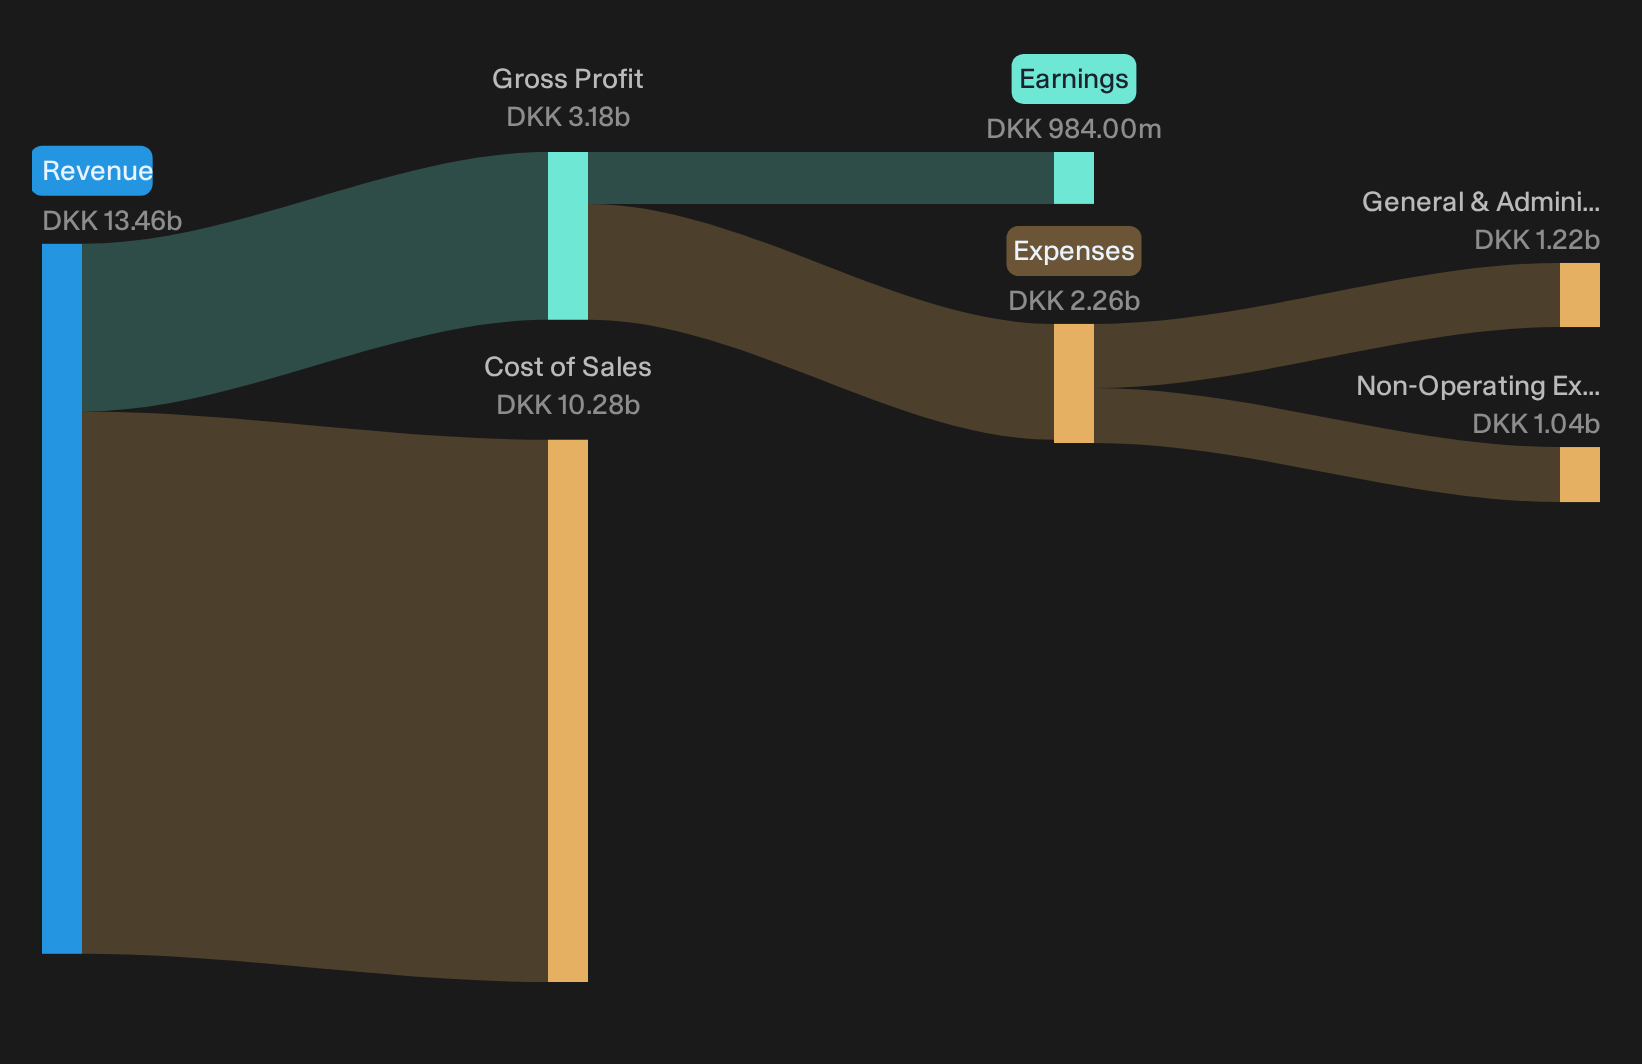
Alm. Brand underwriting story meets Q3 reality
Optimists argue Alm. Brand’s reshaped business mix should steadily clean up the claims profile and cost base.
"The company is executing repricing and pruning in workers’ compensation and large industrial risks, with management indicating that much of the premium being shed contributes almost no technical result."
Q3 Commercial Lines premiums fell 1.8%, yet the Commercial combined ratio moved to 71.7% with a better underlying claims ratio and strong run off. Group underlying claims improved and the cost ratio sat around 17%. That combination points to meaningful progress on the margin quality target, even if weather and run off add a temporary boost.
Bear case tests Alm. Brand reinvestment and growth
The main pushback is that Alm. Brand could be over-distributing cash while hollowing out growth engines and Commercial momentum.
"The company still operates with very high capital returns, including ordinary and extraordinary buybacks and dividends that together are close to full earnings. This may continue to limit Alm. Brand’s capacity for reinvestment and balance sheet flexibility and in turn constrain future earnings growth."
Guidance now points to a higher 2026 insurance service result and profit before other income and expenses, helped by low major claims, run off and efficiency moves like 85 FTE cuts. Commercial premiums declined, with underlying broad commercial growth around 1%, so the concern about slower reinvestment translating into muted volume improvement is not fully cleared.
One Narrative disagrees with today's price. → See where this Narrative says Alm. Brand should trade.
Hunt For Quiet Mispricings
Alm. Brand just showed how a single quarter can raise new doubts about how durable a story is. The real opportunity is spotting stocks that could be undervalued before new information forces investors to reconsider their views.
- Company 1 - 29% below our estimate - scale planned data center capacity while shifting from basic co location to higher value sovereign and compliant cloud services.
- Company 2 - 42% below our estimate - expand power and rack capacity so constrained facilities can better support growing cloud and AI infrastructure demand.
- Company 3 - 33% below our estimate - extend digital farming tools and specialty crop solutions as refinanced debt and new credit lines increase balance sheet flexibility.
Three companies from the same screener. Open every one of the 195 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com