


Whirlpool (WHR) Stock May Be Undervalued Following Cut Revenue Guidance
Whirlpool shares have fallen sharply in recent years, which puts fresh focus on a simple question for investors who still follow the stock. Does the current price around US$27 reflect what the business is actually earning today and what those earnings might support over time?
- The share price has dropped about 84% over the past 5 years, which puts past expectations about Whirlpool's earning power under close scrutiny.
- Recent losses and lower revenue expectations have pushed earnings into the red, which can reshape how investors think about the durability and timing of Whirlpool's profit recovery.
- The analysts covering Whirlpool have run their own numbers. See what analysts think Whirlpool's shares could be worth.
For investors, the debate is whether Whirlpool's current share price is adequately supported by its recent earnings performance and what those earnings suggest for the future.
You can pressure test Whirlpool's earnings story against a wider field of companies by scanning 29 high quality undervalued stocks.
Is Whirlpool a Bargain on Earnings?
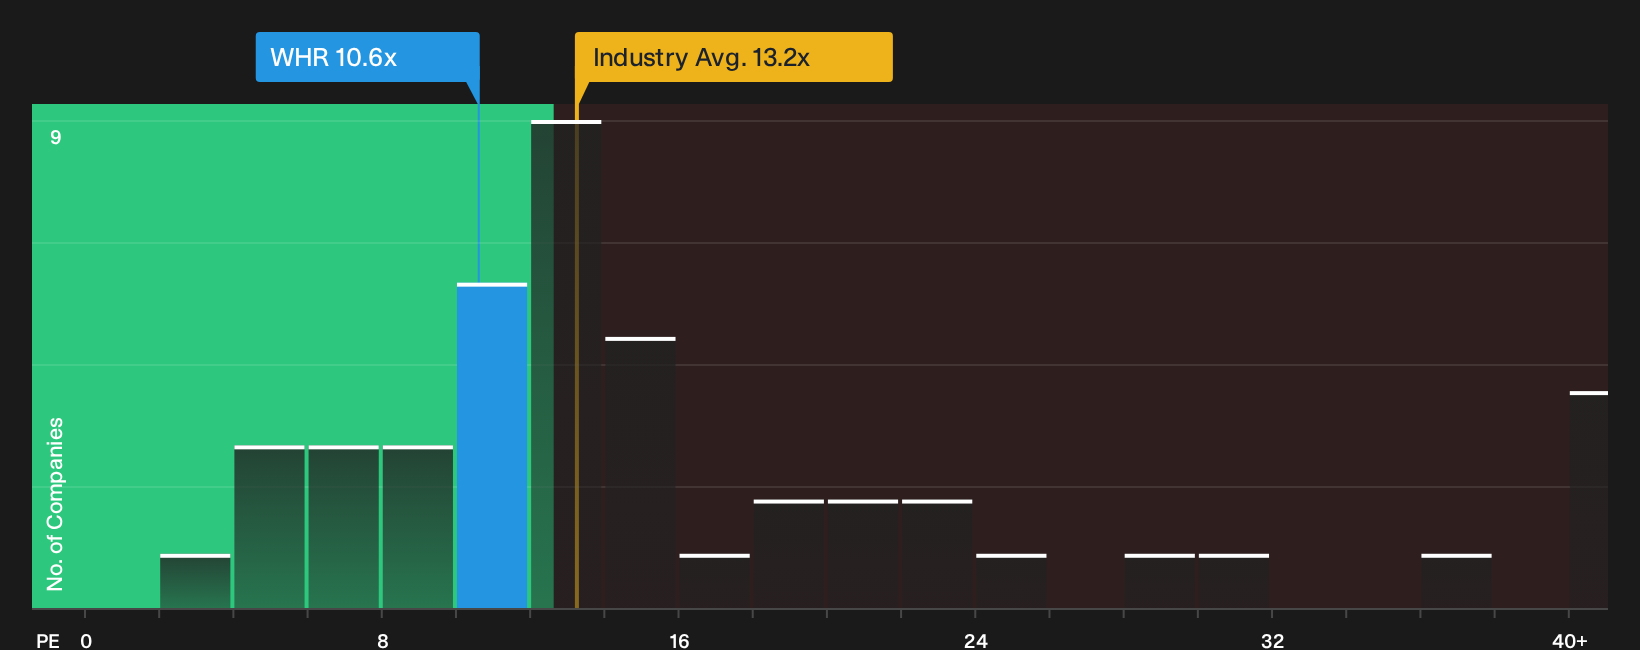
The P/E ratio suits Whirlpool because earnings usually sit at the center of how investors judge a mature home-appliance manufacturer. On this measure, Whirlpool trades on a P/E of 10.6x, compared with a Consumer Durables industry average of about 13.2x and a peer group closer to 9.4x. Because the tailored fair multiple comes in higher than where the stock currently trades, the model reads Whirlpool as undervalued on earnings relative to what its mix of margins, growth assumptions, size and risk profile would typically support.
Because the latest guidance points to a full year loss after a weak Q3, the P/E looks compressed at the same time that recent results have been under heavy pressure. That tension means the current discount might reflect concern that the recent earnings shortfall persists for longer than analysts expect, or it could indicate investors are pricing in a deeper reset to Whirlpool's long term profitability. You can compare this implied earnings discount with the modelled fair P/E and other valuation checks in more detail at. Explore the numbers behind Whirlpool's P/E valuation.
The Whirlpool Narrative: What Would Justify Today's Price?
Narratives pick up where Whirlpool's valuation puzzle leaves off. They spell out which expectations on growth, profitability and earnings would need to play out for the share price to sit meaningfully above or below where it trades today, and each one presents Whirlpool's fair value as a clear thesis about the business that you can watch over time on Simply Wall St's Community page.
Community views on Whirlpool are split between a margin driven recovery story and a housing linked drag that keeps returns under pressure.
Bull case: 74% undervalued
"The SDA Global business is already running at around 12% EBIT margin with double digit sell through and high teens point of sale growth..."
Discover why this Narrative puts Whirlpool at 74% undervalued.
Bear case: 24% overvalued
"Despite a detailed program targeting about US$150 million of cost takeout in 2026 and further benefits from factory and logistics moves into 2027 and 2028, the company is still reporting very low ongoing EBIT margins and has already consumed more than US$2.0b of free cash flow in the first half of 2026..."
Explore why this Narrative puts Whirlpool at 24% overvalued.
Whirlpool’s valuation still leaves one crucial piece off the table
Price and earnings only tell part of the Whirlpool story, because the people directing capital and how they are rewarded can tilt outcomes in ways the share chart does not show. See who runs Whirlpool and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com