


MasTec (MTZ) Moved Higher, What Is Catching Investor Attention?
MasTec (MTZ) heads into its Thursday afternoon earnings release with expectations in clear focus. The market is watching for September quarter revenue of US$4.94b and earnings of US$2.94 per share.
Recent trading has been choppy for MasTec, with the 30 day share price return down 17.1% and the 90 day share price return down 38.6%, even after a 2.3% gain in the latest session that leaves the stock at US$176.5. Across a longer stretch, the picture looks different, with a 3 year total shareholder return of about 197% and a 5 year total shareholder return of about 96%. This suggests the recent weakness has come after a strong multi year run as investors reassess risk and expectations heading into this earnings release.
Spot opportunities around MasTec’s setup by scanning infrastructure focused contractors and builders in the 42 power grid technology and infrastructure stocks that are poised around key earnings and project cycles.MasTec now trades at a steep discount to both analyst targets and some intrinsic value estimates after a sharp pullback. Is that pricing in real project and earnings risk, or does it lean too heavily into caution ahead of results?
Most Popular Narrative: 54% Undervalued
Against the last close at $176.5, the most followed narrative for MasTec points to a fair value of $386.1. This frames a wide valuation gap that investors are weighing against execution and funding risks in the current project mix.
Continued reshaping of US energy infrastructure toward utility scale renewables, storage and gas fired generation, supported by the Clean Energy & Infrastructure segment’s roughly US$7.8b backlog and 2026 revenue outlook of about US$6.8b with high single digit EBITDA margins, provides a visible path for segment level revenue and EBITDA growth beyond current contracts.
See why 30 investors see MasTec as 54% undervalued.
Result: Fair Value of $386.1 (UNDERVALUED)
Still, the MasTec narrative hinges on turning a large backlog into profitable work while avoiding further setbacks in the more unpredictable Communications segment.
Find out about the key risks to this MasTec narrative.
Another View on MasTec’s Valuation
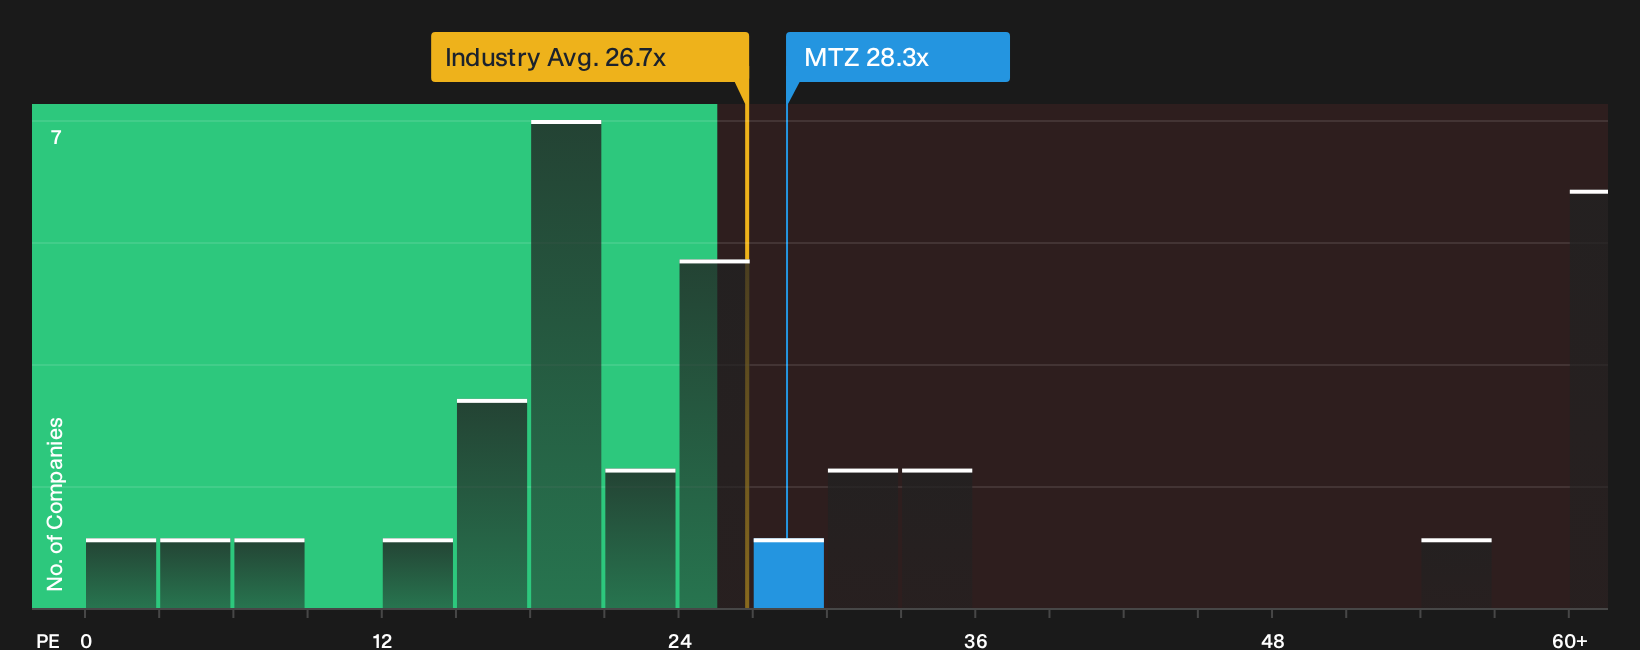
While the narrative fair value for MasTec lands at about $386.1 per share, a different lens tells a cooler story. The current P/E of 28.3x sits above both the US Construction industry at 26.7x and peers at 20.8x, even though the fair ratio is estimated at 37.7x. That mix of premium versus peers yet discount to the fair ratio raises a simple question for investors: is the market overpaying for recent growth or underestimating the earnings runway?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views exist about whether MasTec’s setup is attractive or too finely balanced. Act quickly, review the data yourself, then weigh the 3 key rewards and 1 important warning sign.
Looking for more MasTec-sized opportunities?
Do not stop your research with MasTec. Broaden your watchlist using structured stock ideas that match your risk appetite and income goals.
- Target potential mispricing by scanning a curated pool of quality businesses on the 29 high quality undervalued stocks.
- Strengthen capital preservation by focusing on companies with robust finances using the list of solid balance sheet and fundamentals (24 results).
- Boost income potential by reviewing reliable payout candidates through the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com