


Take Two Interactive Software (TTWO) Nears Earnings With GTA VI Hopes On An Undervalued View
Take-Two Interactive Software (TTWO) heads into its upcoming fiscal second quarter earnings on November 9 with expectations for lower profit per share and softer revenue, keeping investor attention firmly on the next update.
Recent trading has been soft, with a 1-day share price return of 1.02% lower, a 7-day share price return of 2.62% lower, and the 90-day share price return down 18.32% as investors weigh earnings risk against anticipation around Take-Two Interactive Software’s longer term pipeline and a 3-year total shareholder return of 50.49%.
Scan how other media and gaming stocks with solid balance sheets are setting up around earnings season by comparing Take-Two against a curated list of solid balance sheet and fundamentals (24 results)
After a near 20% drop this year and a share price sitting below both analyst targets and some fair value models, is Take-Two Interactive Software priced for too much risk or not enough caution?
Most Popular Narrative: 27% Undervalued
The current Simply Wall St narrative pegs Take-Two Interactive Software’s fair value at $276.97, above the last close of $201.28. That gap sets the stage for a thesis built around one franchise that could reshape how investors view the entire business.
GTA V’s online ecosystem, which is now 13 years old, generated revenue for over a decade and continues to do so. If GTA VI online follows a similar trajectory, the long tail value of this single title is almost incalculable on a conventional near-term model.
See why 95 investors see Take-Two Interactive Software as 27% undervalued.
Result: Fair Value of $276.97 (UNDERVALUED)
Still, the narrative around Take-Two Interactive Software can be upset if GTA VI faces fresh delays, or if live service spending softens more than expected.
Find out about the key risks to this Take-Two Interactive Software narrative.
Another View: What Take-Two’s P/S Ratio Is Signalling
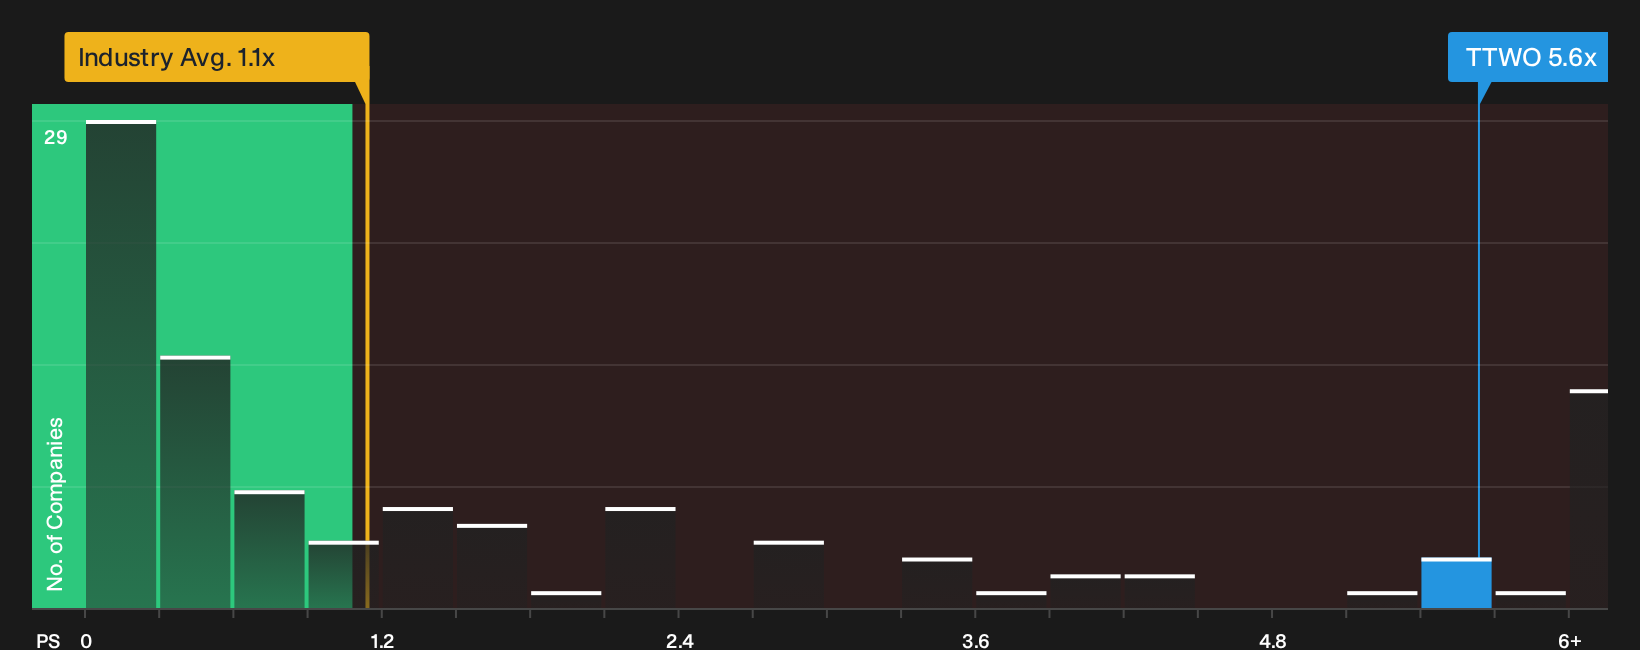
That 27% fair value gap from the Simply Wall St narrative leans on a discounted cash flow view of Take-Two Interactive Software. The market is telling a different story through the P/S ratio. TTWO trades on 5.6x sales compared with 2.6x for peers and 1.1x for the wider US Entertainment group, while the fair ratio is 3.5x. That is a wide premium. It suggests investors are already paying up for future wins, so how comfortable are you with that baked in optimism?
See what the numbers say about this price in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The mix of optimism and concern around Take-Two Interactive Software is clear. Move quickly, review the full data set, and weigh the 3 key rewards and 1 important warning sign.
Looking for more ideas beyond Take-Two Interactive Software?
If you stop with Take-Two Interactive Software, you leave a lot on the table. Use the Simply Wall St screener to spot opportunities that better fit your goals.
- Target resilient compounding by scanning companies with strong balance sheets and dependable fundamentals through our list of solid balance sheet and fundamentals (24 results).
- Hunt for mispriced opportunities by focusing on quality businesses trading below their estimated worth in the 29 high quality undervalued stocks.
- Spot potential rising stories early by filtering for strong financial profiles among under-followed stocks in the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com