


Is Nagase (TSE:8012) Fairly Valued After Its Recent Share Price Run?
Nagase (TSE:8012) has drawn fresh attention after a recent move in its share price, with the stock showing gains over the past month and past 3 months that investors are now reassessing.
That recent move fits into a stronger trend for Nagase, with a year to date share price return of 24.04% and a 1 year total shareholder return of 48.92% pointing to building momentum that long term holders, who have seen a 5 year total shareholder return of 191.32%, will already recognise.
Scan other momentum-driven industrials with solid fundamentals by reviewing the hand picked 72 high quality undiscovered gems alongside Nagase's recent share price run.
After that kind of run, the real tension for Nagase holders is simple: Does the current valuation still leave enough upside to justify fresh risk, or has most of the easy reward already been taken?
Price-to-Earnings of 12.3x: Is it justified?
Nagase now trades on a P/E of 12.3x, which leaves the stock looking more expensive than both its industry and direct peers despite the recent share price surge.
The P/E ratio compares the current share price to earnings per share and gives a quick sense of how much investors are paying for each unit of profit. For a diversified trading and distribution business like Nagase, this metric is often used as a shorthand for how the market rates the quality, durability, and growth profile of its earnings stream.
On simple comparisons, the market is assigning Nagase a richer valuation. The current 12.3x P/E is higher than the JP Trade Distributors industry average of 10.5x and also above the peer group on 10.6x, which indicates investors are paying more for each yen of earnings. At the same time, that 12.3x level is below the estimated fair P/E of 14.9x, which highlights a gap the market may close if sentiment and fundamentals remain aligned.
Explore the SWS fair ratio for Nagase.
Result: Price-to-Earnings of 12.3x (ABOUT RIGHT)
Still, the story can change quickly if sentiment around Japanese industrial exporters cools or if Nagase faces pressure on margins across its chemicals and electronics lines.
Find out about the key risks to this Nagase narrative.
Another View: What Our DCF Model Says About Nagase
The P/E story paints Nagase as roughly in line with fair value, but the SWS DCF model comes in colder. On that framework, the estimated future cash flow value is ¥984.62 per share versus a current price of ¥1,212.5. This points to an overvalued stock and raises a simple question: Which lens do you trust more, earnings today or cash flows tomorrow?
Look into how the SWS DCF model arrives at its fair value.
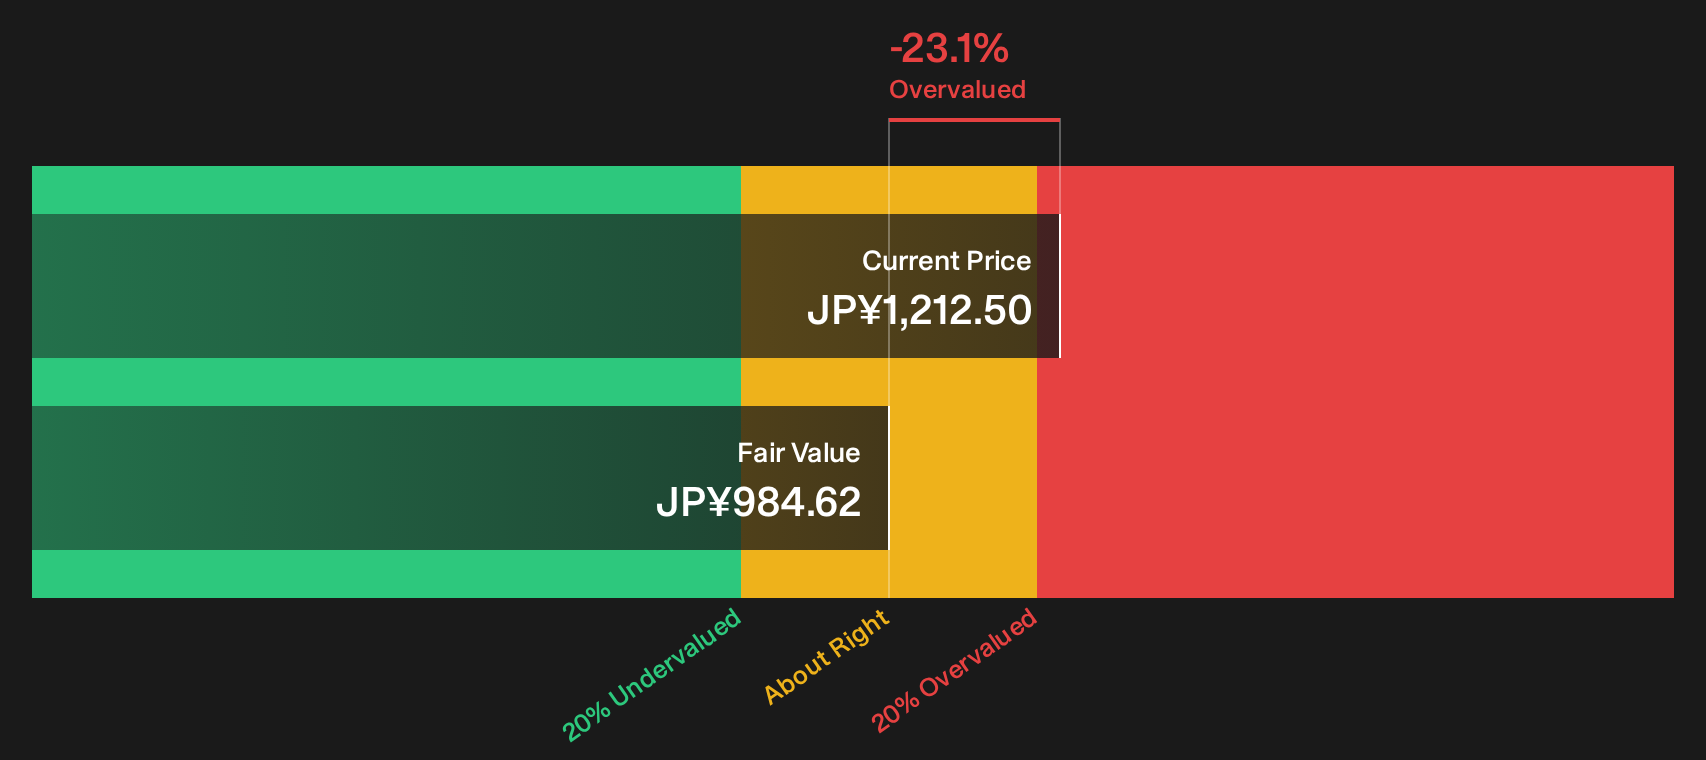
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Nagase for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 16 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Nagase's value case so far. Review the situation while the data is fresh and weigh both caution and upside by checking the 3 key rewards and 1 important warning sign.
Looking for more ideas beyond Nagase?
If Nagase has sharpened your focus on valuation and momentum, do not stop here. Use the Simply Wall Street Screener to line up your next watchlist candidates.
- Target strong fundamentals and potential mispricing by running a fresh search through the 16 high quality undervalued stocks that meet your quality and balance sheet standards.
- Prioritise resilience and capital protection by sorting for companies in the 22 resilient stocks with low risk scores that fit your comfort level on volatility and financial strength.
- Hunt for future watchlist candidates before the crowd by scanning the 1 elite penny stocks with strong financials that already show solid financial underpinnings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com