


Astrana Health (ASTH) Could Be 28% Undervalued On Alignment Health Deal
Astrana Health (ASTH) drew fresh attention after announcing a provider collaboration with Alignment Health Plan that will widen Medicare Advantage access across California from 2027, including multilingual and culturally focused primary and specialist care.
Astrana Health’s latest announcement lands after a strong run, with the share price showing a 47.62% year-to-date return even as the 90-day share price return slipped 1.95%. At the same time, the 1-year total shareholder return of 12.65% and 3-year total shareholder return of 22.83% point to gains that contrast with a 5-year total shareholder return decline of 47.32%. This suggests current enthusiasm around deals such as the Alignment Health Plan collaboration is being weighed against a longer track record that has been more mixed for long-term holders.
Spot other healthcare management stocks that could be setting up for the next move by scanning our hand picked 34 healthcare AI stocks alongside Astrana Health.Astrana Health has already delivered a sharp move this year, so the next question is simple. Does the recent Alignment deal leave meaningful upside ahead, or has most of the rerating already happened in the share price?
Most Popular Narrative: 28% Undervalued
Astrana Health closed at $37.23, while the most followed narrative anchors fair value at $51.67 using a 7.54% discount rate. This frames the recent Alignment partnership against a thesis built on full risk contracts and cash generation rather than short term headlines.
The main thing that has to go right is that Astrana Health continues to convert and manage more members in full-risk arrangements while its AI-enabled operating system keeps driving G&A efficiency, free cash flow generation, and successful integration of deals like Prospect despite ongoing Medicaid churn and cybersecurity scrutiny.
See why 6 investors see Astrana Health as 28% undervalued.
Result: Fair Value of $51.67 (UNDERVALUED)
Still, the Astrana Health story carries real pressure points, including reimbursement changes on government plans and any stumble integrating acquisitions like Prospect that could hit earnings power.
Find out about the key risks to this Astrana Health narrative.
Another View: What Astrana Health’s P/E Is Telling You
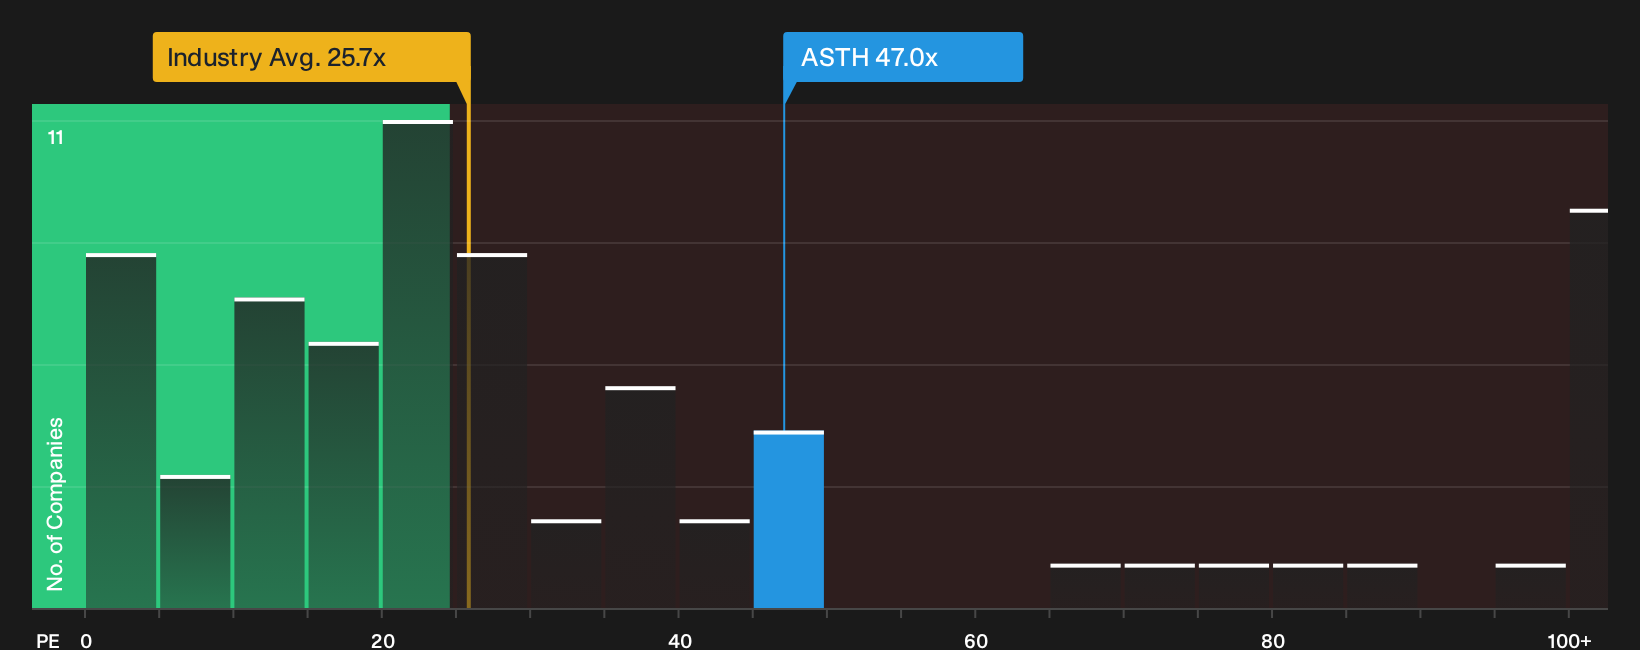
The first narrative leans on fair value and cash flow, yet the P/E ratio offers a more focused view of pricing. Astrana Health trades on roughly 47x earnings, compared with a fair ratio of 35.8x, the US Healthcare average of 25.7x, and a peer group closer to 51.3x.
This combination of a higher headline multiple than the broader industry but below closer peers, and still a premium to the fair ratio, leaves investors considering whether they are paying up for quality or taking on valuation risk if sentiment cools.
For a closer look at how these earnings multiples compare and what they might imply if the market moves toward the fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Astrana Health can either spook you or sharpen your thinking, so move quickly, check the underlying metrics, and decide where you land based on the 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond Astrana Health?
If Astrana Health has sharpened your thinking, do not stop there. Broaden your watchlist with focused filters that surface companies aligned with your priorities.
- Target potential mispricing by screening for quality businesses that look cheap on key metrics using the 29 high quality undervalued stocks.
- Lock in income candidates by reviewing a curated set of higher yielding payers through the 5 dividend fortresses.
- Dial back risk by focusing on financially resilient companies with cleaner balance sheets through the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com