


How Investors May Respond To DXC Technology (DXC) Governed AI Partnership
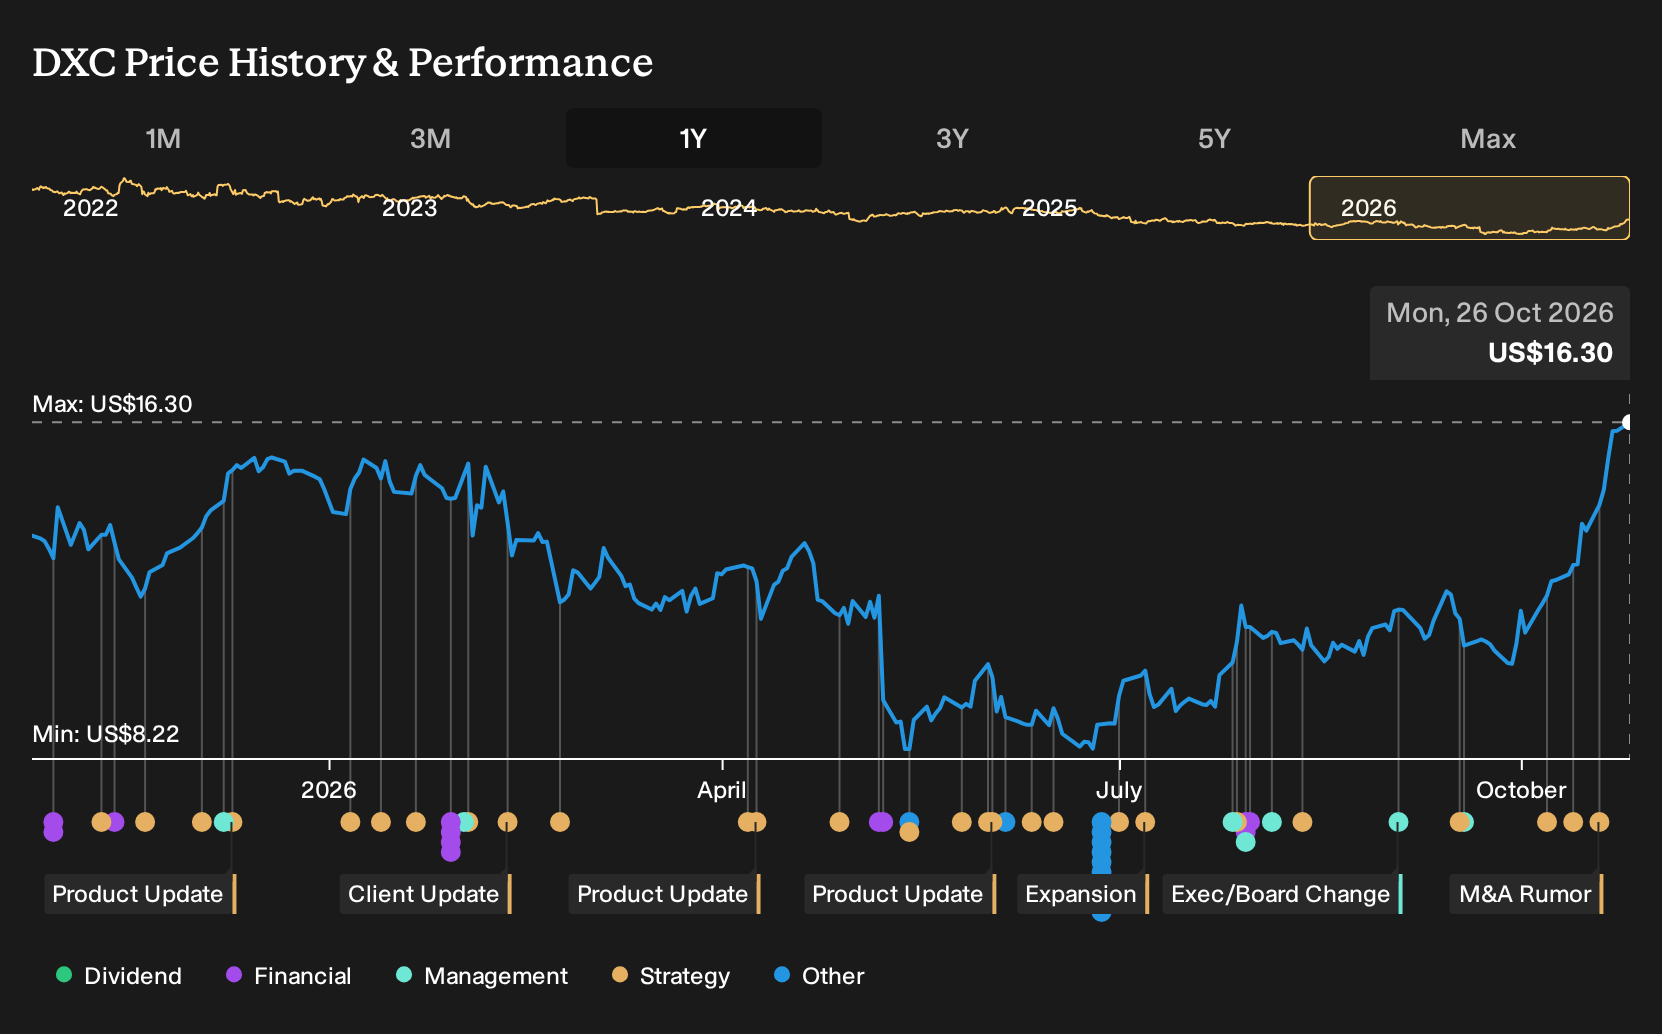
- DXC Technology has reportedly been in advanced talks to sell its global insurance software and services division to Eldridge Industries for about US$2.4b, with Eldridge considering a combination of the asset with its Zinnia insurance technology platform.
- The potential divestiture would move DXC Technology further away from traditional insurance outsourcing work and focus its efforts on higher value, AI driven IT operations and software platforms across regulated industries.
- We will now see how DXC Technology’s push into governed AI agents, highlighted by the LangChain partnership, could influence its investment narrative.
Compare DXC Technology’s AI pivot with other potential breakouts in mission critical tech by scanning our curated list of 55 AI infrastructure stocks for your watchlist.
DXC Technology Investment Narrative Recap
To be a shareholder in DXC Technology, you need to believe the shift from labor intensive contracts to AI led platforms like OASIS can gradually offset current revenue pressure. The rumored US$2.4b sale of the insurance division would fit that story only if the remaining portfolio can still keep bookings growing and sustain a book to bill above 1.0.
The main near term swing factor is whether DXC Technology can stabilize organic revenue while lifting margins off a 1% profit base and managing high debt. The biggest risk is that Global Infrastructure Services keeps declining, eroding EBIT margin, while any divestiture proceeds or AI wins do not translate into stronger cash generation.
The LangChain partnership is the most relevant operational update alongside the potential insurance sale because it relates directly to the core thesis around governed AI agents in mission critical IT. OASIS already runs across dozens of customer environments with measured incident handling time reductions, which directly supports the margin improvement story if adoption broadens.
For you as an investor, this puts execution under a spotlight. DXC Technology needs to keep proving that OASIS and related AI tooling can replace low margin support work at scale without creating new operational or reputational issues in highly regulated sectors. If that proof point stalls while revenue continues to decline, the AI narrative becomes far less convincing.
DXC Technology's current analyst narrative assumes revenues of US$11.9b and earnings of US$169.4 million by 2029, built on a 1.7% yearly revenue decline and a move from US$124.0 million of earnings today to that 2029 consensus, which is an increase of roughly US$45 million.
Uncover why DXC Technology's fair value indicates a 30% potential downside to its current price that leaves little room for error.
Exploring Other Perspectives
One alternate angle on DXC Technology focuses on the risk that GIS weakness drags on longer than expected. The most bearish analysts were already working off revenue of about US$11.8b and earnings near US$179.7 million by 2029 before this insurance sale rumor. You can treat those lower forecasts as a stress test and explore how the potential deal, together with the LangChain alliance, might eventually reshape those expectations.
Explore 3 other DXC Technology fair value estimates, including one that suggests there could be as much as 44% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your DXC Technology research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for DXC Technology. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate DXC Technology's overall financial health at a glance.
Looking For More Ideas Beyond DXC Technology?
If the DXC Technology story has sharpened your thinking and you want to widen your opportunity set, the Simply Wall St Screener can help you quickly filter for other listed businesses that fit your risk and return preferences.
- For investors who want income without ignoring quality, consider companies that show up in our 5 dividend fortresses as a starting universe for further research.
- If capital protection matters most to you, focus on stability first and use the 30 resilient stocks with low risk scores to identify businesses with more resilient profiles.
- When you are hunting for underfollowed potential, broaden your watchlist with the 21 high quality undiscovered gems that combine strong fundamentals with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com