


How Investors May Respond To Bridgestone Stock As New Tire Launches Roll Out
- Bridgestone recently introduced the BATTLAX ADVENTURE A42 motorcycle tire for global rollout from 2027 and highlighted Lassa’s Wintus 3 winter tire, which secured TÜV SÜD certification and tested above competitor averages across multiple performance metrics.
- These tire launches suggest that Bridgestone is placing more emphasis on premium, higher-spec products for both adventure riders and light commercial fleets, with product development aligned to efficiency, wear life and performance demands.
- We will now look at how Bridgestone's premium tire focus, illustrated by the BATTLAX ADVENTURE A42 launch, shapes its investment narrative.
Bridgestone Investment Narrative Recap
To hold Bridgestone, you need to believe the premium and solutions tilt can keep earnings quality resilient even while tariffs, softer regions and restructuring drag on reported profit. In the near term the hinge is execution on cost savings and mix, not headline volume. The latest tire launches look aligned with that mix story rather than changing it.
The biggest swing factor still sits in external pressure on margins, especially U.S. tariffs and any renewed softness in North American truck and bus demand. Latin America profitability also remains fragile. The recent announcements do not materially change these risks, but they do provide more evidence on product depth at the higher end.
The BATTLAX ADVENTURE A42 launch is the clearest operational tie back to Bridgestone’s premium focus catalyst. Management is expanding a product line that already targets riders willing to pay for wet grip, wear life and comfort, which fits neatly with the goal of keeping premium and specialty segments as a larger slice of earnings.
What matters for you is execution from here. Premium tires currently carry higher adjusted operating margins than the group average, so the key question is whether Bridgestone can continue rolling out products like A42 and Wintus 3 while holding pricing power against low cost competitors and offsetting tariff and regional pressures through its cost programs.
Bridgestone's narrative projects ¥5,257.0b revenue and ¥466.1b earnings by 2029. This is based on an assumed 4.3% annual revenue increase and an earnings rise of about ¥58.1b from ¥408.0b today.
Uncover why Bridgestone's fair value indicates that Bridgestone is roughly in line with its current price.
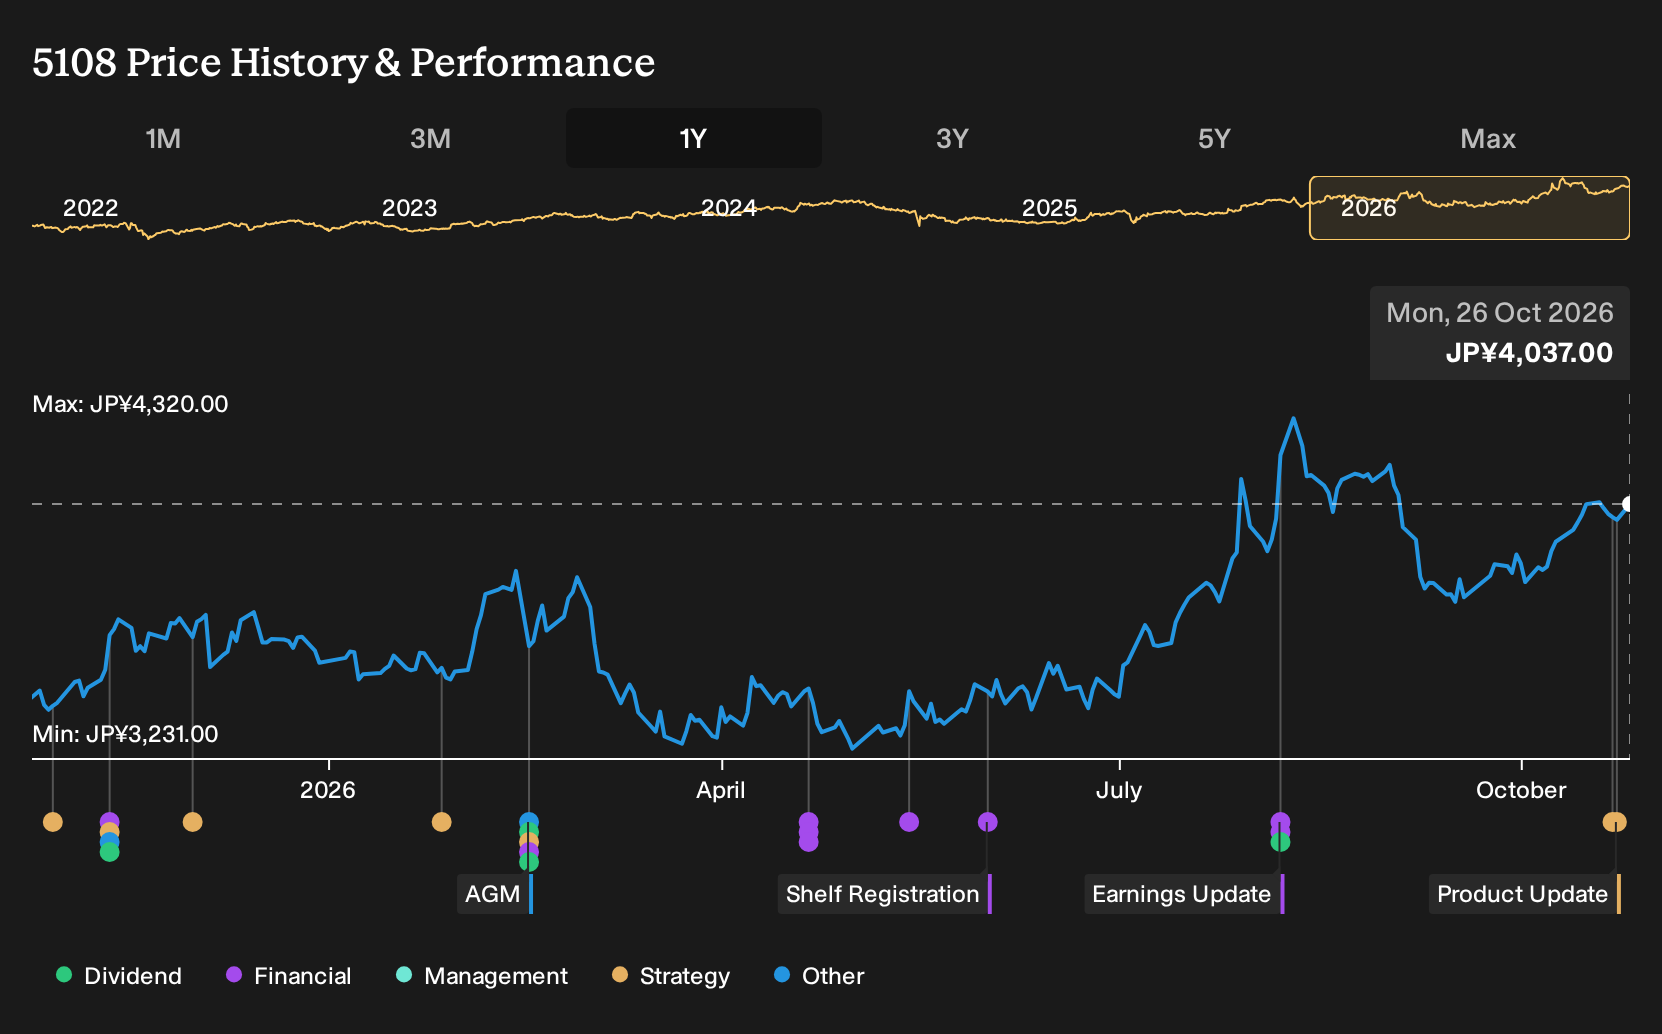
Exploring Other Perspectives
One alternate view says the real swing factor for Bridgestone is not premium tire launches like BATTLAX ADVENTURE A42 but pressure from weaker volumes and tariffs. The most cautious analysts were pencilling in revenue of about ¥4,851.4b and earnings near ¥368.9b by 2029 before this news, so their story is far more restrained. Use that gap to test your own expectations and ask whether fresh product wins like Wintus 3 could shift those forecasts over time.
Explore another Bridgestone fair value estimate, including one that suggests it could be worth just ¥4,020.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Bridgestone research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Bridgestone. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bridgestone's overall financial health at a glance.
Looking For More Investment Ideas Beyond Bridgestone?
If the Bridgestone story has sharpened your interest in quality and resilience, it can help to line it up against other opportunities that share similar traits but operate in different pockets of the market.
- For investors who want potential upside without paying a premium, scan through a 16 high quality undervalued stocks that pair solid fundamentals with prices that may not fully reflect them.
- If capital preservation sits high on your checklist, focus on a 22 resilient stocks with low risk scores that screens for businesses with steadier profiles and fewer red flags.
- When the goal is to back sturdier balance sheets and consistent execution, filter candidates with a list of solid balance sheet and fundamentals (23 results) that surfaces companies with cleaner financial footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com