


NRG Energy (NRG) Could Be 38% Below Fair Value Following Its Dividend Declaration
NRG Energy (NRG) kept its capital return story in focus after the Board declared a quarterly dividend of $0.475 per share (equivalent to $1.90 on an annualized basis), payable November 16, 2026.
Despite the fresh dividend, NRG Energy’s recent share price performance has been weak. The stock is down 7.11% over the past week and 27.63% over 90 days, and the year-to-date share price return has declined 44.45%, even though the 3-year total shareholder return sits at 130.90%. This suggests long-term holders are still well ahead, while near-term momentum has clearly faded as investors reassess natural gas exposure, carbon costs, and competition from renewables.
Scan how NRG Energy’s dividend story and recent pullback compares with other utilities by checking our hand-picked 42 power grid technology and infrastructure stocks.
NRG Energy now trades at a steep discount to both analyst targets and some intrinsic value estimates after the slide. Is this caution about gas exposure, carbon costs, and leverage a fair price or an overreaction?
Most Popular Narrative: 38% Undervalued
Against the last close of $92.31, the most widely followed narrative on NRG Energy pegs fair value at $150. It frames today’s pullback as a sizable discount that hinges on how well the enlarged power portfolio converts into lasting cash generation.
The acquisition had increased financial risk. But it had also increased cash-generating capacity. Both facts mattered.
See why 2 investors see NRG Energy as 38% undervalued.
According to John_Eric, the narrative’s $150 figure reflects a discounted cash flow style view that weighs NRG Energy’s enlarged generation fleet, projected free cash flow before growth investments of roughly $3.05b, and a discount rate of about 7.39%. That framework treats the current 38.5% discount to fair value as a bet on whether those assets can earn returns that justify roughly $23.1b of simplified net debt and ongoing capital needs.
The same storyline also stresses that dividend income is only one piece of the puzzle. With the payout described as not well covered by free cash flow and interest payments not well covered by earnings, the investment case in this narrative leans more on future cash conversion, potential debt reduction and project economics than on the current 2.06% yield.
For readers trying to benchmark NRG Energy against peers facing similar grid constraints and capital intensity, that narrative effectively frames the stock as an experiment in capital allocation at scale rather than a simple yield play.
Result: Fair Value of $150 (UNDERVALUED)
Still, the enlarged debt load and weaker recent share performance could quickly undercut the 38% undervalued case if cash conversion or power pricing disappoints.
Find out about the key risks to this NRG Energy narrative.
Another View on NRG Energy’s Valuation
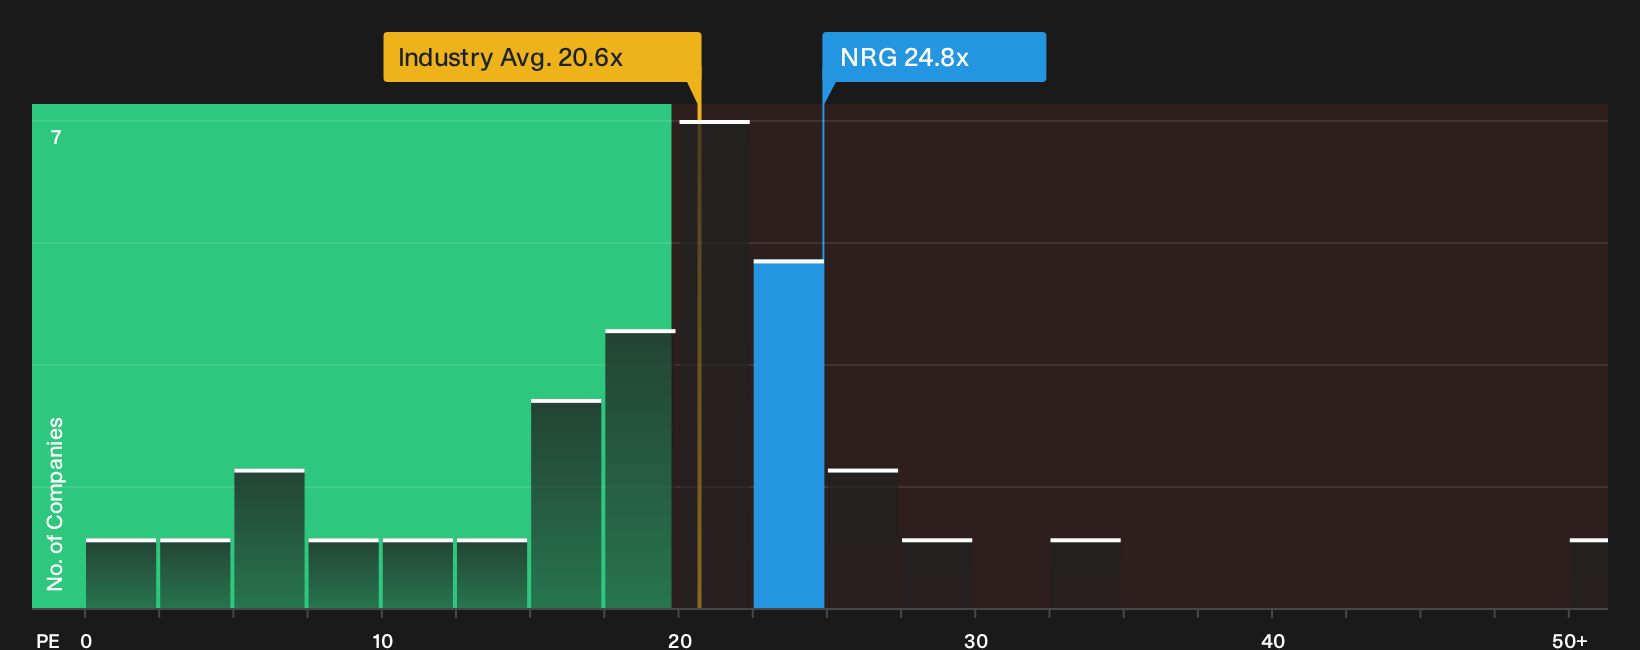
That 38% undervalued storyline leans heavily on cash flow and a fair value of $150. A different lens looks at NRG Energy’s current P/E of 24.8x, which sits above both peers at 17.5x and the US Electric Utilities industry at 20.6x, even though the fair ratio is 29.1x. For investors, that gap raises a simple question: is this a quality premium worth paying, or extra valuation risk if expectations slip?
To see how that earnings multiple stacks up in more detail, including where the market could trend toward the fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the recent NRG Energy story. Price and sentiment can change quickly, so pull up the data, test the assumptions, and weigh the 3 key rewards and 2 important warning signs.
Looking for more NRG Energy investment ideas?
If NRG Energy has you rethinking your watchlist, now is the time to widen the net and pressure test your next moves with fresh, high quality ideas.
- Target stability first and stress test your downside by scanning a curated set of resilient companies through the 30 resilient stocks with low risk scores.
- Hunt for quality at a discount by reviewing the 28 high quality undervalued stocks that combine stronger fundamentals with pricing that may leave room for upside.
- Build a more durable income stream and compare NRG Energy's payout profile with a hand picked 5 dividend fortresses that focus on higher yields.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com