


What Altra Fastigheter (OM:ALTRA)'s Higher Earnings Means For Shareholders
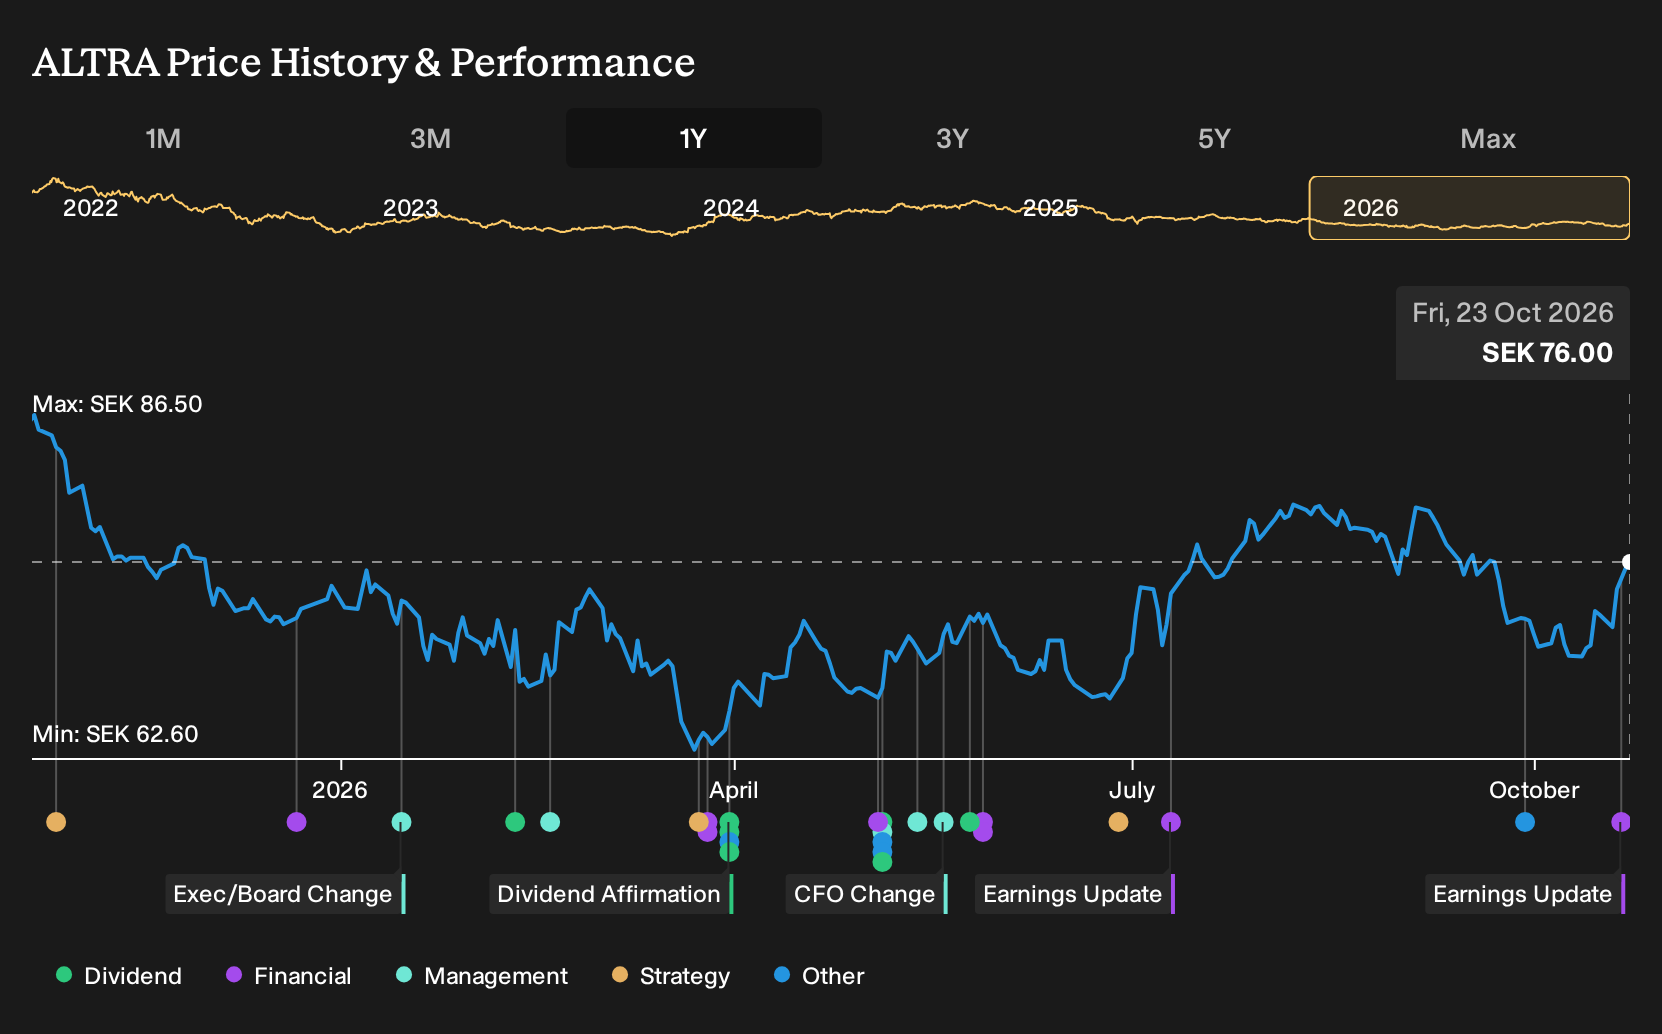
- Altra Fastigheter reported third quarter 2026 revenue of SEK 871 million and net income of SEK 575 million, while completing a SEK 919.01 million buyback of 11,816,649 shares representing 6.2% of its share capital announced in May 2026.
- The combination of materially higher earnings per share from continuing operations and a reduced share count indicates a sharper focus on profitability per share rather than pure top line expansion.
- We will examine how Altra Fastigheter's investment narrative is affected by sharply higher earnings per share in the latest quarterly update.
Altra Fastigheter Investment Narrative Recap
For a shareholder in Altra Fastigheter, the core belief is that a transaction intensive Nordic property portfolio can keep generating reliable cash flows while management actively rotates assets and manages vacancies. The latest quarter showed higher net income and earnings per share even though revenue was slightly lower, which points to tighter cost control and mix effects rather than volume growth.
In the short term, the key swing factor is still leasing and occupancy, especially with earlier comments about higher vacancy and weaker Finnish performance. Recent profit strength does not remove that risk. It simply gives more breathing room if rental income softens or refinancing terms stay demanding and interest cover remains tight.
The third quarter earnings release is the clearest reference point for this update. Revenue of SEK 871 million and net income of SEK 575 million, alongside basic earnings per share from continuing operations of SEK 3.1, indicate that Altra Fastigheter is currently converting its property income into profit efficiently, even with relatively flat top line trends.
That profitability profile interacts directly with the completed SEK 919.01 million share buyback. A smaller share count magnifies earnings per share, which can matter for catalysts tied to investor perception and to any future capital allocation choices. It also raises the bar on execution, because weaker occupancy, Finnish exposure issues or higher interest costs would be felt per share more quickly.
Altra Fastigheter's narrative projects SEK 3.7b revenue and SEK 1.7b earnings by 2029. This projection is based on 1.0% yearly revenue growth and an earnings increase of roughly SEK 1.0b from SEK 693.0m today.
Uncover why Altra Fastigheter's fair value indicates a potential 14% upside to its current price that could narrow quickly.
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community cluster between SEK 71.02 and SEK 89.20, so you are looking at a fairly tight band of retail expectations on Altra Fastigheter. When you set that against vacancy risk, Finnish exposure and a recently completed buyback, you get plenty of room for sharply different opinions.
Explore 2 other Altra Fastigheter fair value estimates, including one that suggests as much as 7% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Altra Fastigheter research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Altra Fastigheter. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Altra Fastigheter's overall financial health at a glance.
Looking For More Investment Ideas Beyond Altra Fastigheter?
If Altra Fastigheter has sharpened your focus on earnings quality, capital returns and balance sheet strength, it can be useful to compare it with other businesses that share similar traits. The Simply Wall St Screener lets you filter for companies that match the kind of risk and return profile you want, so you can build a watchlist that fits your own approach.
- If you want income to play a bigger role in your portfolio, start with companies that behave like cash machines and review 225 dividend fortresses that might fit a yield focused strategy.
- If capital preservation and steadier profiles matter more to you, filter for financially robust businesses and work through the 223 resilient stocks with low risk scores to see what fits your comfort level.
- If you are hunting for quality at a measured price rather than chasing headlines, look across companies with solid fundamentals and compare those in the list of solid balance sheet and fundamentals (207 results) to your existing holdings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com