


Undiscovered Gems in Canada to Explore This October 2026
As of October 2026, the Canadian market has been navigating a mixed landscape with small-cap stocks experiencing fluctuations influenced by broader economic indicators and shifts in investor sentiment. In this dynamic environment, identifying promising small-cap stocks requires a keen eye for companies that demonstrate resilience and potential growth amidst these changing conditions.
Top 10 Undiscovered Gems With Strong Fundamentals In Canada
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Total Energy Services | 3.93% | 18.21% | 37.46% | ★★★★★★ |
| Torex Gold Resources | NA | 12.76% | 20.04% | ★★★★★★ |
| Wesdome Gold Mines | NA | 34.13% | 46.06% | ★★★★★★ |
| Thor Explorations | NA | 38.45% | 61.95% | ★★★★★★ |
| Alvopetro Energy | 18.59% | 7.72% | 6.43% | ★★★★★☆ |
| Hydreight Technologies | 22.28% | 71.66% | 59.41% | ★★★★☆☆ |
| Aris Mining | 28.26% | 24.20% | 5.42% | ★★★★☆☆ |
| Kolibri Global Energy | 20.09% | 25.10% | -21.44% | ★★★★☆☆ |
| Rio2 | 22.38% | 105.97% | 53.08% | ★★★☆☆☆ |
| Journey Energy | 11.76% | 6.14% | -39.79% | ★★★☆☆☆ |
Let's uncover some gems from our specialized screener.
Aris Mining (TSX:ARIS)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Aris Mining Corporation is involved in acquiring, exploring, developing, and operating gold properties across Canada, Colombia, and Guyana with a market capitalization of approximately CA$4.47 billion.
Operations: Aris Mining generates revenue primarily from its Marmato and Segovia segments, with the latter contributing $1.14 billion. The company's cost structure and financial performance are influenced by these operations, with a focus on optimizing returns from its gold properties.
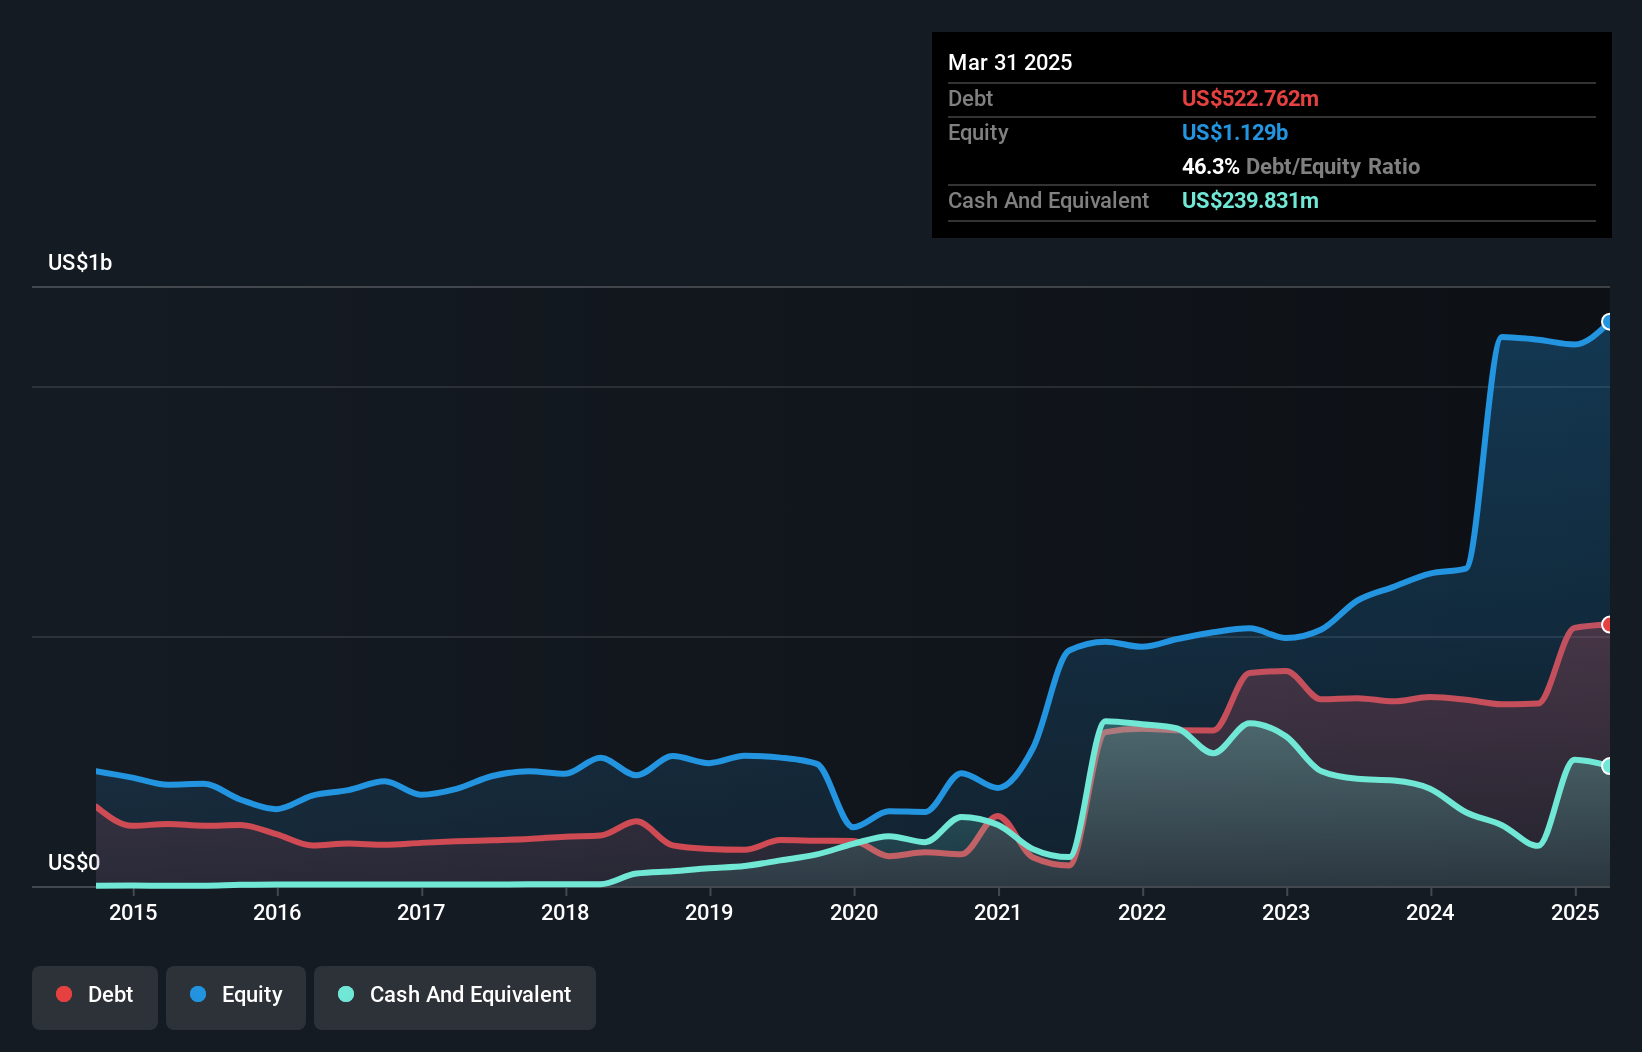
Aris Mining, a notable player in the Canadian mining sector, has shown remarkable earnings growth of 5501.6% over the past year, outpacing the industry average of 125.6%. The company trades at a significant discount to its estimated fair value and maintains a satisfactory net debt to equity ratio of 4.2%. Recent developments include increased gold production with third-quarter output reaching 69.3 koz and nine-month sales totaling 215.3 koz compared to last year's figures. Despite strong growth prospects driven by projects like Segovia and Marmato, geopolitical risks tied to Colombian operations remain a concern for future stability.
B2Gold (TSX:BTO)
Simply Wall St Value Rating: ★★★★★☆
Overview: B2Gold Corp. is a Canadian gold producer with operations in multiple countries and has a market capitalization of CA$8.84 billion.
Operations: B2Gold generates revenue primarily from its Fekola Mine, contributing $2.36 billion, followed by the Masbate Mine at $899.26 million and the Otjikoto Mine at $606.64 million. The company's net profit margin reflects its financial performance in managing costs relative to its revenue streams.
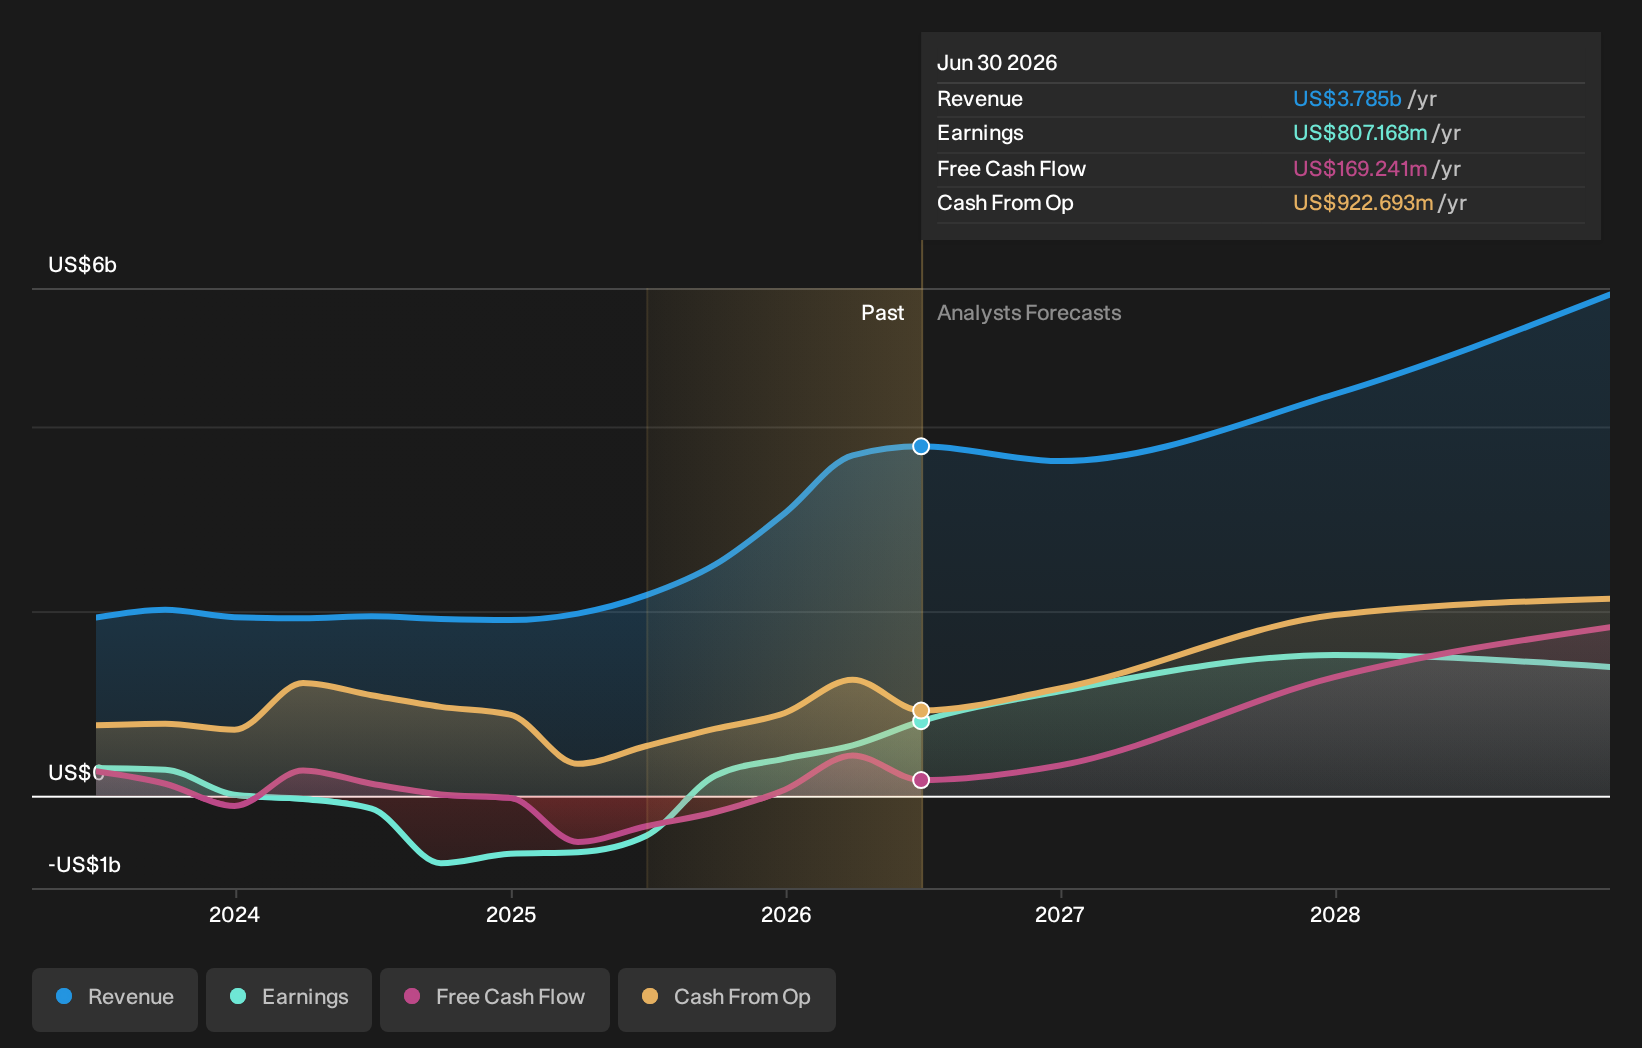
B2Gold, a player in the mining sector, has recently made strides with its exploration activities in Canada's Back River Gold District. The company allocated $51 million to its 2026 exploration program, completing 27,493 meters of drilling by August. B2Gold's net debt to equity ratio stands at a satisfactory 2.9%, reflecting prudent financial management. In the second quarter of 2026, the company reported net income of US$417 million compared to US$154 million last year and repurchased 15 million shares for CAD74 million. Trading at a significant discount to its estimated fair value suggests potential upside for investors seeking undervalued opportunities.
- Navigate through the intricacies of B2Gold with our comprehensive health report here.
Explore historical data to track B2Gold's performance over time in our Past section.
Total Energy Services (TSX:TOT)
Simply Wall St Value Rating: ★★★★★★
Overview: Total Energy Services Inc. is an energy services company with operations in Canada, the United States, Australia, and internationally, and it has a market capitalization of CA$1.39 billion.
Operations: Total Energy Services generates revenue from four main segments: Compression and Process Services (CA$634.50 million), Contract Drilling Services (CA$362.27 million), Well Servicing (CA$130.72 million), and Rentals and Transportation Services (CA$78.79 million).
Total Energy Services, a nimble player in the energy services industry, showcases impressive financial health with a debt to equity ratio dropping from 41.4% to 3.9% over five years and earnings growth of 35% last year outpacing the industry's -6%. The company repurchased 882,428 shares for CA$18.13 million, reflecting confidence in its valuation which is currently trading at a significant discount to estimated fair value. With EBIT covering interest payments by 41 times and no concerns about cash runway due to profitability, Total Energy appears well-equipped for future challenges despite recent insider selling activity.

Taking Advantage
- Click through to start exploring the rest of the 12 TSX Undiscovered Gems With Strong Fundamentals now.
- Have a stake in these businesses? Integrate your holdings into Simply Wall St's portfolio for notifications and detailed stock reports.
- Simply Wall St is a revolutionary app designed for long-term stock investors, it's free and covers every market in the world.
Ready To Venture Into Other Investment Styles?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com