


How Record Silver Output Will Impact Hecla Mining Stock Investors
- Hecla Mining recently reported record silver production alongside lower all in sustaining costs and a stronger cash balance, highlighting a period of operational efficiency and tighter cost control.
- The combination of high output and reduced sustaining costs suggests Hecla Mining may have more flexibility in funding future projects and managing balance sheet priorities without relying as heavily on external capital.
- This analysis reviews how Hecla Mining's investment narrative is affected by record silver output paired with meaningfully lower all in sustaining costs.
Compare Hecla Mining's record output story with other precious metals producers by scanning our curated list of 10 top silver producer stocks that show similar production and cost profiles.
Hecla Mining Investment Narrative Recap
To own Hecla Mining, you need to believe its record silver output and lower all in sustaining costs can be maintained while major assets like Greens Creek, Lucky Friday, and Keno Hill stay on track operationally. The near term swing factor is how reliably that high production converts into steady surplus cash as capital needs ebb and flow.
The biggest risk right now sits around capital intensity and permitting at projects such as Keno Hill and the impact of declining grades at older mines like Casa Berardi. The latest cost improvements help, but they do not remove the possibility that higher spending or regulatory delays could squeeze future free cash flow.
The most relevant recent development is the combination of record silver production and lower all in sustaining costs alongside a stronger cash balance. That mix directly feeds into the key catalyst investors are watching, which is whether Hecla Mining can fund mine development, technology spending, and potential deleveraging mostly from internal cash generation.
If that operational trend holds, pressure to rely on higher risk funding or fresh equity could ease. This matters for a business already flagged for dilution and elevated capital requirements. Execution still needs to line up around throughput at Keno Hill, ESG compliance, and cost control to keep this cash flow story intact.
Hecla Mining's analyst narrative points to revenue of US$1.6b and earnings of US$449.7m by 2029. This assumes revenue declining at 3.3% per year and an earnings decrease of about US$102.8m from current earnings of US$552.5m.
Uncover how Hecla Mining's fair value indicates a 59% potential upside to its current price.
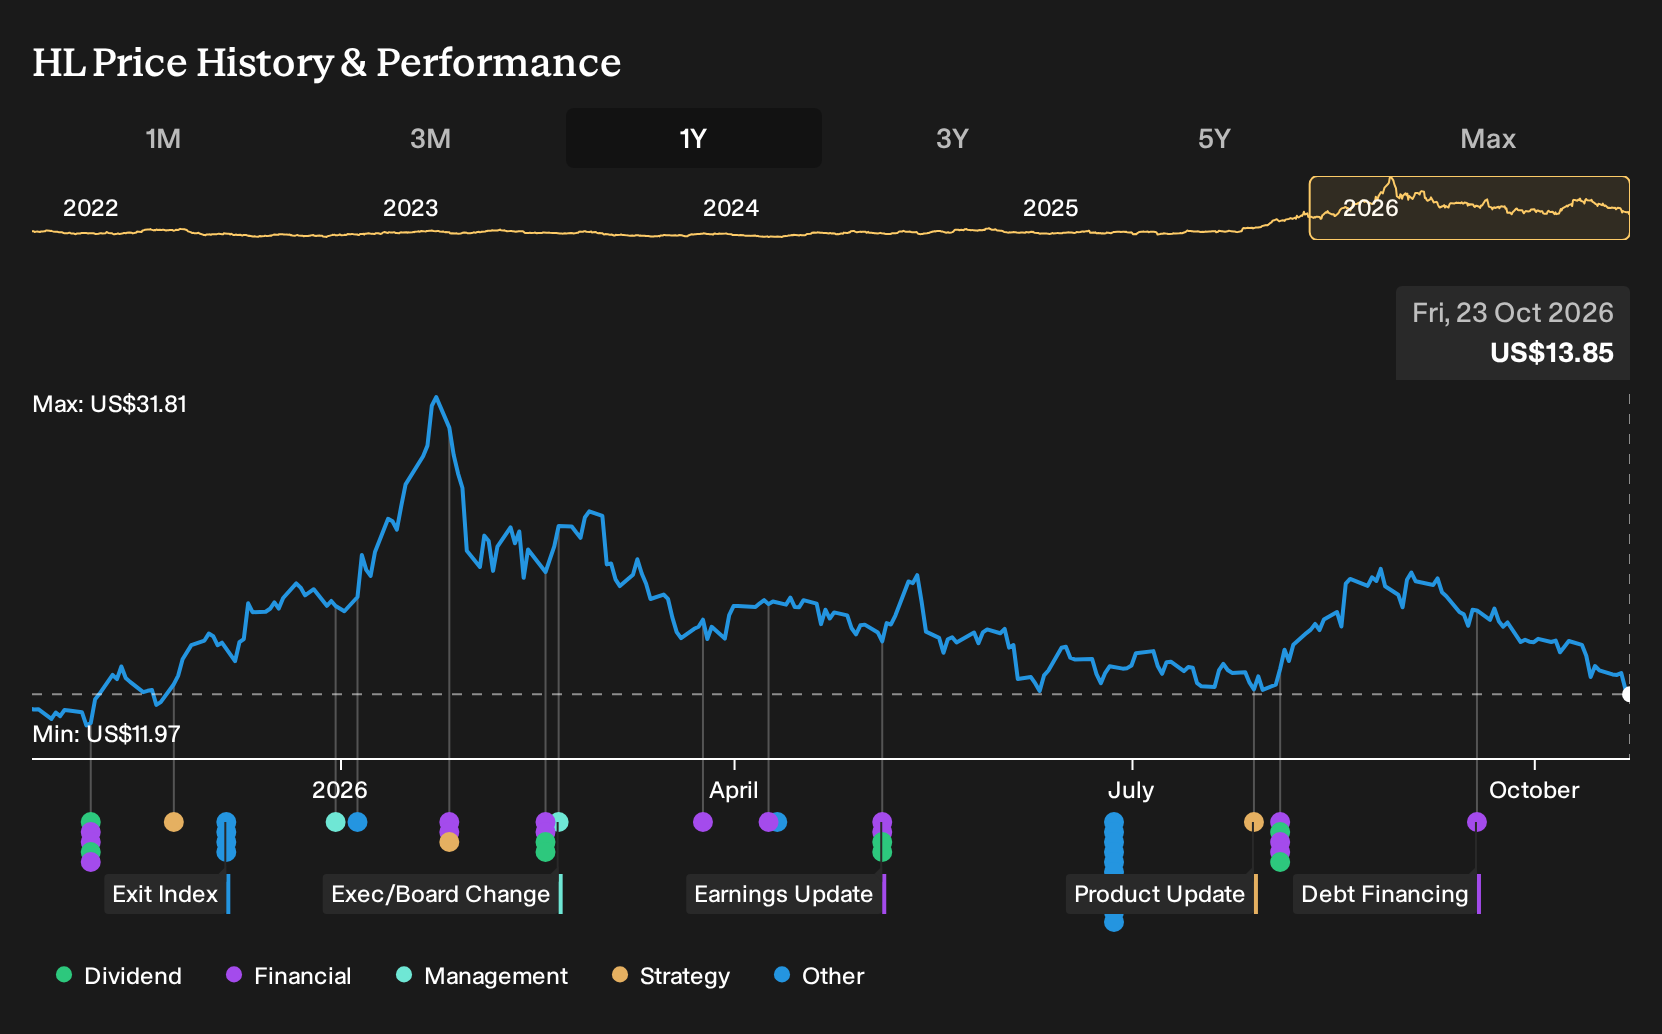
Exploring Other Perspectives
Some of the most optimistic analysts focus on Hecla Mining’s sector consolidation potential. Before this record output news, the bullish camp was already pencilling in US$1.6b of revenue and around US$449.5m of earnings by 2029, with a much higher implied P/E. You can now ask whether this fresh production surprise shifts those expectations again.
Explore 4 other Hecla Mining fair value estimates, including one that suggests potential upside of up to 122% from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Hecla Mining research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Hecla Mining. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hecla Mining's overall financial health at a glance.
Looking for more investment ideas beyond Hecla Mining?
If the Hecla Mining story has sharpened your focus on quality and risk, it can be useful to widen the lens and compare it with other companies that share some of the same financial traits.
- For investors who care most about resilient balance sheets and steady fundamentals, start with this list of solid balance sheet and fundamentals (24 results) to see which businesses align with that profile.
- If you are hunting for mispriced opportunities backed by solid financials, scan a 28 high quality undervalued stocks that match a blend of quality metrics and valuation filters.
- When your priority is limiting downside risk, focus on a 30 resilient stocks with low risk scores and see which tickers the model flags as having more defensive characteristics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com