


First Horizon (FHN) Reports A Third Quarter Loss, Is The Valuation Case Still Intact?
First Horizon (FHN) moved into focus after third quarter 2026 results showed a net loss of US$83 million, a swing from profit a year earlier, along with higher net charge-offs and ongoing funding cost pressure.
The third quarter loss and higher net charge-offs have come as First Horizon’s share price has eased around 10% over the past three months, even though the 1-year total shareholder return of 14.8% and roughly 3-year total shareholder return above 100% point to longer term momentum that is still intact.
Scan how First Horizon compares with other banks facing similar margin and credit pressures by reviewing the hand-picked list of solid balance sheet and fundamentals (24 results) in the sector.
Bulls point to First Horizon’s long run of positive total returns. Bears focus on the fresh quarterly loss and rising charge-offs. Which side does current valuation evidence support as you weigh the next move?
Most Popular Narrative: 15% Undervalued
First Horizon’s most followed valuation storyline puts fair value at about $27.45 using a 7.24% discount rate, compared with the recent $23.44 share price. This frames the Q3 loss against a longer term earnings and capital plan.
First Horizon is still targeting a multi year, $100m plus pre tax pre provision revenue uplift from deeper commercial relationships, with management now indicating progress of roughly 30% to 50% toward that goal, which can continue to support revenue and PPNR.
See why 7 investors see First Horizon as 15% undervalued.
Result: Fair Value of $27.45 (UNDERVALUED)
Still, the narrative comes under pressure if funding costs keep edging toward wholesale levels or if the planned pretax, pre-provision uplift stalls before completion.
Find out about the key risks to this First Horizon narrative.
Another View: How First Horizon Screens On Earnings
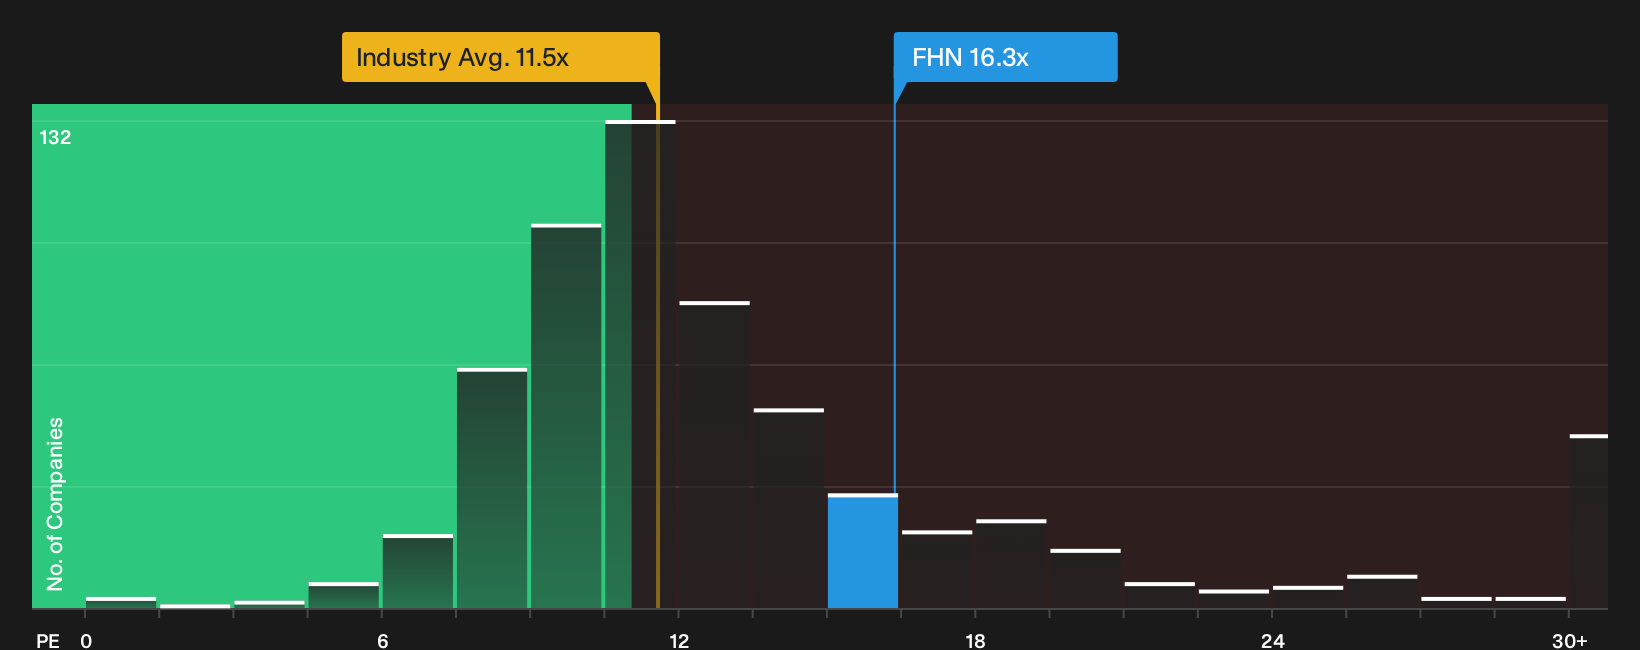
On a simple P/E yardstick, First Horizon looks less forgiving. The stock trades on 16.3x earnings compared with 11.5x for the US Banks industry and 11x for close peers, even though the fair ratio model suggests 16.8x as a level the market could move toward.
That means the valuation gap cuts both ways. There is a cushion versus the fair ratio, yet a clear premium to sector and peer averages that could compress if sentiment cools or expand if the recent setback proves temporary.
To see how those trade offs show up in the numbers, have a look at the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around First Horizon is mixed, and that is exactly when fresh data matters most, so check the underlying metrics and form your own stance. To see the optimistic angles analysts are watching around the business, review the 3 key rewards
Looking for more investment ideas beyond First Horizon?
Do not stop your research with First Horizon. The best opportunities often sit just outside the obvious choices, and a fresh watchlist can change your next decision.
- Target resilient balance sheets and steadier risk profiles by reviewing the 30 resilient stocks with low risk scores that filters for financial strength first.
- Hunt for quality at a discount by scanning the 29 high quality undervalued stocks that highlights stocks with strong fundamentals trading below assessed worth.
- Lock in potential income streams by checking the 5 dividend fortresses that focuses on higher yielding payouts with staying power.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com