


Swedish Orphan Biovitrum (OM:SOBI) Could Be 9% Below Fair Value On TRYNGOLZA Win
TRYNGOLZA decision reshapes the conversation around Swedish Orphan Biovitrum
The CHMP’s early positive opinion on TRYNGOLZA as an adjunct therapy for severe hypertriglyceridemia puts Swedish Orphan Biovitrum (OM:SOBI) in focus as investors weigh RNA-based treatment exposure.
Recent trading backs up the TRYNGOLZA headline, with a 7 day share price return of 4.08% and a year to date share price gain of 37.47% hinting at building momentum. Meanwhile, the 1 year total shareholder return of 42.56% and 5 year total shareholder return of 104.08% show Swedish Orphan Biovitrum has already rewarded patient holders over time.
Scan beyond Swedish Orphan Biovitrum and see how other potential breakouts in complex therapies line up in our hand picked 124 healthcare AI stocks list.
After a sharp year to date move and with a TRYNGOLZA catalyst now in play, Swedish Orphan Biovitrum forces a choice. Lean into the current price, or wait and hope the valuation gives you a second chance?
Most Popular Narrative: 9% Undervalued
At a last close of SEK454.20 against a narrative fair value of about SEK500.92, Swedish Orphan Biovitrum is framed as modestly undervalued, with the TRYNGOLZA decision fitting into a much larger rare disease build out rather than a single product story.
Continued roll out of Swedish Orphan Biovitrum’s high-value rare disease portfolio, including Altuvoct, Aspaveli, Gamifant, Tryngolza and gout assets, with management aiming to reach around SEK 55b of revenue and an adjusted EBITA margin in the high 30s by 2030, points to further potential gains in revenue and earnings.
See why 11 investors see Swedish Orphan Biovitrum as 9% undervalued.
Result: Fair Value of SEK500.92 (UNDERVALUED)
Still, the story around Swedish Orphan Biovitrum can change quickly if key late stage launches stumble, or if international pricing and reimbursement decisions drag out longer than expected.
Find out about the key risks to this Swedish Orphan Biovitrum narrative.
Another View: What Multiples Say About Swedish Orphan Biovitrum
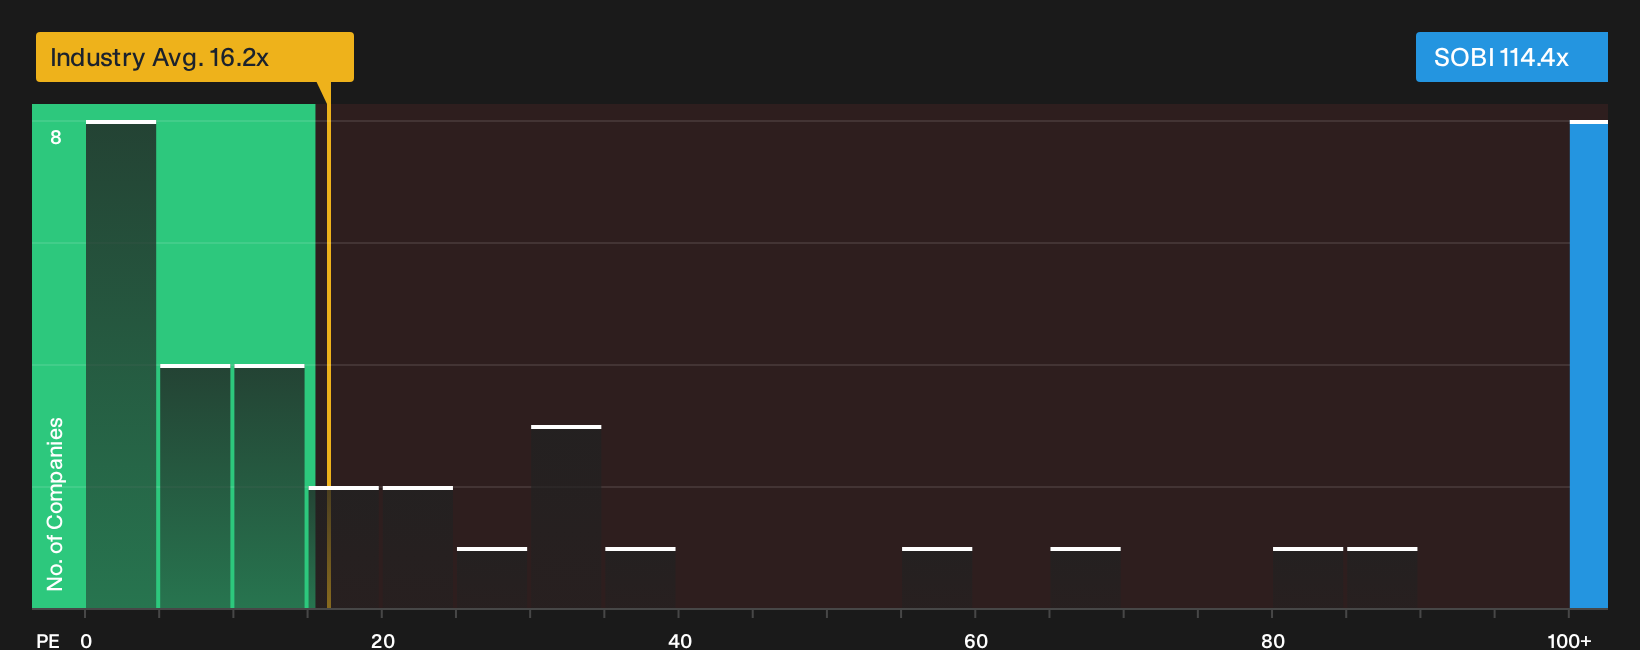
That 9% narrative discount on Swedish Orphan Biovitrum looks modest once the P/E is brought into focus. The shares trade on around 114.4x earnings versus 56.9x for peers and 16.2x for the wider European biotech group, while the fair ratio model points to 58.2x as a level the market could move toward over time. That gap suggests plenty of valuation risk if execution slips, so the real question is which lens you trust more when the story gets bumpy.
For a closer look at how this pricing stacks up against the earnings profile and peer set, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Reading this, you can sense both optimism and caution around Swedish Orphan Biovitrum. Consider reviewing the numbers yourself and weighing the 2 key rewards and 3 important warning signs carefully.
Looking for more investment ideas beyond Swedish Orphan Biovitrum?
If Swedish Orphan Biovitrum has your attention, do not stop here. Broadening your opportunity set now can help you spot tomorrow’s winners before the crowd.
- Target potential mispricings by scanning companies that combine quality fundamentals with appealing entry points using the 194 high quality undervalued stocks.
- Strengthen your income stream by reviewing businesses with robust payouts and higher yields through the 229 dividend fortresses.
- Prioritize resilience by focusing on financially sound operators with strong balance sheets via the list of solid balance sheet and fundamentals (207 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com